


Profitability concerns put Global Industrial under the spotlight
Global Industrial (GIC) has drawn renewed attention after recent commentary highlighted revenue growth of 3.3% over the last two years, flat earnings per share, and weakening returns on capital that raise questions about the durability of its profitability.
Recent trading has added fuel to the debate around Global Industrial. The share price has climbed 26.6% over the past 90 days and delivered a 51.1% year to date share price return, while the 1 year total shareholder return of 32.1% suggests momentum has been building despite concerns about profitability quality.
Compare Global Industrial's recent momentum against a hand picked group of companies with sturdier balance sheets and profitability profiles by scanning the 30 resilient stocks with low risk scores now.
Profitability questions now meet a share price that has already sprinted ahead. The key issue is whether Global Industrial still offers enough potential reward to justify that risk as valuation comes under closer scrutiny next.
Most Popular Narrative: 5.9% Overvalued
Global Industrial last closed at $44.46 against a widely followed fair value estimate of $42.00. The story now hinges on whether its digital platform and account mix can carry enough earnings power to justify that premium.
The company is intentionally shifting its go to market strategy to focus on higher value strategic accounts, increasing customer specialization, and deepening relationships, which is likely to boost revenue growth and support gross margins through improved customer retention and share of wallet gains.
Efforts to expand product categories and broaden offerings, particularly in MRO and industrial supplies, now include wider MRO and consumables assortments and more vendor drop ship partnerships, which can lift revenue and earnings as Global Industrial captures a greater portion of customer spend.
See why 10 investors see Global Industrial as 6% overvalued.
Result: Fair Value of $42 (OVERVALUED)
Still, Global Industrial faces pressure if tariffs keep input costs high or if faster growing distributors and large digital procurement platforms limit its ability to gain share.
Find out about the key risks to this Global Industrial narrative.
Another View: What P/E Says About Global Industrial
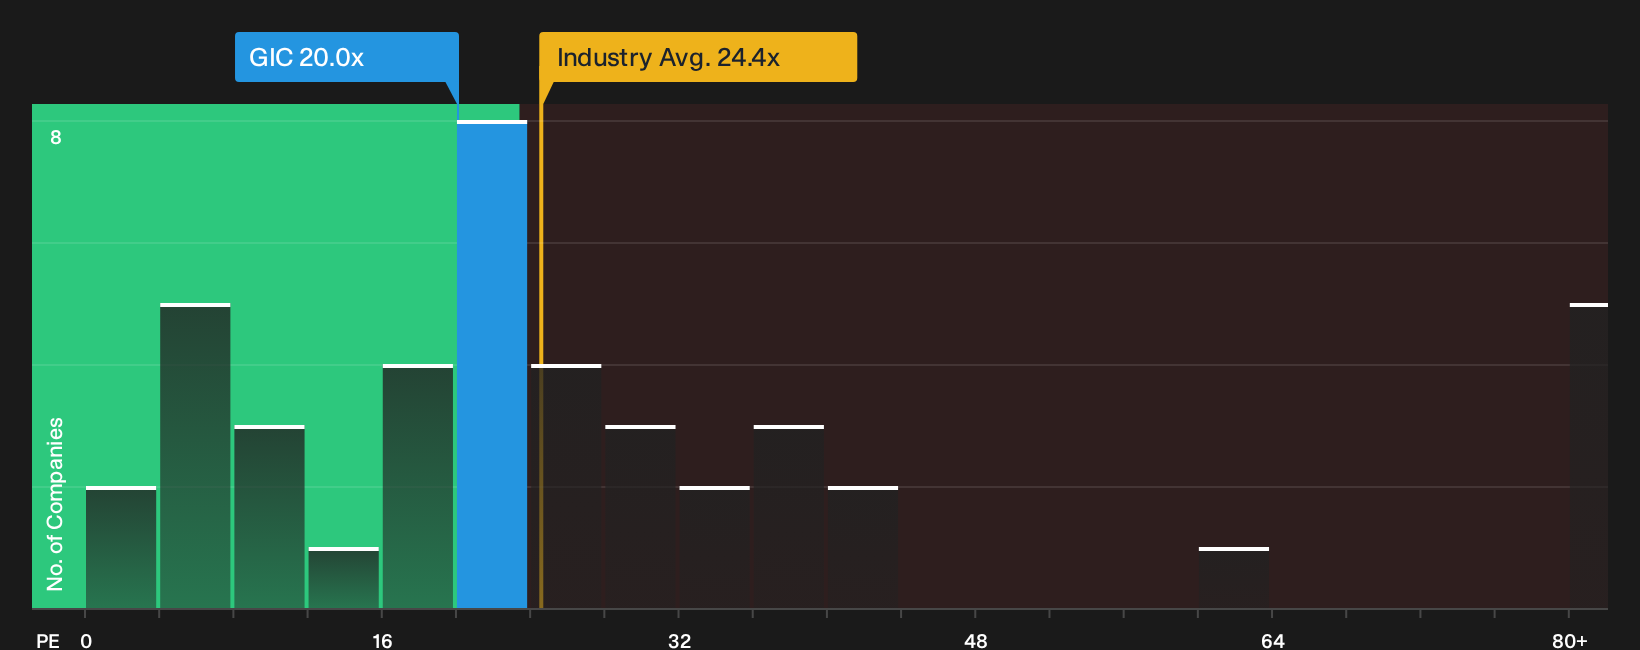
The first narrative leans on a fair value of $42, yet the P/E picture for Global Industrial tells a different story. The shares trade on 20x earnings, below the US Trade Distributors industry at 24.6x and sharply below peer averages of 79.2x, but still above a fair ratio of 13.6x. That gap points to a stock that screens cheaper than rivals while still carrying valuation risk if sentiment cools or growth expectations reset.
To pressure test that earnings based view against the underlying numbers, take a closer look at how the valuation stacks up using our detailed ratio workup, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Global Industrial story can sound mixed, with risks on one side and clear upside arguments on the other. Move quickly, weigh the evidence yourself, and then stress test that view against the 3 key rewards and 2 important warning signs.
Looking for more Global Industrial style investment ideas?
Do not stop your research with Global Industrial alone. Broaden your watchlist using targeted tools that surface fresh opportunities before they become crowded trades.
- Scan for quality at a discount by checking companies that pass our 27 high quality undervalued stocks and see which businesses look mispriced based on their fundamentals.
- Strengthen your downside protection by focusing on balance sheet resilience through the list of solid balance sheet and fundamentals (25 results), so fragile finances do not catch you off guard.
- Get ahead of the crowd by tracking potential future leaders hidden in plain sight with the 21 high quality undiscovered gems before they move onto everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com