


French bond yields above 5% and a weaker euro have turned short-duration cash and liquidity into more than just a parking bay for idle funds. Sudden shifts in sovereign risk and funding costs are quietly reshaping where investors feel comfortable holding euros, and where they do not. This article unpacks how that backdrop affects euro money market and cash-management providers, and identifies 3 stocks that appear positively exposed to this new rate environment.
The three stocks covered next are only a sample from this corner of euro cash and liquidity markets. The full screen surfaced 14 more companies with equally detailed narratives that are not included here.
If you want to identify, compare and analyze the full field of short-duration euro money market and cash-management providers, head straight to the Short-Duration Euro Money Market and Cash-Management Providers screener.
Crédit Agricole (ENXTPA:ACA)
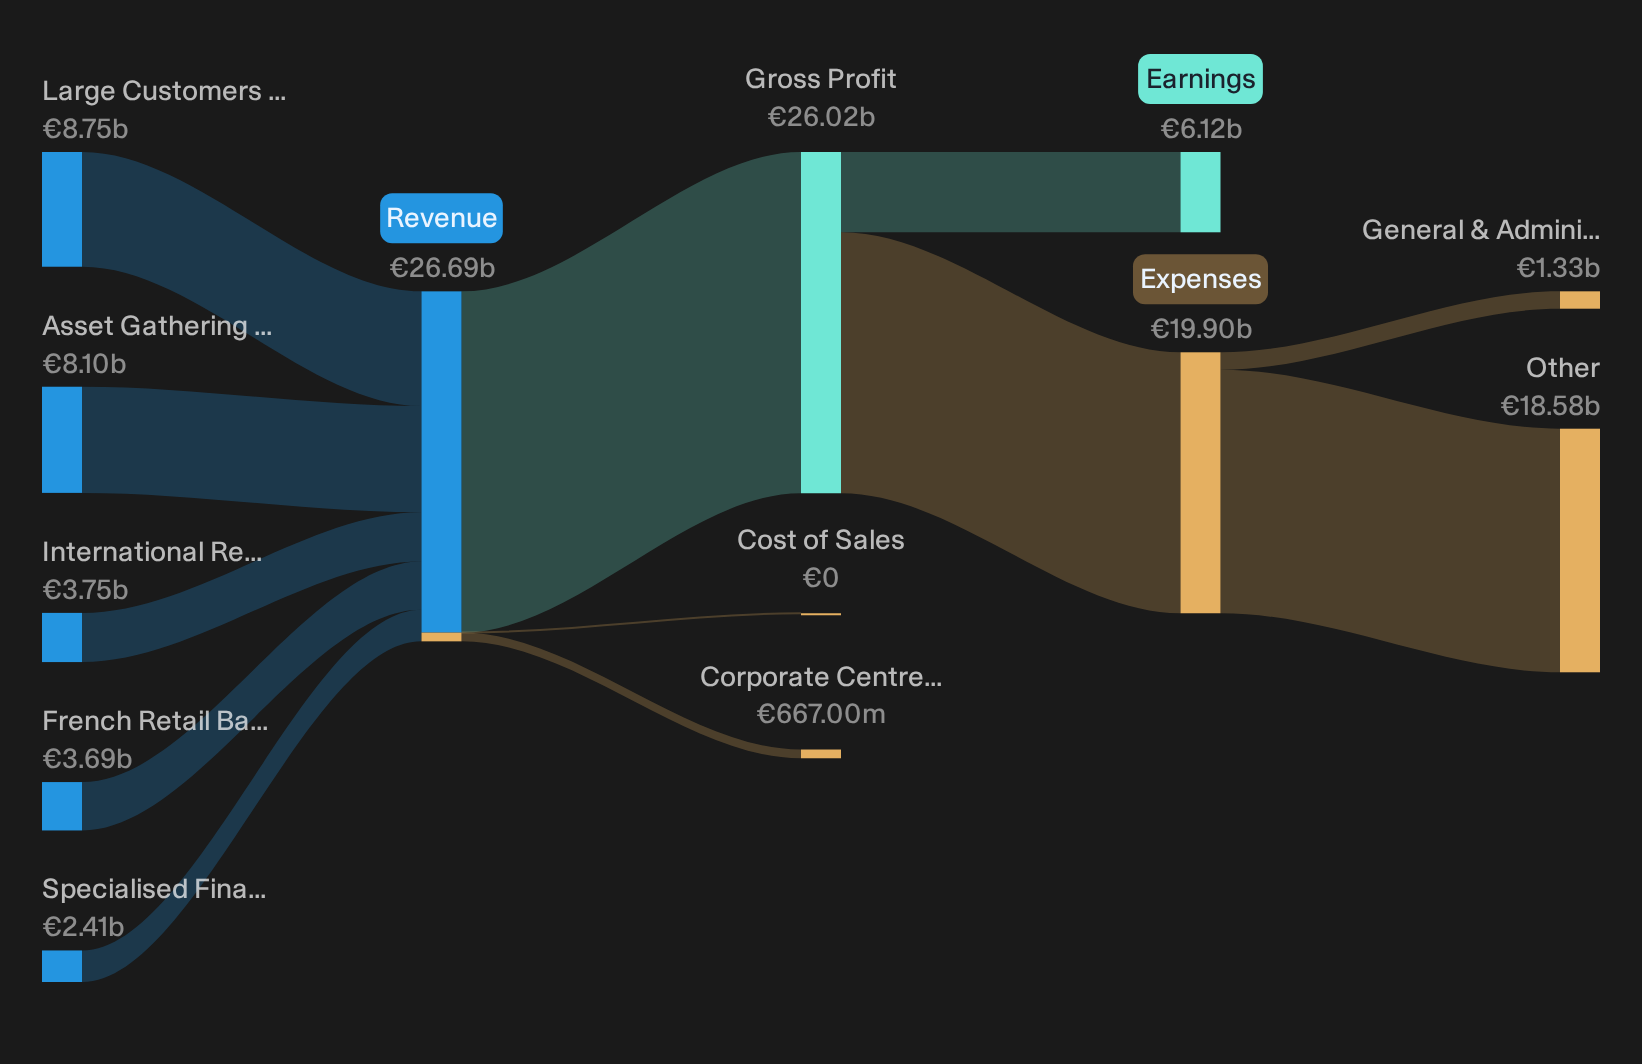
Crédit Agricole is a €44.7b French universal bank whose broad retail and asset-gathering operations make it a natural player in euro cash and liquidity, with revenue spread across Asset Gathering (€8.1b), Large Customers (€8.7b), French and international retail (€7.4b) and Specialized Financial Services (€2.4b).
For short-duration euro cash and liquidity, Crédit Agricole matters because it couples a deep retail and corporate footprint with large-scale savings and asset management platforms that can channel deposits into money market and cash products at speed.
Crédit Agricole's ongoing investments in digital banking and fintech, including the European digital savings platform in Germany and the wider roll out of fully digital client journeys, are building on the existing digital program and are expected to support lower cost to income and stronger net margins.
What happens to those margins if one unresolved pressure on its funding mix starts to bite harder than current sentiment implies?
If that funding squeeze is what worries you, start with the full narrative for Crédit Agricole to see how Crédit Agricole's cash engine could accelerate or stall from here.
DWS Group GmbH KGaA (XTRA:DWS)
DWS Group GmbH KGaA is a Frankfurt based asset manager in the screener because its fund range likely includes euro money market and short-duration liquidity products, with all of its €4.8b revenue coming from asset management and a market value of about €12.7b.
For short-duration cash and liquidity, DWS Group matters because it can redirect risk-off flows into its money market style products while also leaning on broader ETFs and alternatives as investors reassess where to park euro cash.
The expansion of DWS Group GmbH KGaA's Xtrackers ETF and Alternatives businesses is linked to demand from the global middle class and rising wealth, particularly in Asia and emerging markets, for scalable, diversified investment solutions that can support higher net flows and management fee revenue.
What happens to those fee streams if one quiet shift in client product mix pushes harder on pricing than current expectations allow for?
If that pricing pressure is the real swing factor, the full narrative for DWS Group GmbH KGaA lays out how DWS Group could still turn mix shifts into accelerating earnings power.

KBC Group (ENXTBR:KBC)
KBC Group is a Brussels based bank insurer with asset management that channels Benelux retail and SME deposits into a full suite of euro cash and savings products, generating €7.4b revenue in Belgium, €2.7b in the Czech Republic and €2.8b across Hungary, Bulgaria and Slovakia, and carrying a market value of about €45.1b.
In a world where euro deposit holders are moving up the yield curve but want to keep risk on a short leash, KBC Group offers a vertically integrated mix of banking, insurance and asset management aimed squarely at everyday savers and smaller businesses.
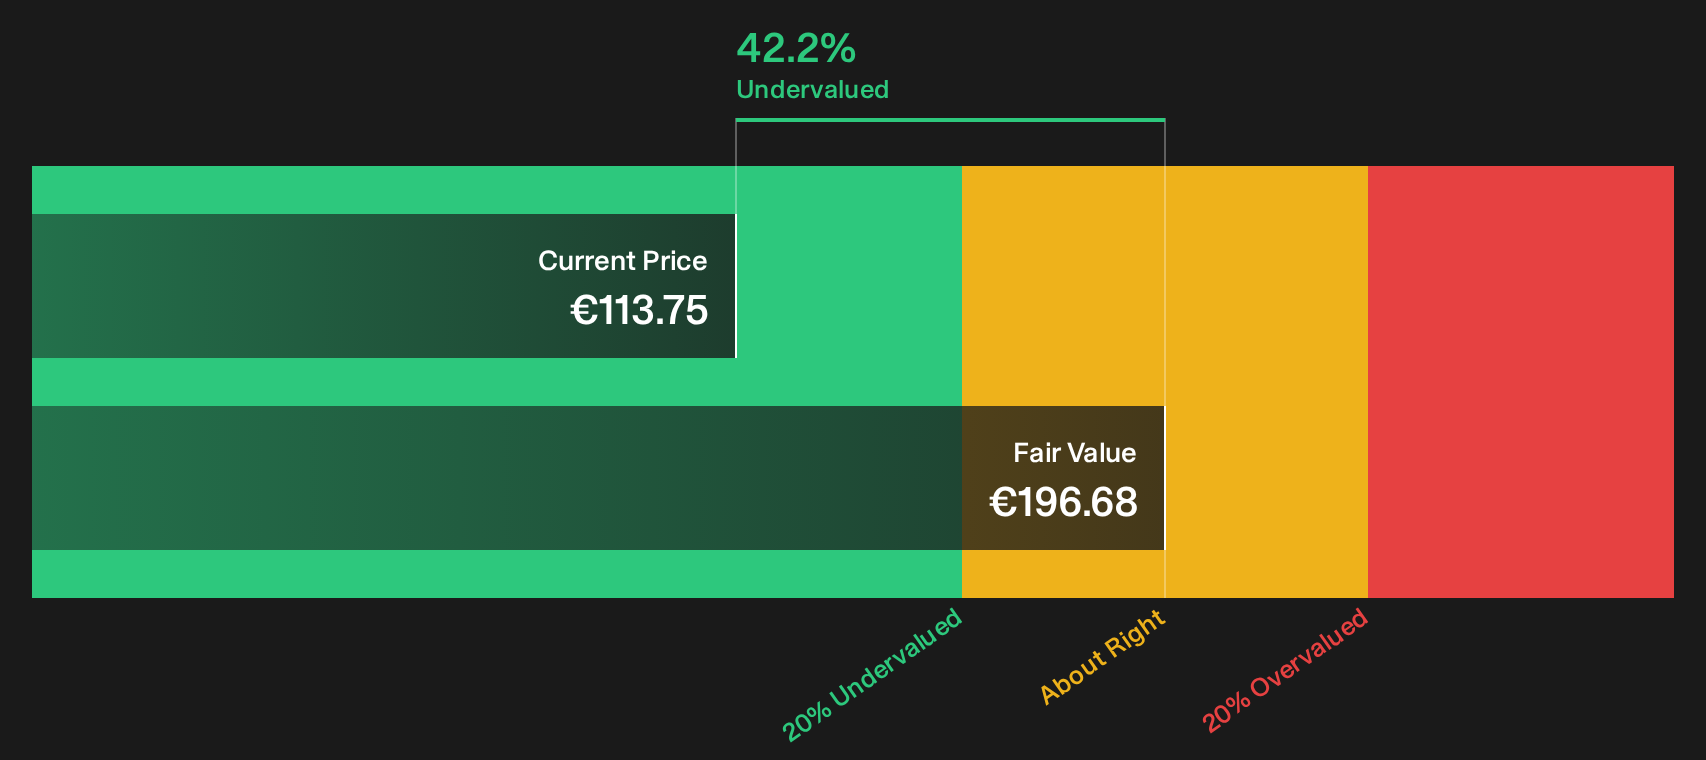
If KBC’s equity beta normalizes toward 1.0 (pushing Cost of Equity to ~8.15%), both model outputs drop significantly below the bottom of their sensitivity ranges.
This raises the question of what happens to that euro cash franchise if a single assumption about how investors price its risk profile quietly shifts again.
If that risk reset is what you care about, the full narrative for KBC Group shows where KBC Group’s euro cash engine could be accelerating, stalled or quietly decoupling.
Seeking Fresh Alternatives Beyond Cash?
Fresh opportunities can move from quiet to flying once momentum builds. Spot potential breakouts under the radar for now and consider positioning before the crowd reacts.
- Target income streams by scanning the 226 dividend fortresses that concentrate higher yielding payers while they are still priced for hesitation rather than certainty.
- Look for potential mispriced quality using the 192 high quality undervalued stocks where balance sheets, cash flows and valuation align before momentum traders respond later.
- Track early trendsetters in automation with the 95 robotics and automation stocks and see which operators could benefit first if demand for productivity tools continues to develop.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com