


GrainCorp valuation questioned after cash flow focused DCF update
A fresh discounted cash flow review has put GrainCorp (ASX:GNC) under the microscope, with the model suggesting intrinsic value trails the current share price. That gap is pushing investors to reassess what future cash flows might justify.
Recent trading tells a mixed story. GrainCorp’s share price has gained 19.45% over the past 90 days; yet the year to date share price return is down 9.71%, while the 1 year total shareholder return has declined 20.09% despite a 38.94% gain over five years.
Compare GrainCorp’s valuation gap with a curated set of potential mispriced opportunities using our 4 high quality undervalued stocks filter, which is built around cash flow strength and balance sheet quality.
After a sharp 90 day rebound, yet a weaker year and a discounted cash flow value that sits below the share price, does GrainCorp reward buying now or waiting for a cleaner entry on the numbers?
Most Popular Narrative: 8% Undervalued
On the latest narrative workup, GrainCorp’s fair value sits at A$7.11 per share, a touch above the A$6.51 last close, which puts the discounted cash flow gap in sharper focus for anyone weighing the price today.
GrainCorp's record oilseed crush volumes and continued growth in Animal Nutrition volumes, including 1H26 sales of 390,000 tonnes and FY25 volumes that were 83% higher than FY21, point to ongoing expansion of processing and feed activities that can support future revenue and EBITDA.
See why 27 investors see GrainCorp as 8% undervalued.
Result: Fair Value of A$7.11 (UNDERVALUED)
Still, the GrainCorp narrative leans heavily on a rebound from weaker grain margins and on a recovery in Nutrition and Energy earnings that may not arrive on schedule.
Find out about the key risks to this GrainCorp narrative.
Another View: GrainCorp multiples tell a different story
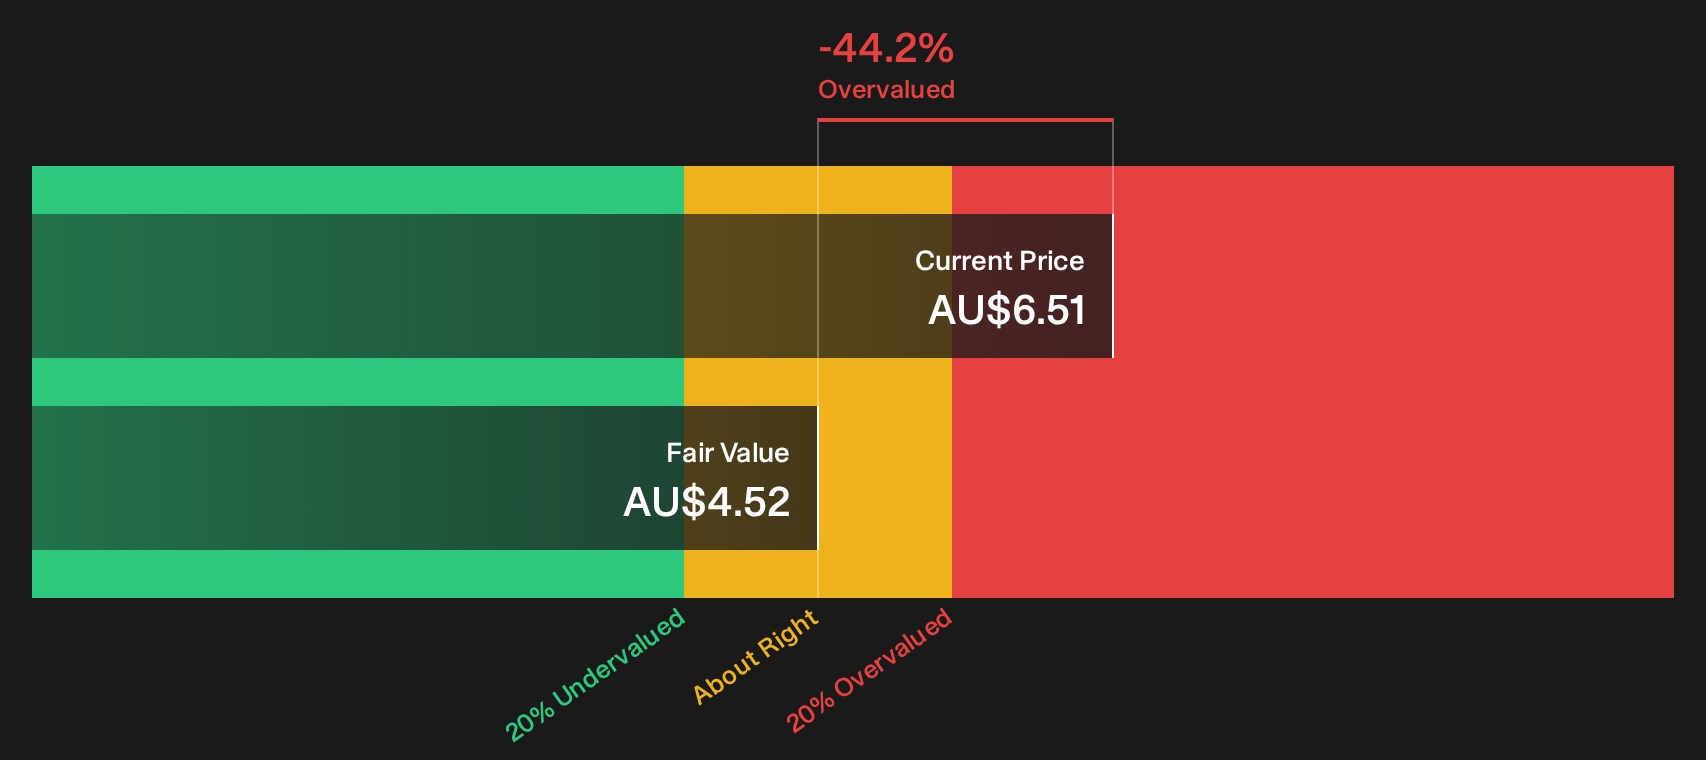
The SWS DCF model points to future cash flows that support a value of A$4.52 per GrainCorp share, which is below the A$6.51 market price and frames the stock as overvalued on that lens. That sits against analyst fair value of A$7.11, leaving you to weigh which assumptions feel more realistic.
Before leaning on either signal too heavily, it is worth seeing how the cash flow model is built and what needs to happen in practice for those inputs to hold up. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GrainCorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around GrainCorp’s value can be confusing, so move quickly to check the full data, weigh the risks and rewards, and decide where you stand using 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond GrainCorp?
If GrainCorp leaves you on the fence, widen your watchlist now. The right shortlist can turn a vague hunch into a clear decision.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (12 results) built to surface financially robust businesses.
- Hunt for quality trading below intrinsic value through the 4 high quality undervalued stocks and compare how those opportunities stack up against GrainCorp.
- Focus on cash returns to shareholders with the 6 dividend fortresses and see which payers currently combine income potential with underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com