


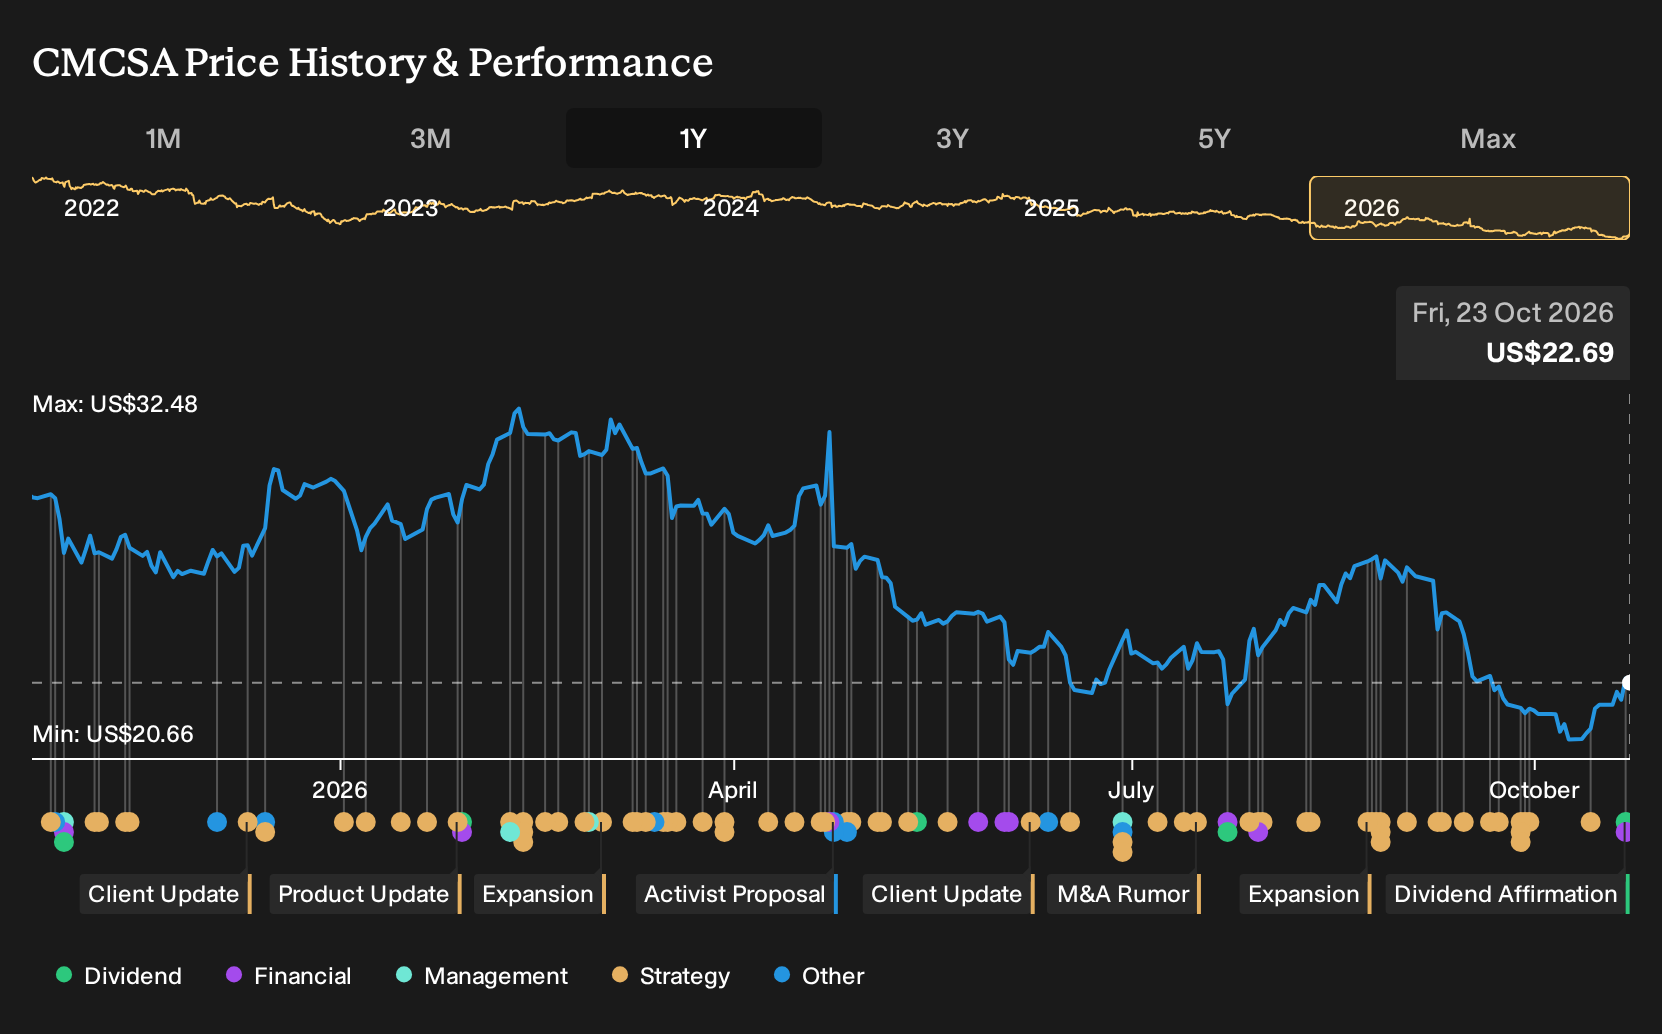
- Comcast reported third quarter 2026 results with sales of US$29.3b, net income of US$3.4b, and basic EPS from continuing operations of US$0.97, alongside affirmation of a US$0.33 quarterly dividend payable in January 2027.
- Operating updates showed Peacock posting a second consecutive profitable quarter, while management pushed ahead with a large cost transformation and the planned separation of NBCUniversal and Sky into an independent public company.
- The focus now turns to how Comcast's cost transformation and segment separation plan could reshape the broader investment narrative for the business.
Compare Comcast's restructuring, dividend, and broadband pressures with other communications players by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results)
What Is Comcast's Investment Narrative?
To stay in Comcast through this restructuring, you need to believe the core connectivity and media assets can earn solid returns on heavy capital and content spend while customer behavior keeps tilting toward wireless and streaming. The latest quarter showed that picture is mixed. Broadband lines are under pressure, yet Peacock is profitable again and wireless additions are strong. The affirmed US$0.33 dividend and reaffirmed NBCUniversal and Sky separation signal management is comfortable funding both payouts and a large cost program, even as margins sit well below last year and debt remains meaningful.
In the short term, the main swing factors are execution on the cost transformation, broadband retention against fiber and satellite rivals, and cleanly executing the media spin by mid 2027 without value leakage. The Q4 charge of more than US$1b makes the restructuring tangible rather than theoretical. Expansion into underserved markets like Hardee County shows Comcast still investing in the network where it sees opportunity, even while guidance points to subdued revenue trends over the next few years. For shareholders, the question is whether that combination of value, dividend income, and break up potential outweighs softer profit growth and lower recent share returns.
Yet there is one uncomfortable piece of the Comcast story that still hangs over all of this restructuring optimism.
There's only one way to know the right time to buy, sell or hold Comcast. Head to Simply Wall St's company report for the latest analysis of Comcast's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Comcast’s rural broadband build as a potential upside swing factor. Before this quarter’s update, the bullish camp was modeling fairly flat revenue through 2029 and earnings rising from about US$11.2b to US$12.6b. You should expect those views to evolve as the dividend affirmation and broadband trends sink in.
Explore 5 other Comcast fair value estimates, including one that suggests as much as 342% upside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Comcast research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Comcast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comcast's overall financial health at a glance.
Looking For More Ideas Beyond Comcast?
If Comcast's restructuring story has you thinking about portfolio balance, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you filter by financial strength, income potential, and valuation style so you can quickly build a watchlist that matches your own approach rather than someone else's model.
- For investors hunting for mispriced quality, start with companies that combine stronger fundamentals with appealing valuations by scanning 27 high quality undervalued stocks.
- If resilience is your top priority, focus on businesses with sturdier finances and steadier risk profiles by reviewing a 30 resilient stocks with low risk scores.
- For those who care most about income, tilt your search toward companies offering higher yields and robust payout records using a screener of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com