


DuPont de Nemours (DD) just added AmberChrom SIL silica gel to its bioprocessing lineup, targeting purification for peptide drugs like GLP-1 therapies. This gives investors fresh context for the stock’s role in healthcare-focused materials.
Recent price action suggests investors are warming to DuPont de Nemours again, with a 1-day share price return of 1.07% and a 7-day gain of 4.68% pushing the stock to US$136.55. A 36.70% 1-year total shareholder return points to momentum that has been building over a longer stretch.
Scan beyond DuPont de Nemours and explore other materials and industrial stocks with higher quality fundamentals using the list of solid balance sheet and fundamentals (25 results), which might merit a closer look.
After a 36.70% 1-year total return and fresh interest around DuPont de Nemours in healthcare materials, the real tension now is simple: pay up at today’s price, or wait and hope the valuation comes back to you.
Most Popular Narrative: 18% Undervalued
On the most followed narrative, DuPont de Nemours screens as undervalued, with a fair value of $166.41 compared with the latest $136.55 close. This puts a spotlight on what has to go right operationally to close that gap.
Ongoing productivity programs that target 3% net productivity of COGS each year, coupled with already delivered COGS reductions and efforts to push cost of poor quality below the current 4% of sales, create room for further operating EBITDA margin expansion and earnings growth if execution continues.
See why 32 investors see DuPont de Nemours as 18% undervalued.
Result: Fair Value of $166.41 (UNDERVALUED)
Still, two things could upset the DuPont de Nemours story quickly: PFAS related legal costs and Water segment projects that stay slower for longer than analysts expect.
Find out about the key risks to this DuPont de Nemours narrative.
Another View: What The P/E Ratio Says About DuPont de Nemours
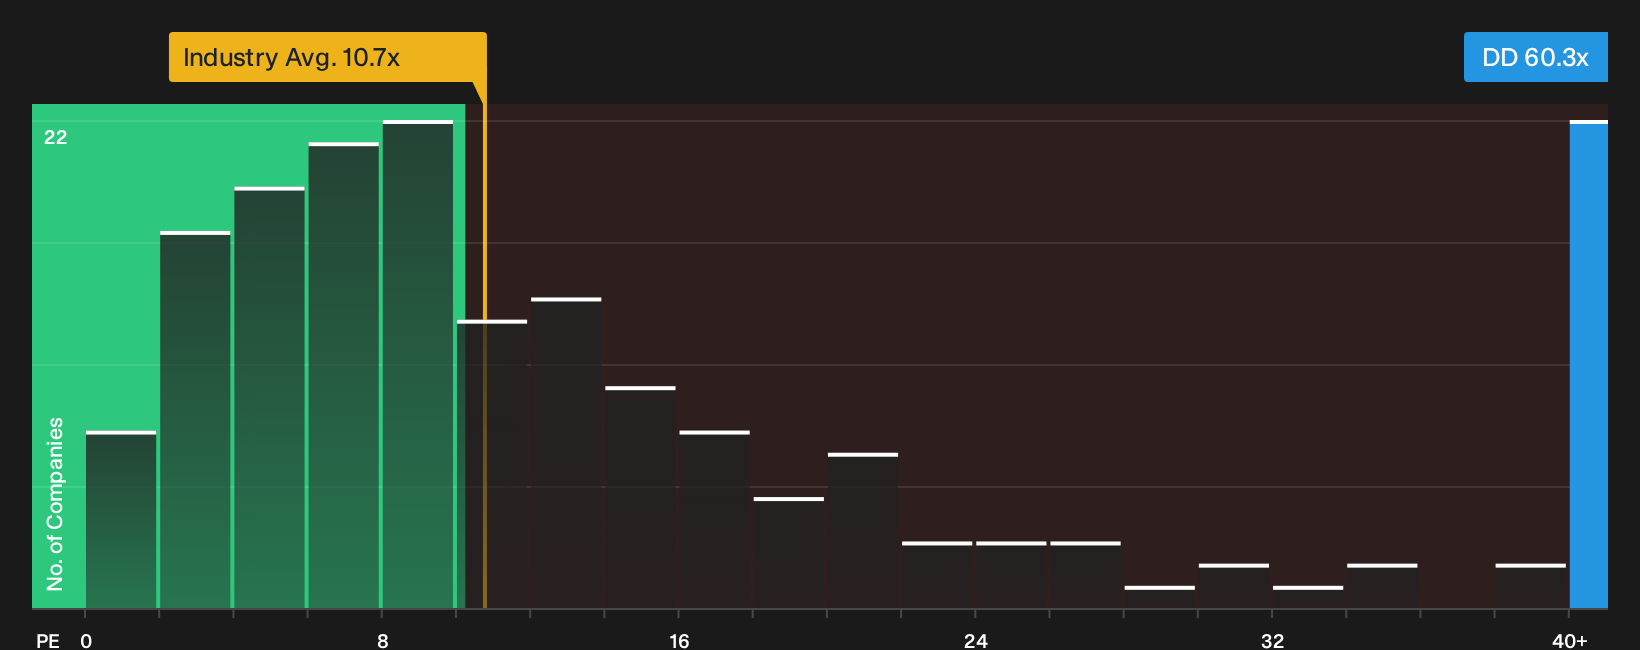
On a P/E basis, DuPont de Nemours looks expensive. The current multiple of 60.3x sits well above the Industrials industry average of 10.7x and the 27.3x peer average, and it also towers over the 34.9x fair ratio that the market could eventually lean toward. If sentiment cools, how quickly could a re rating toward that fair ratio affect returns?
To pressure test this against the first valuation view, it helps to step through the numbers driving this richer multiple story in our breakdown, then decide how much valuation risk you are comfortable holding at today’s price. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages on DuPont de Nemours leave you unsure, move quickly to review the underlying data yourself and pressure test the narrative from both angles. To weigh the push and pull of its upside potential against the issues investors worry about, start with the 4 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond DuPont de Nemours?
You have a clearer view on DuPont de Nemours. Now broaden your opportunity set and pressure test your thinking across other businesses before making your next move.
- Target durable balance sheets and steadier fundamentals by scanning a 30 resilient stocks with low risk scores that can help you sidestep the most fragile companies.
- Hunt for value where quality and price intersect by focusing on a 27 high quality undervalued stocks that may sit closer to your preferred margin of safety.
- Stack potential income ideas on your watchlist by filtering for a 5 dividend fortresses that screens for yield with backing fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com