


Encompass Health (EHC) has drawn fresh attention after two related updates. The group opened a new inpatient rehabilitation hospital in San Antonio and reaffirmed a regular quarterly cash dividend for shareholders.
These updates land after a solid run for Encompass Health’s shares, with the 90-day share price return of 9.92% and year-to-date share price return of 16.66% pointing to building momentum. The 3-year total shareholder return of 108.35% and 5-year total shareholder return of 157.76% underline how patient investors have been rewarded over time.
Spot opportunities around Encompass Health's expansion story by scanning a curated group of hospital and healthcare operators with resilient fundamentals through our list of solid balance sheet and fundamentals (25 results).Encompass Health now appears to be a high quality operator, with fresh capacity coming online and a recurring dividend on top. The real question is whether the current US$124 share price already fully reflects that profile.
Most Popular Narrative: 16% Undervalued
The most followed view on Encompass Health pitches a fair value of about $148 per share using a 7.2% discount rate, compared with the recent $124.09 close. The narrative frames the current price as not fully reflecting the longer term expansion and earnings profile.
Ongoing expansion of Encompass Health’s inpatient rehabilitation footprint through de novo hospitals, bed additions at high occupancy sites, and small format facilities, supported by a disclosed multi year pipeline and high returns on these projects, points to further discharge volume growth that can lift net operating revenue and EBITDA.
See why 6 investors see Encompass Health as 16% undervalued.
Result: Fair Value of $148.17 (UNDERVALUED)
Still, the Encompass Health story can be knocked off course if tougher Medicare Advantage authorization trends persist or if new hospitals and added beds ramp more slowly than modeled.
Find out about the key risks to this Encompass Health narrative.
Another View: What Encompass Health's P/E Is Telling You
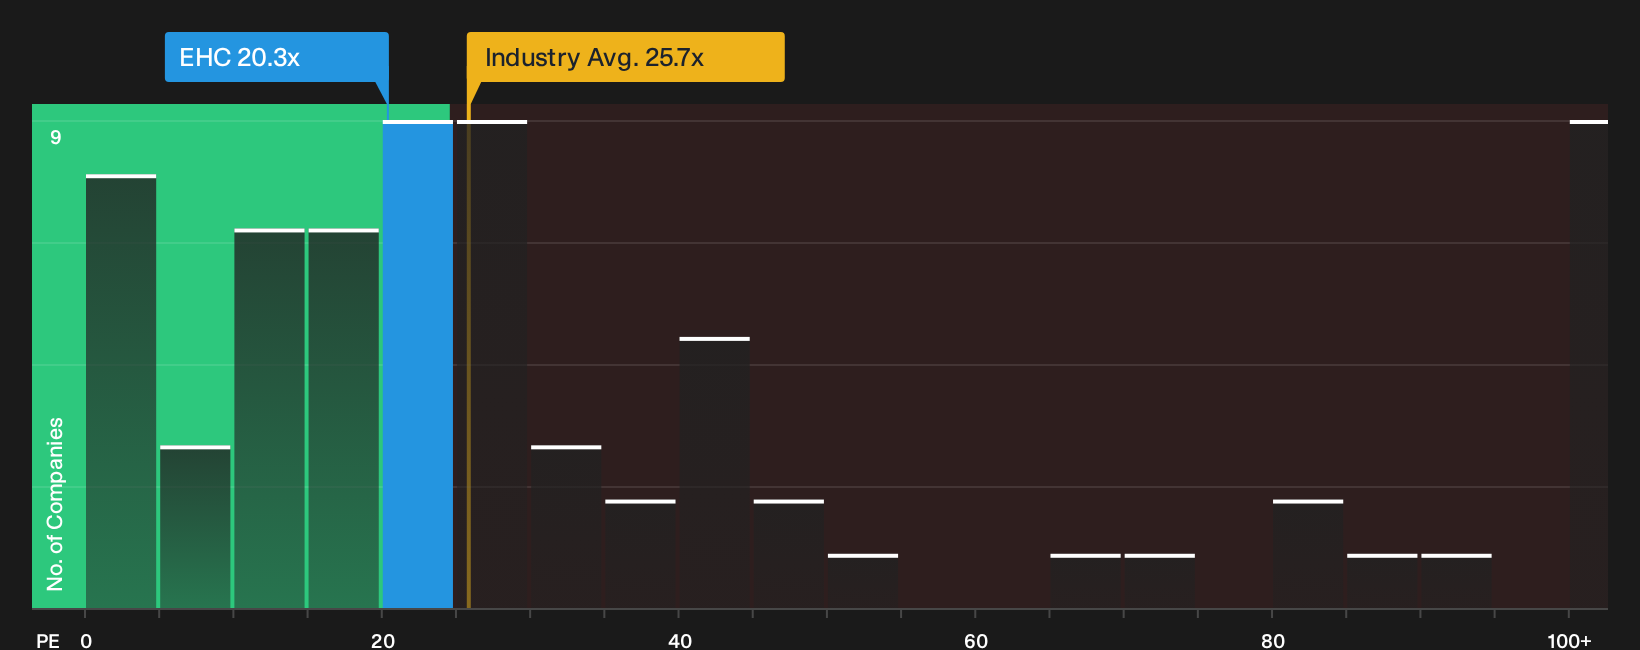
The narrative around Encompass Health leans on future cash flows and analyst targets. The plain P/E picture looks different. At 20.3x earnings, the stock trades above peers at 17.9x, yet below the broader US Healthcare group at 26.1x and under its own 25x fair ratio. That mix suggests valuation risk if expectations soften, and it also leaves room for the market to re rate upward if the current thesis remains in place.
To explore how those P/E differences could change over time and what that might imply for potential upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far, right, with Encompass Health carrying both clear strengths and some pointed concerns that investors keep circling back to. If you want to move quickly and shape your own view using the same structured breakdown others are leaning on, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Encompass Health?
If Encompass Health has your attention, do not stop here. Broaden your watchlist with fresh ideas that share strong fundamentals, income potential, or lower risk.
- Target more resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that highlights companies with financial strength at the core of their story.
- Hunt for potential mispricing opportunities using a 27 high quality undervalued stocks that focuses on quality businesses trading below their assessed worth.
- Build a steadier income stream by reviewing a 5 dividend fortresses that concentrates on higher yielding companies with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com