


Recent commentary around Kingboard Laminates Holdings (SEHK:1888) centres on analyst optimism tied to demand for PCB materials in electronics, which is expected to support profits, margins, and the company’s already healthy balance sheet.
At a latest share price of HK$37.7, Kingboard Laminates Holdings has given investors a 1-year total shareholder return of 196.00%. The year-to-date share price return of 180.51% points to strong momentum, despite a sharp 30-day share price decline of 26.87% that may reflect shifting views on near-term earnings risk versus longer-term demand for PCB materials.
Compare Kingboard Laminates Holdings with other PCB and electronics suppliers riding similar demand trends by scanning our curated list of 55 AI infrastructure stocks.
After a near tripling over 12 months followed by a sharp pullback, Kingboard Laminates Holdings now sits at a crossroads. Does the recent slide finally tilt the risk reward in buyers’ favour, or is it still too early to tell?
Preferred P/E of 27x: Is it justified?
On valuation, Kingboard Laminates Holdings is trading on a P/E of 27x, which prices the latest HK$37.7 share level well above both its fair P/E estimate and sector yardsticks.
The P/E ratio compares the current share price to earnings per share. For a laminates and electronic materials supplier like Kingboard Laminates Holdings, this measure effectively captures how much investors are willing to pay for each unit of profit in a sector where earnings can swing with end demand and input costs.
Based on the data, 1888 is considered expensive on a P/E of 27x compared with the estimated fair P/E of 25.7x. That suggests the market is attaching a richer valuation multiple than the level the fair ratio model points to. This gap could narrow if sentiment or earnings expectations shift.
Against peers, the contrast is even sharper. The same 27x P/E is described as expensive versus the peer average of 15.2x and also expensive relative to the wider Hong Kong Electronic industry on 13.3x. This implies investors are paying a substantial premium for this stock compared with sector alternatives.
Explore the SWS fair ratio for Kingboard Laminates Holdings.
Result: Price-to-earnings of 27x (OVERVALUED)
Still, the narrative around Kingboard Laminates Holdings can crack quickly if PCB demand softens, or if higher input costs pressure its current profitability profile.
Find out about the key risks to this Kingboard Laminates Holdings narrative.
Another view on Kingboard Laminates Holdings valuation
The P/E discussion presents Kingboard Laminates Holdings as expensive, yet the SWS DCF model points in the opposite direction. At HK$37.7, the stock is assessed as trading about 48.3% below an estimated future cash flow value of HK$72.98. That indicates a potential mismatch between market mood and cash flow maths.
Look into how the SWS DCF model arrives at its fair value.
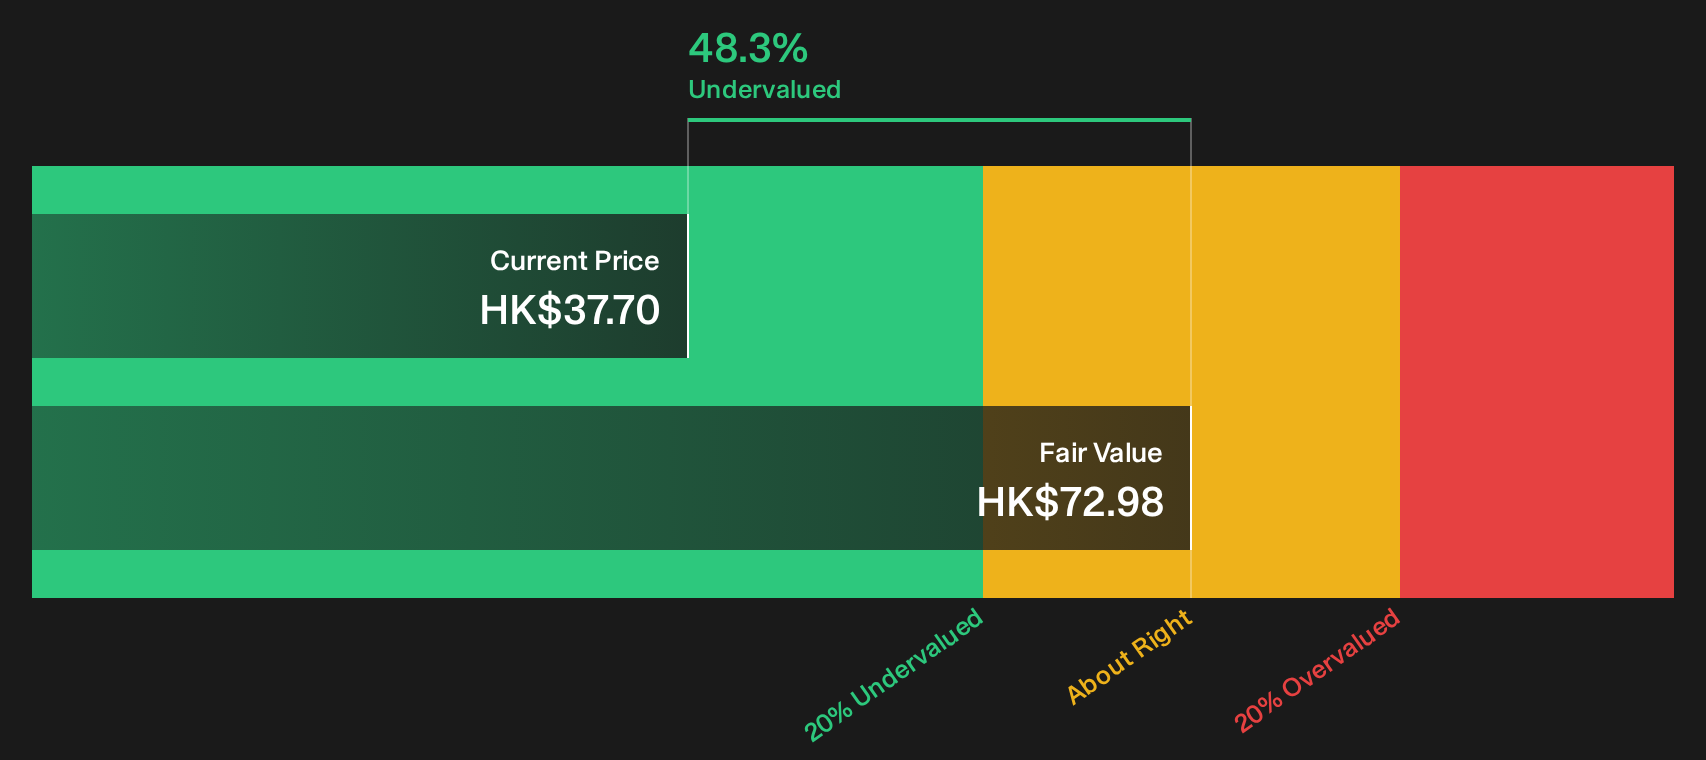
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kingboard Laminates Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of premium valuation and conflicting signals around Kingboard Laminates Holdings feels finely balanced, consider reviewing the numbers quickly in the context of your own risk tolerance and time horizon. Then weigh both sides of the story by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kingboard Laminates Holdings?
If Kingboard Laminates Holdings has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with other opportunities filtered by clear fundamentals.
- Target potential mispricings by scanning a curated 192 high quality undervalued stocks that filters for companies combining quality fundamentals with discounted valuations.
- Build a steadier income stream by reviewing a focused 226 dividend fortresses that prioritises higher yields alongside fundamental strength.
- Protect your downside by zeroing in on a 221 resilient stocks with low risk scores that is designed to highlight businesses with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com