


Doximity (DOCS) just tied its fast growing Ask AI assistant directly into Wolters Kluwer Health’s UpToDate content, giving clinicians embedded access to 13,000 evidence based topics inside the existing decision support workflow.
These product moves arrive while Doximity’s share price tells a mixed story for investors, with a 90 day share price return of 63.5% and a 30 day gain of 25.7% pointing to building momentum, even as the year to date share price return is down 22.9% and the 1 year total shareholder return has declined 50.0%.
Spot fresh healthcare AI momentum beyond Doximity by scanning a curated group of 34 healthcare AI stocks that are already building real clinician workflows around machine learning tools and data platforms.Doximity’s AI deals have driven a sharp rebound in the share price, although the 1-year return remains significantly negative. Is this recovery the beginning of a rerating, or is the stock already trading close to fair value?
Most Popular Narrative: 90% Undervalued
Doximity last closed at $33.39, while the most followed narrative on Simply Wall St anchors fair value at $33.70. That tiny gap on price hides a much bigger story about how the community views the platform’s earnings power and cash generation.
What I like about Doximity is that there really is a very high viewership / user base of active practicing Physicians in the US and that is not invaluable and definitely could be monetized perhaps more efficiently. I also think that Doximity offers a lot of interesting tools for Physicians a lot of which you’re free and really marketed towards I think Physicians who are more in private practice. It’s a little bit unclear how much value that provides given that most Physicians and practitioners these days are employed and not a private practice.
See why 10 investors see Doximity as 1% undervalued.
According to Dc12, a practicing tech focused physician, the draw is not just the AI tools but the concentration of actively practicing doctors on Doximity’s network. That narrative ties the valuation back to engagement, monetisation potential across its $655.6m healthcare software revenue base, and a long track record of earnings expansion, with profits growing 20.6% per year over the past five years.
This viewpoint also sits alongside Simply Wall St’s own cash flow work. The SWS DCF model currently points to a future cash flow value of $35.27 per share, compared with the $33.39 trading price, which indicates the stock is priced about 5.3% below that intrinsic estimate.
Result: Fair Value of $33.70 (UNDERVALUED)
Still, this Doximity optimism runs into two obvious pressure points: tougher competition around AI tools and the risk that private practice focused products have a capped audience.
Find out about the key risks to this Doximity narrative.
Another View: What Doximity’s P/E Is Telling You
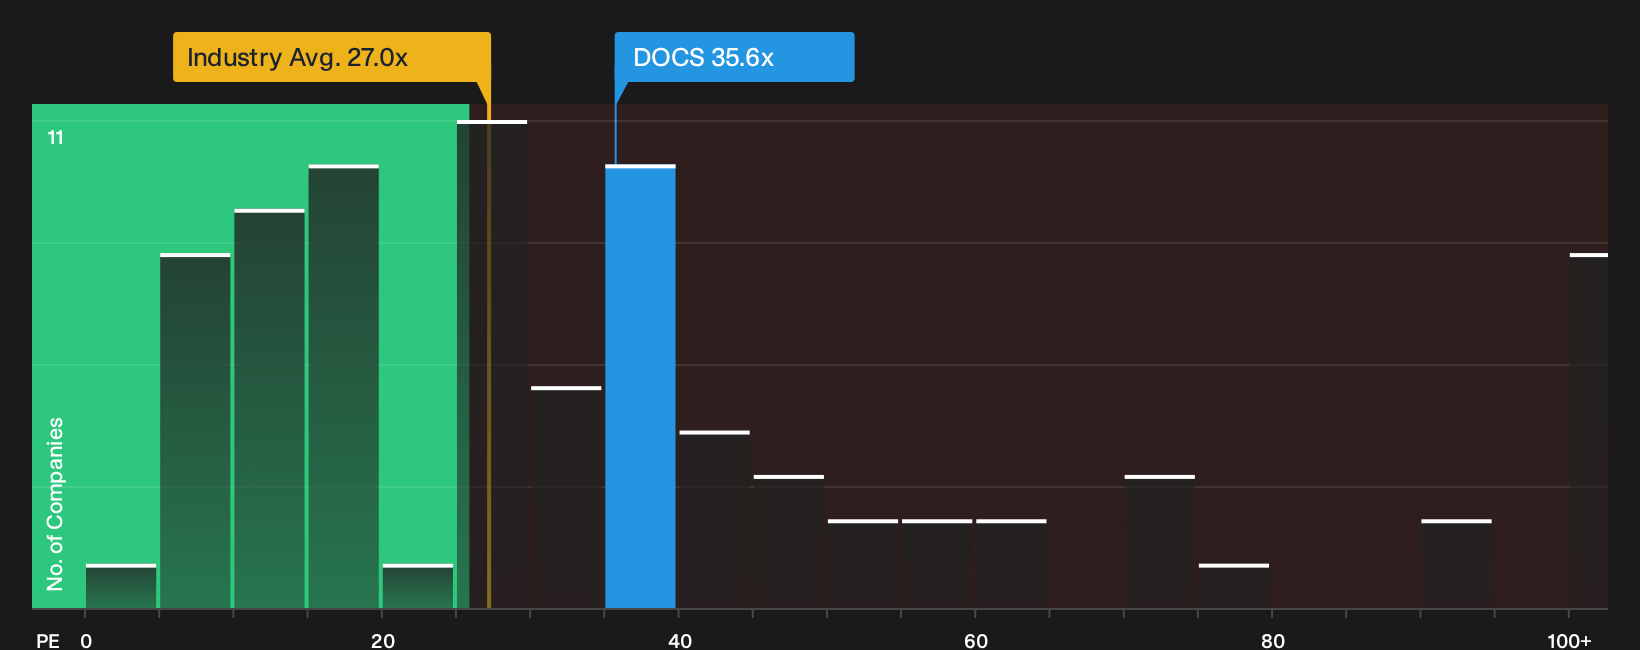
Doximity trades on a P/E of 35.6x, which is higher than the global Healthcare Services industry at 27.9x and above its own fair ratio of 27.4x. That premium suggests investors are already paying up, so the risk is that any stumble in execution hits the multiple first.
Against closer peers, though, Doximity’s 35.6x looks cheaper than the 60.4x peer average. That comparison leaves some room if the market leans toward that group rather than the fair ratio benchmark. Which crowd do you think will set the tone for this stock over the next few years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Doximity’s valuation and AI push makes this a good moment to review the underlying numbers yourself and decide where you stand. To weigh both the concerns and the upside potential, start with the 2 key rewards and 2 important warning signs.
Looking for more Doximity sized ideas?
If Doximity has sharpened your focus on healthcare and valuations, do not stop here. Broaden your watchlist now or you risk missing the next opportunity.
- Target value with quality by scanning a curated set of 27 high quality undervalued stocks that pair stronger fundamentals with price tags that may not fully reflect them.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with sturdier finances when conditions get choppy.
- Hunt for overlooked potential by checking a group of 21 high quality undiscovered gems that combine robust metrics with far less attention from the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com