


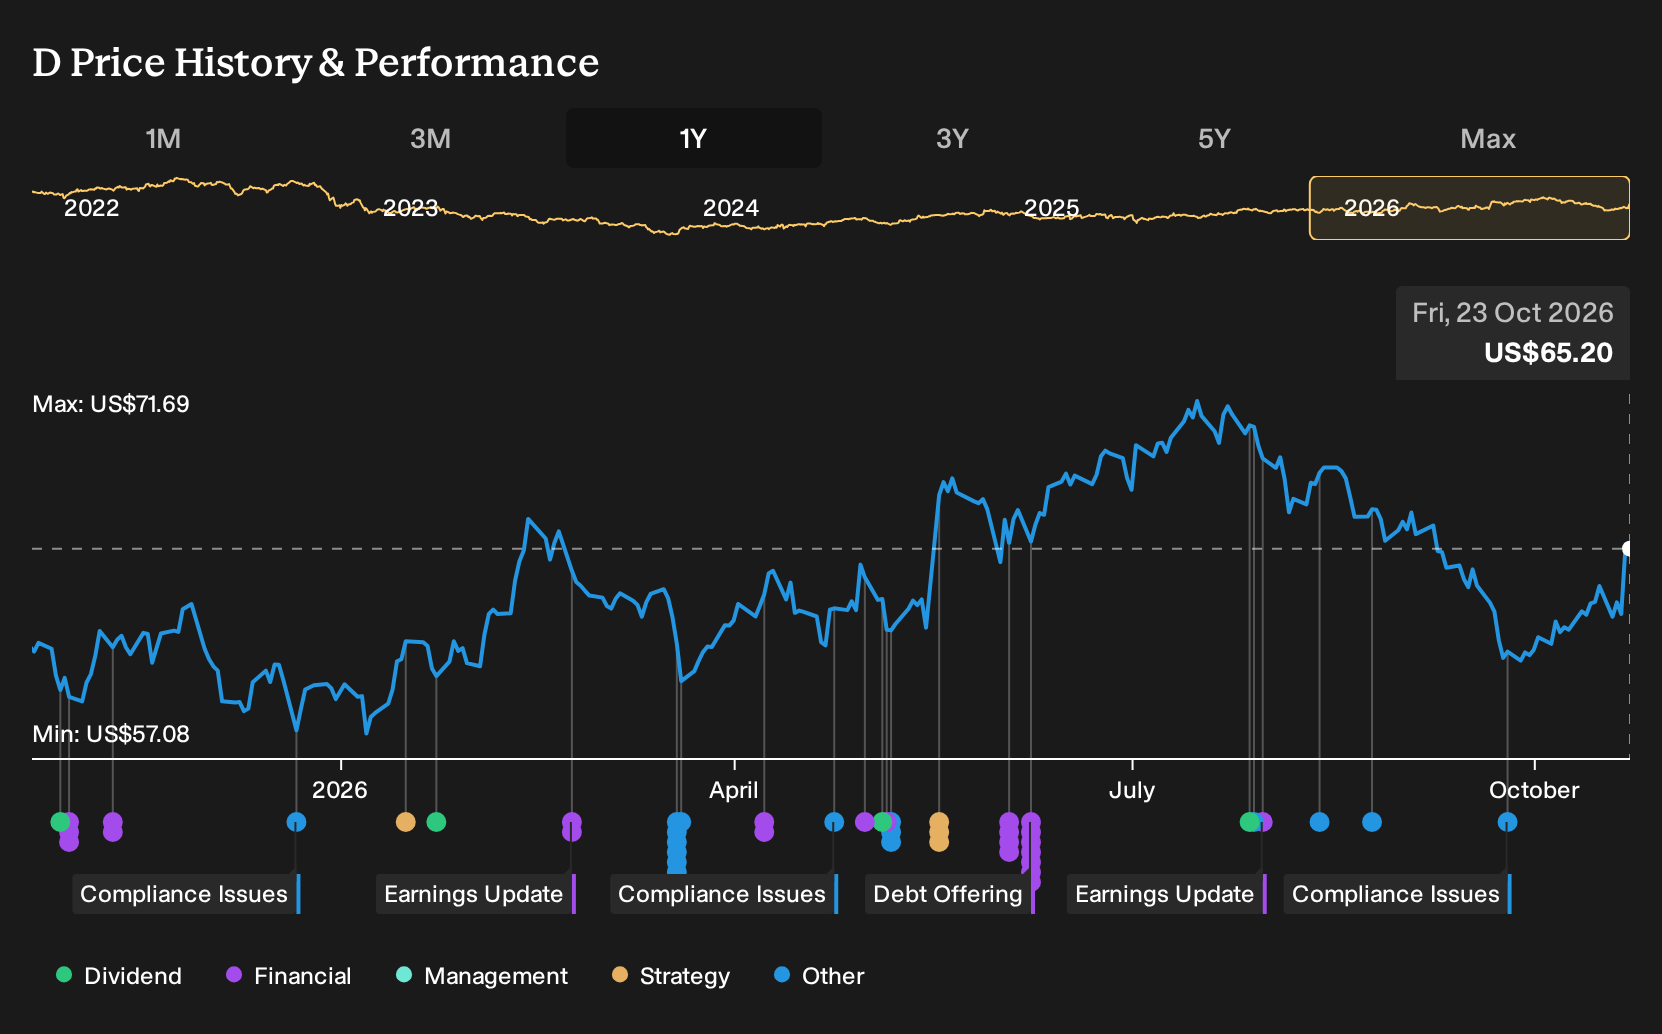
- Dominion Energy recently faced two regulatory setbacks in Virginia, including a rejected merger with NextEra Energy and a denied permit for its Vint Hill substation, even as the utility prepares to report its next quarterly results.
- The clash between Dominion Energy's grid reliability projects and state level consumer protections highlights how regulatory decisions could shape future capital spending and allowed returns.
- Next, the focus shifts to how Dominion Energy's investment narrative absorbs this mix of earnings optimism and legal pushback on the Vint Hill project.
Dominion Energy Investment Narrative Recap
To own Dominion Energy, you need to believe that regulated grid and generation investment in Virginia and the Carolinas will keep moving forward despite tougher scrutiny. The short term swing factor is how quickly the utility can convert surging large load demand and its US$65b capital plan into assets in rate base without major regulatory friction.
The biggest risk right now sits around project execution and approvals. The Vint Hill setback and the rejected NextEra merger both point to a more assertive stance on consumer protections and bill impacts. If that shift spreads to offshore wind, data center infrastructure or new gas plants, the timing and economics of Dominion Energy capital spending could be less favorable.
The Vint Hill lawsuit is the announcement that feels most relevant. Dominion Energy is effectively arguing that grid reliability constraints linked to data center growth need urgent physical solutions. That goes straight to the core thesis that long dated, regulated infrastructure can underpin earnings as new projects are completed and added to rate base.
For you, the key question is whether local resistance to transmission projects meaningfully slows that build out. Dominion already faces large committed projects such as Coastal Virginia Offshore Wind and new gas capacity at Canadys Station and Mount Storm. Any pattern of delays or cost disallowances would add to existing pressure points around dividend coverage and interest expense.
Dominion Energy's current analyst narrative points to revenues of US$21.1b and earnings of US$4.0b by 2029, based on 5.2% yearly revenue growth and an earnings increase of about US$1.5b from US$2.5b today.
Uncover why Dominion Energy's fair value indicates a 10% potential upside to its current price before the discount gap closes.
Exploring Other Perspectives
The two fair value views from the Simply Wall St Community span roughly US$72 to US$175 per share, which shows how far private investors can spread on Dominion Energy. Those assessments pre date the Vint Hill lawsuit and merger rejection; you should weigh them against fresh regulatory risk and earnings sentiment before forming your own view.
Explore another Dominion Energy fair value estimate, including one that suggests it could be worth just $71.64.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Dominion Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dominion Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dominion Energy's overall financial health at a glance.
Looking for more investment ideas beyond Dominion Energy?
If you want to stress test your view on Dominion Energy and see how it stacks up against other opportunities, the Simply Wall St Screener can help you quickly filter for businesses that better match your risk tolerance, dividend needs, or value focus.
- Target resilience first by focusing on balance sheet strength and fundamental quality with this curated list of solid balance sheet and fundamentals (25 results) that may better match a conservative approach.
- Prioritize stability and income by scanning a focused group of higher yielding 5 dividend fortresses that aim to combine ongoing payouts with business robustness.
- Hunt for overlooked quality by running through a carefully filtered set of 21 high quality undiscovered gems that many investors may not yet be watching closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com