


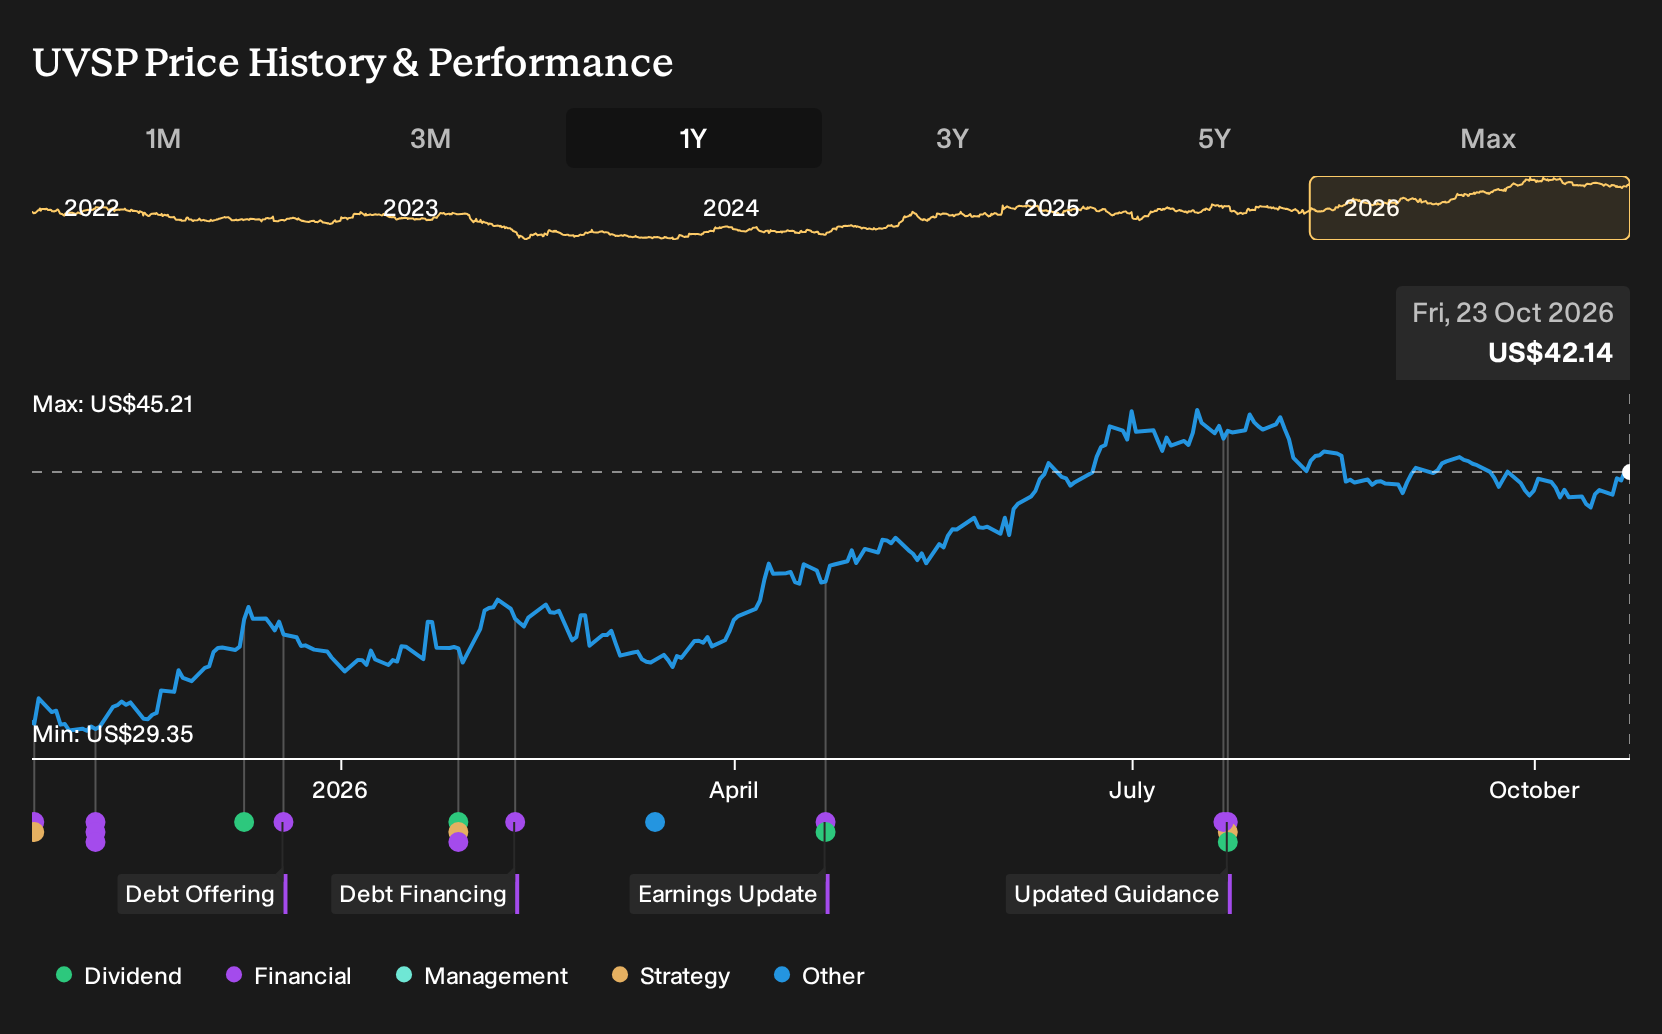
- Univest Financial recently highlighted a 2.2% dividend yield and an annualized dividend that is 5.7% higher than a year ago, alongside consensus expectations for stronger earnings in the coming fiscal year.
- The combination of an above-industry dividend yield and anticipated earnings growth suggests that Univest Financial is leaning on income and profitability to attract capital in a competitive regional banking market.
- The focus now turns to how this richer dividend profile might reshape Univest Financial's broader investment narrative around earnings quality.
Compare Univest Financial's income profile with a handpicked 5 dividend fortresses that also focus on yield and fundamentals to attract long-term capital.
Univest Financial Investment Narrative Recap
To own Univest Financial, you need to be comfortable with a regional bank that leans on disciplined lending, deposit gathering, and fee income rather than rapid expansion. The key short term swing factor is how net interest income holds up as competition for quality commercial and construction loans and deposits stays intense. The latest dividend increase and current 2.2% yield signal confidence, but they do not materially change that core operational story.
The biggest risk remains pressure on credit quality and funding costs. Event driven issues in commercial real estate or larger commercial borrowers could push credit provisions above prior guidance and hit returns. If deposit initiatives lose steam while rivals keep bidding up rates on money market and certificate of deposit balances, profitability could feel that squeeze even with healthier loan yields.
The most relevant recent move tied to this dividend story is the 4.5% increase to a US$0.23 per share payout, with a payout ratio near 26%. That sits alongside a dividend yield modestly above the industry and an annualized dividend that is 5.7% higher than a year ago. For you, the signal is about how management balances income return with capital retention.
Framed against the catalysts, that higher dividend works alongside ongoing digital investment, fee based wealth and insurance revenue, and a tilt toward higher margin commercial and construction lending. The combination could support earnings quality if credit costs stay contained and deposit growth keeps pace with loan demand. The risk is that any uptick in provisions or stubbornly high funding costs would make that richer dividend profile harder to maintain without trade offs elsewhere in the business.
Univest Financial's analyst narrative points to US$394.9 million in revenue and US$109.2 million in earnings by 2029, based on an assumed 6.2% yearly revenue growth rate and an earnings increase of US$10.8 million from US$98.4 million today.
Uncover why Univest Financial's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Univest Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Univest Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Univest Financial's overall financial health at a glance.
Looking for more ideas beyond Univest Financial?
If you want to stress test your thesis on Univest Financial, it can help to compare it with other companies that share similar income, risk, or balance sheet traits using the Simply Wall St Screener.
- If capital protection ranks high for you, start with a group of companies screened for resilience by checking out the 30 resilient stocks with low risk scores.
- For investors who care most about financial strength, compare Univest Financial with a list of solid balance sheet and fundamentals (25 results) to see which businesses pair sturdier balance sheets with consistent fundamentals.
- If you are hunting for under-appreciated ideas, broaden your watchlist with a 21 high quality undiscovered gems that couple quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com