


- TriNet Group has rolled out new and enhanced platform capabilities for small and mid sized businesses, including TriNet Leave powered by Cocoon, TriNet Recruit powered by JazzHR, TriNet Spend, and expanded AI assistance across HR workflows.
- The expansion of AI powered tools, from voice enabled mobile support to embedded analytics in Reports and Analytics, points to a push to cut manual HR workload while keeping compliance and workforce data in a single system.
- This article examines how TriNet Group's broader AI infused HR platform, including TriNet Leave, could affect the existing investment narrative.
Scan how TriNet Group’s AI heavy HR rollout compares with other workflow focused platforms by zeroing in on 55 AI infrastructure stocks that are shaking up back office operations.
TriNet Group Investment Narrative Recap
For TriNet Group, the core belief is that more complex HR and compliance work keeps pushing small and mid sized businesses toward outsourced platforms, and that TriNet can turn that need into stable, recurring service revenue. The short term swing factor is whether the firm can stabilize worksite employee volumes after recent 12% declines, since softer client headcount has already lined up with 5% revenue drops.
The biggest current risk is that higher health cost trends and added spending on AI tools, ASCEND and broker channels weigh on margins without clear volume support. The new AI centric release helps the execution story on efficiency and product breadth, but on its own it does not remove the exposure to client workforce softness or medical inflation.
TriNet Leave, powered by Cocoon, looks most relevant for the near term thesis. Leave rules are getting trickier and many founders do not want to staff in house experts for intermittent requests. A more automated, guided experience inside the same HR system can deepen usage and make it harder for customers to switch away once their policies and workflows are embedded.
For catalysts, this rollout matters if it supports retention in the existing PEO base and nudges more clients into broader HR Plus or ASO style relationships. That would lean into the idea that technology and AI can offset higher health trends and investment spend by lifting attachment to the TriNet Group platform, even if headline worksite employee counts stay under pressure for a while.
TriNet Group's current analyst narrative points to US$5.2b in revenue and US$164.8m in earnings by 2029, based on an assumed 2.2% yearly top line expansion. That profile reflects earnings today of US$175.0m, implying an earnings decrease of US$10.2m by the 2029 forecast year.
Uncover why TriNet Group's fair value indicates a 13% potential downside to its current price, suggesting that the current premium may not be sustainable.
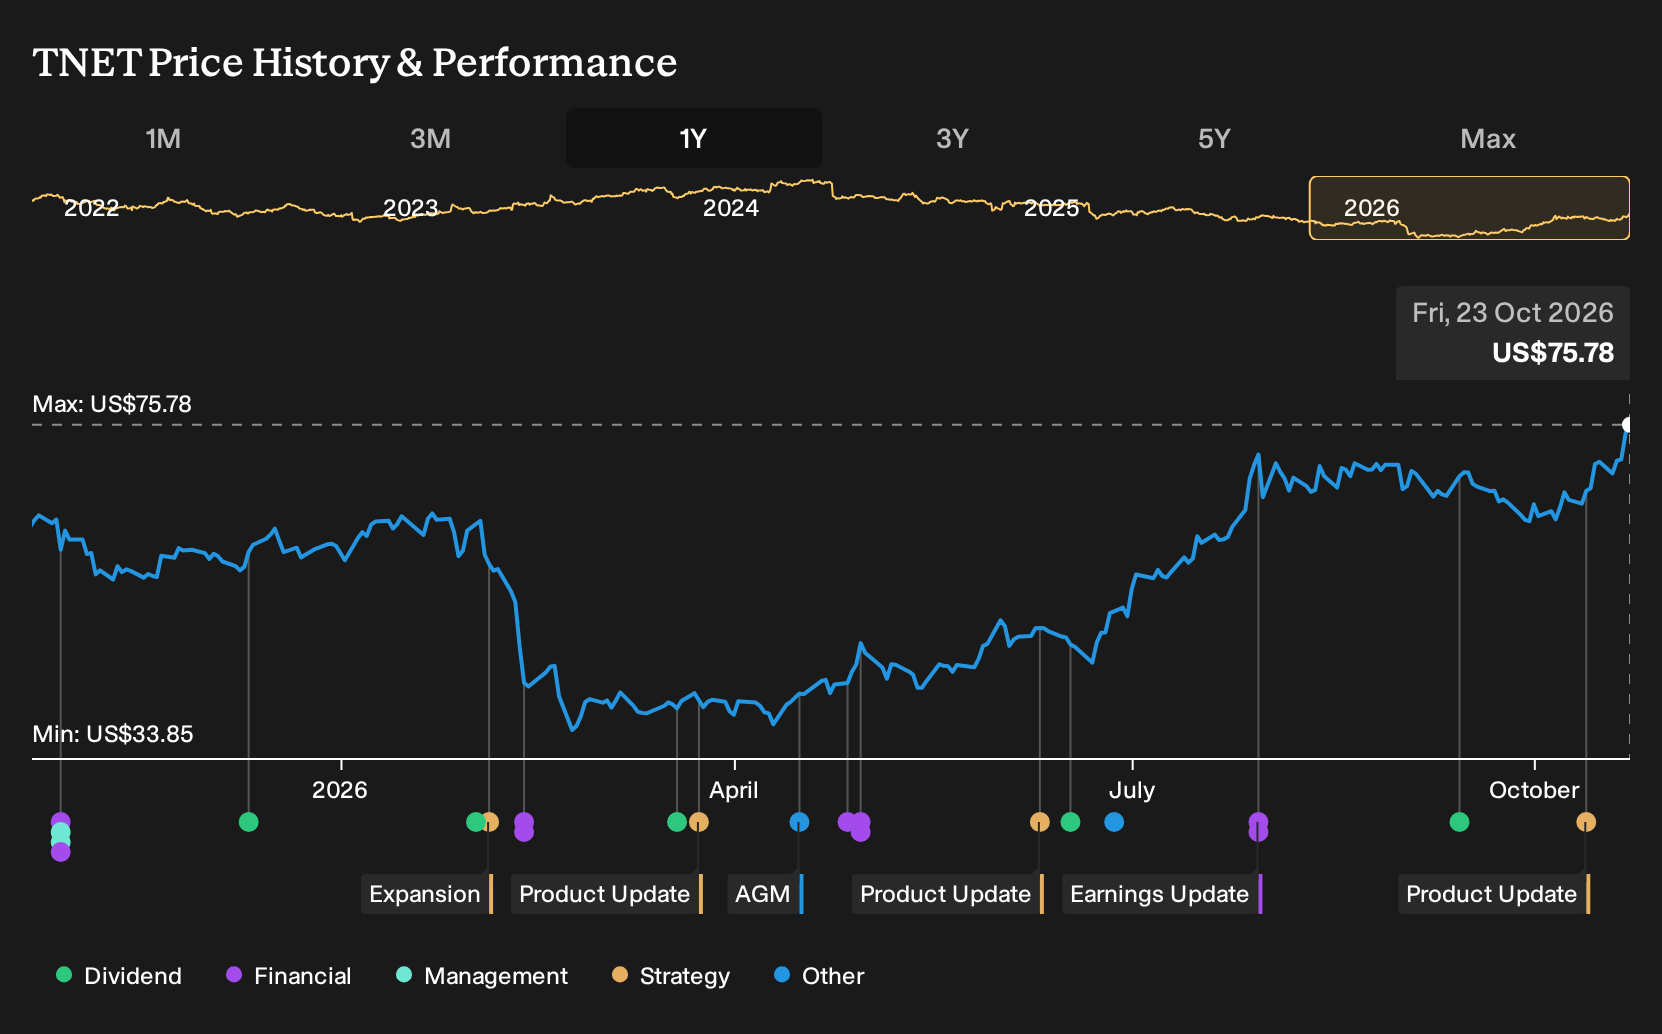
Exploring Other Perspectives
One alternate view focuses on interest income pressure rather than AI tools. The most bearish analysts already had TriNet Group drifting to US$158.1m in earnings on US$5.2b of revenue by 2029. That is a more constrained story than consensus. With this new AI-heavy release, those assumptions might shift, so consider both sets of expectations before deciding what seems reasonable to you.
Explore 3 other TriNet Group fair value estimates, including one that suggests as much as 34% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TriNet Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for TriNet Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriNet Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond TriNet Group?
If the TriNet Group story has sharpened your thinking, use that momentum to build a broader watchlist with the Simply Wall St Screener. You can filter for cash flow strength, balance sheet resilience, or income potential and then compare how those traits line up against what you see in TriNet Group.
- For readers who care most about valuation safety and quality fundamentals, start with a curated pool of 27 high quality undervalued stocks that already clear a high bar on both fronts.
- If capital preservation and smoother return profiles matter more to you than aggressive growth, focus on a carefully filtered group of 30 resilient stocks with low risk scores that score well on resilience.
- When you want to cast a wider net for fresh ideas without drifting into low quality territory, scan a focused universe of 21 high quality undiscovered gems that pair solid fundamentals with lower attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com