


CoreCivic (CXW) just cleared the bar on its latest earnings release, with revenue growth picking up enough to push the stock’s valuation above many sector peers and spotlight investor conviction.
Recent trading paints a mixed picture for CoreCivic. The share price has risen 57.94% year to date and delivered a 59.96% total shareholder return over the past year. However, the stock has eased in recent weeks, with a 30 day share price return of down 6.94% and a 90 day share price return of down 4.18%, suggesting some investors are reassessing how much premium they are willing to pay after the earnings driven rerating.
Spot fresh momentum and valuation stories around CoreCivic by scanning our hand picked 21 high quality undiscovered gems with strong fundamentals that the wider market may still be overlooking.Bulls see CoreCivic’s premium as proof that earnings quality and cash generation justify paying up. Bears point to stretched models instead. With the numbers now on the table, which story does the current valuation support?
Most Popular Narrative: 28% Undervalued
Against a last close of $30.04, the most followed CoreCivic narrative anchors on a fair value of $41.80, which implies a sizable valuation gap that rests on specific growth, margin and capital return assumptions rather than broad optimism.
The surge in ICE detainees housed at CoreCivic facilities, with populations up about 59.6% between early 2025 and mid 2026 and nationwide detention counts near historic highs, points to ongoing federal demand that can support higher occupancy and revenue as enforcement and funding cycles play through future periods.
The sale of four detention facilities to the government for about US$2.2b while retaining management contracts, together with continued ownership of 56 specialized properties, signals an ongoing shift toward recycling real estate value into cash while keeping operating income streams. This can support future earnings and net margin resilience.
See why 15 investors see CoreCivic as 28% undervalued.
Result: Fair Value of $41.80 (UNDERVALUED)
Still, the CoreCivic story leans heavily on ICE detention contracts and federal funding, so any policy shift or contract repricing could quickly undercut that upside case.
Find out about the key risks to this CoreCivic narrative.
Another View: CoreCivic Looks Expensive On Earnings
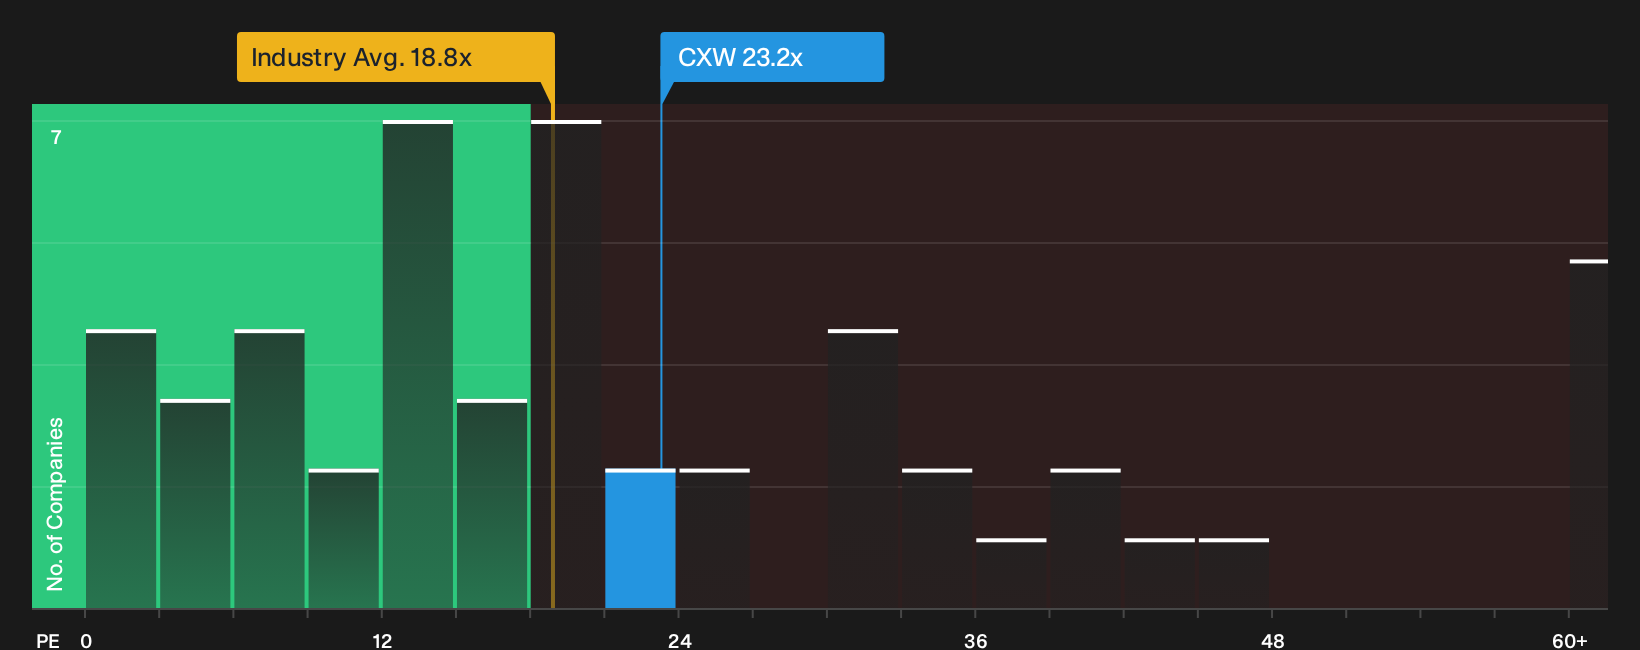
The DCF style narrative points to CoreCivic trading 28% below fair value. A simple P/E cross check tells a different story. The stock changes hands at 23.2x earnings, versus 19x for the US Commercial Services group and a fair ratio of 7.7x, which suggests valuation risk if sentiment cools.
To see how that earnings multiple stacks up against the wider market, and how much room there is for it to compress or expand, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Torn between CoreCivic’s upside story and the valuation worries running through this article? Move quickly, review the numbers yourself, and weigh both sides with the 2 key rewards and 3 important warning signs.
Looking for more CoreCivic style investment ideas?
Do not stop with CoreCivic. Broaden your watchlist now and give yourself more options when sentiment shifts, rather than reacting after prices move.
- Target potential mispricing by scanning a curated set of quality opportunities through the 27 high quality undervalued stocks that match stronger fundamentals with compressed valuations.
- Strengthen your downside protection by focusing on durability and balance sheet resilience using the 30 resilient stocks with low risk scores so sudden shocks do not catch you off guard.
- Get ahead of the crowd by checking the 7 elite penny stocks with strong financials for early stage ideas with healthier numbers than many investors assume at first glance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com