


JPMorgan Chase has rewarded long term shareholders with a powerful share price run, so the live question is whether the current valuation is still grounded in the returns the bank earns on its capital. Recent headlines around blockchain payments, national security financing, and risk management give you plenty of stories, but the investment case ultimately comes back to what those projects do for profitability on each dollar the institution reinvests.
- Over the past 3 years the stock has gained about 160.4%, which puts real pressure on investors to judge whether that kind of share price progress is matched by the returns the bank is generating on its capital base.
- The expansion of JPM Coin and tokenized liquidity products onto public blockchains like Ethereum and Solana may support higher fee income and more efficient use of balance sheet resources, which can matter a great deal for long run returns on equity and future reinvestment opportunities.
- Prefer to judge JPMorgan Chase on earnings? See why JPMorgan Chase's 13.6x P/E tells a different valuation story.
The issue now is whether those capital returns are strong and durable enough to make JPMorgan Chase's current share price look sensible on this lens.
If you want more ideas that link big projects to capital returns, a focused screen of 55 AI infrastructure stocks.
Is JPMorgan Chase a Bargain on Excess Returns?
The Excess Returns model looks at how much profit JPMorgan Chase earns on its equity above the return that shareholders require. On this view, the key inputs are the book value of $132.30 per share, a stable earnings power estimate of $27.24 per share, and an average return on equity of 18.38%. With the cost of equity set at $12.01 per share, the model attributes $15.23 per share to excess return, which points to a business earning more on its capital than the hurdle rate built into the analysis.
The same framework also assumes book value can move toward a stable level of $148.22 per share over time, with that path supported by analyst estimates in the background. For cross-checking with the dividend lens, the model uses current dividends of $6.83 per share and a capped long run growth rate of 3.7%, which is designed to keep the payout path consistent with the implied return on equity rather than stretching it. Despite recent headlines around blockchain expansion and security investments, the Excess Returns analysis places JPMorgan Chase's estimated intrinsic value substantially above the current share price of $331.58. Find out what JPMorgan Chase could be worth using our Excess Returns estimate.
The JPMorgan Chase Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the excess returns puzzle leaves off by making clear which paths for JPMorgan Chase's future growth, margins and earnings would need to play out for the current share price to look materially higher or lower. Each narrative ties a fair value estimate to a specific storyline about JPMorgan Chase's potential catalysts and key risks so you can track over time which version of events appears to be unfolding.
Community views on JPMorgan Chase split between those who see more upside left and those who think most of the strength is already reflected in the price.
Bull case: 12% undervalued
"Management's confidence in organic and inorganic growth, together with sustained capital deployment into new business lines such as the multi year build out of CIB and Payments, the $1.5 billion Security and Resiliency financing program and the expansion of omnichannel consumer banking and branch builds, supports a case for structurally higher long-term revenue and earnings relative to the current cost base..."
Discover why this Narrative puts JPMorgan Chase at 12% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect JPMorgan Chase to see its net and operating margins squeezed if higher expenses, tighter underwriting in areas like data centers, and pockets of consumer stress persist without matching revenue support..."
Explore why this Narrative puts JPMorgan Chase at roughly fairly valued.
One more piece of the JPMorgan Chase puzzle before you move on
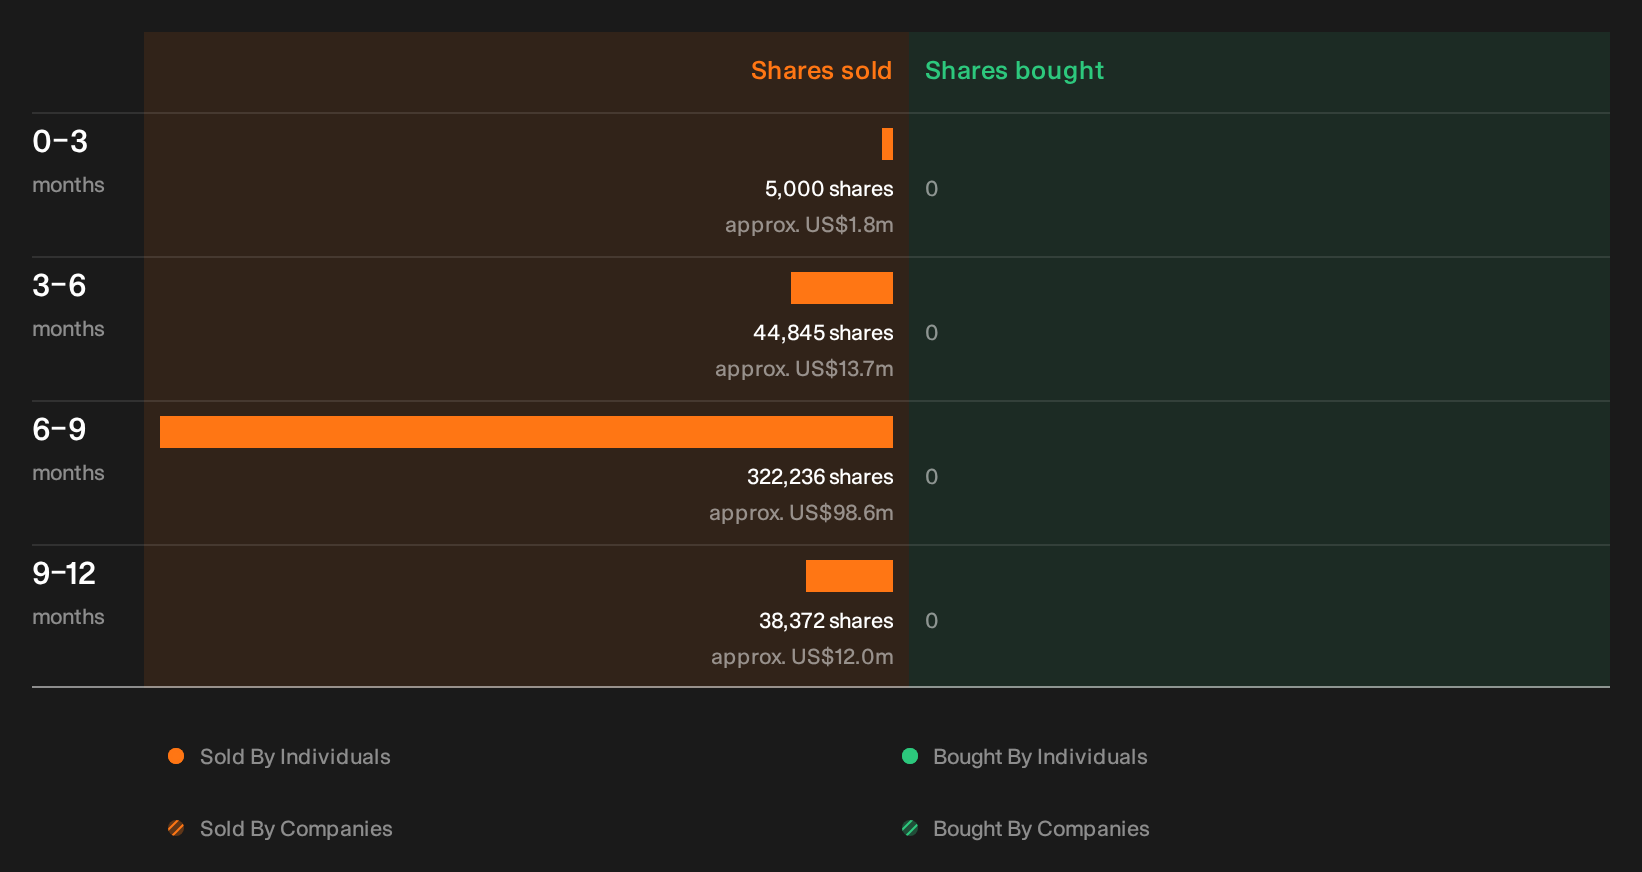
Before acting on any view of JPMorgan Chase, it is worth knowing that recent trades by people inside the business have been flagged by our checks, with the specific sellers, volumes and possible read throughs left for you to explore. See the recent insider selling flagged for JPMorgan Chase.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com