


Recent value focused research on Concentrix (CNXC) has brought the stock back onto investors’ screens, as third party analysts highlight comparatively low P/S and PEG metrics along with an attractive cash flow profile.
Recent price action around Concentrix has been choppy, with the share price falling 3.65% over the last day to US$33.00 after a strong 7 day share price return of 18.41% and a 90 day share price return of 48.31%. This contrasts with a year to date share price decline of 19.92% and a 1 year total shareholder return decline of 26.05%. This suggests momentum has picked up in the short term, even though longer term total shareholder returns over 3 and 5 years, down 49.92% and 79.15% respectively, still reflect a market that has been cautious about the story despite today’s value focused interest.
Scan beyond Concentrix and compare this setup with a curated list of value focused opportunities in our 27 high quality undervalued stocks.
After a 48.31% rebound over 90 days yet a 1 year total return still down 26.05%, Concentrix now forces a choice. Is this the moment to lean into the reset, or wait for a cleaner entry once the valuation work is done?
Most Popular Narrative: 1% Overvalued
Concentrix last closed at $33.00, almost exactly in line with the most followed narrative fair value of $32.60, which is based on a 12.54% discount rate and a detailed earnings and cash flow framework that already bakes in goodwill impairments and guidance cuts.
The current valuation, after large goodwill impairments, guidance cuts and share price declines alongside continued free cash flow, debt paydown and dividend growth, implies the market is heavily discounting Concentrix’s ability to translate its AI and iX Suite momentum into sustained earnings power and a higher share price.
See why 18 investors see Concentrix as 1% overvalued.
Result: Fair Value of $32.60 (OVERVALUED)
Still, the Concentrix story can break if revenue headwinds from client budget cuts persist, or if heavy debt and large restructuring efforts strain cash generation.
Find out about the key risks to this Concentrix narrative.
Another View: Concentrix On Cash Flow Value
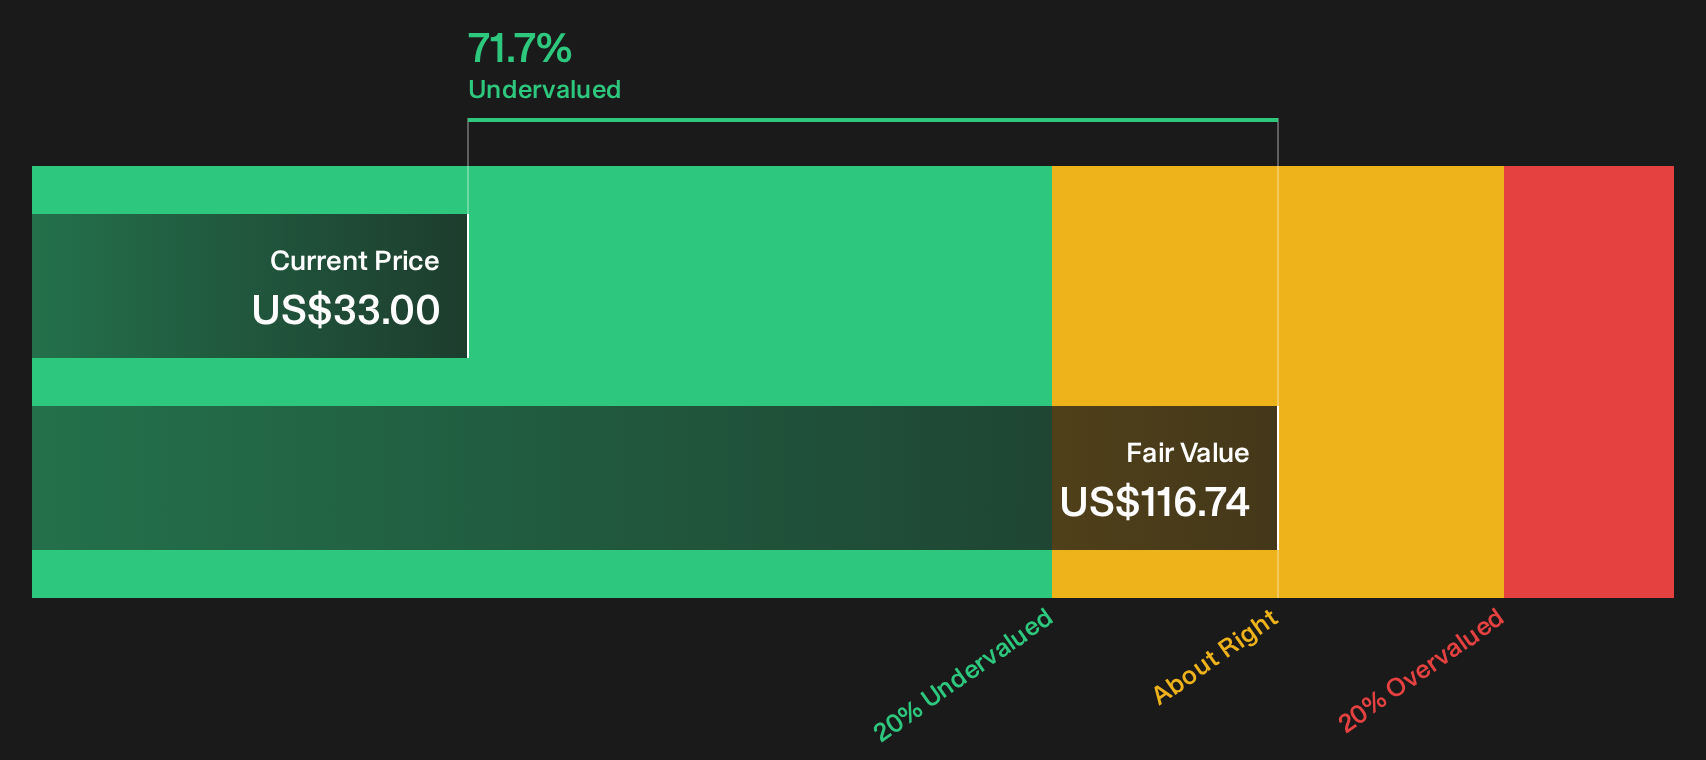
The fair value story shifts once the SWS DCF model is applied. Through this lens, Concentrix at $33 is described as trading well below an estimated future cash flow value of $116.74, which frames the stock as heavily undervalued rather than slightly overvalued. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Concentrix only matter if you act on them, so move quickly, review both the concern and optimism in detail, then weigh up the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Concentrix?
If Concentrix has you rethinking value, do not stop here. Broaden your watchlist with ideas filtered by quality, income, and resilience using targeted screeners.
- Target resilient options that prioritise capital protection using a 30 resilient stocks with low risk scores tailored to lower risk scores and sturdier fundamentals.
- Build a foundation of financially sound holdings by running a list of solid balance sheet and fundamentals (25 results) that highlights stronger balance sheets and cleaner funding profiles.
- Hunt for tomorrow’s potential standouts before the crowd spots them by scanning through a 21 high quality undiscovered gems backed by underlying fundamental strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com