


SoundHound AI has seen a sharp shift in its share price over recent years, which puts fresh attention on what investors are actually paying for each dollar of its sales. With such a wide range of outcomes in the recent return profile, the key issue is whether the current valuation still lines up with the revenue the business is generating.
- Over the past 3 years, SoundHound AI has delivered a gain of 182.2%, which raises the question of how much of that move is supported by the underlying sales base.
- The company’s focus on commercialising its voice and AI platform points directly to future revenue scale, which can shape how much investors are prepared to pay for each unit of current and potential sales.
- There is a second opinion on SoundHound AI worth weighing. See what analysts think SoundHound AI's shares could be worth.
For investors, the debate is whether SoundHound AI’s recent share price level is justified by the value the market is placing on its sales today.
If you are weighing SoundHound AI against other opportunities tied to artificial intelligence themes, it can help to compare it with 38 AI small caps.
Does SoundHound AI Look Pricey on Sales?
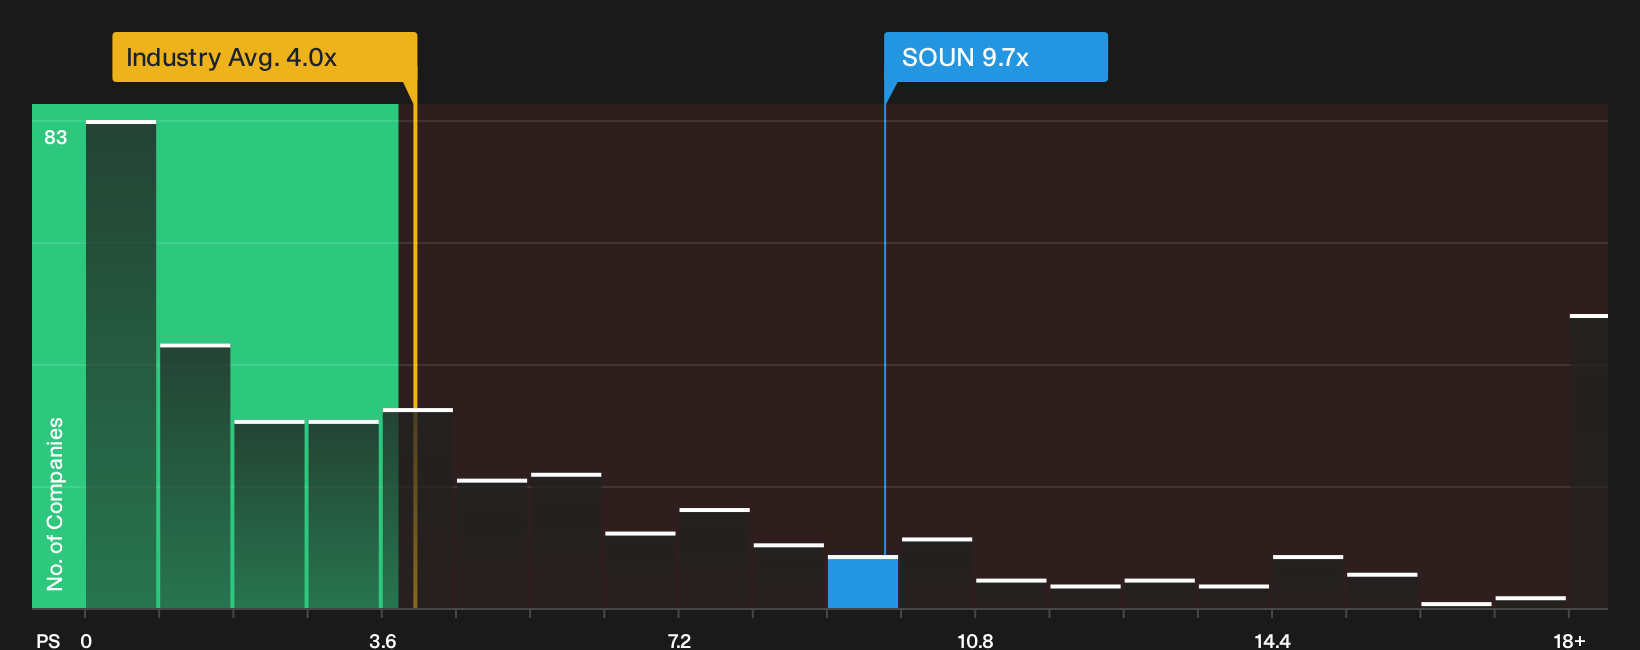
A price to sales lens suits SoundHound AI because investors are still focused on what they are paying for each dollar of revenue rather than profits. The current P/S of 9.7x sits well above the broader Software industry average of 4.0x, which already captures many growth oriented platforms. Compared with closer peers on about 6.6x sales, the stock trades on a richer tag again, so the market is clearly assigning a premium to this business model and its AI exposure.
The tailored fair multiple for SoundHound AI, which blends factors like industry, scale, growth profile and risk, points to a lower P/S than the one implied by today’s share price. That gap suggests the stock screens overvalued on this measure, so anyone buying at current levels is paying a higher price for each unit of sales than both typical software groups and the model’s own yardstick would suggest. Explore the numbers behind SoundHound AI's P/S valuation.
The SoundHound AI Narrative: What Would Justify Today's Price?
SoundHound AI’s valuation puzzle only really comes into focus once you spell out what would need to happen to growth, margins and eventual earnings for today’s share price to look either conservative or stretched. Simply Wall St Narratives on the Community page do exactly that by tying each number driven view to a clear path for future expansion, profitability and risk that you can revisit as new information arrives.
One of the top community narratives on SoundHound AI: 65% undervalued
"Expansion across multiple industries and partnerships is fueling broader adoption, improved customer diversification, and increased recurring revenue opportunities…"
Discover why this Narrative puts SoundHound AI at 65% undervalued.
For SoundHound AI, the price tag is only one decision point
Before you treat SoundHound AI’s valuation as the whole story, it is worth checking the specific concerns our research has already flagged for this business. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com