


- Waters Corporation recently announced collaborations with Labcorp and Quest Diagnostics to expand access to the BD Onclarity HPV Assay and the Onclarity Self-Collection Kit across nationwide laboratory and consumer channels in the United States.
- These partnerships shift Waters further into clinically deployed diagnostics and at-home testing, tying its instruments and software directly to large recurring screening programs across major lab networks.
- We will now assess how Waters’ deeper integration into cervical cancer screening workflows through BD Onclarity access might influence its investment narrative.
Waters Investment Narrative Recap
An investor in Waters needs to believe the enlarged group can turn its analytical instruments, BD diagnostics assets, and software footprint into steadier, higher quality earnings despite recent margin pressure and a large one off loss. The near term catalyst is execution on integration and cost synergies while keeping the instrument replacement backlog and consumables momentum intact.
The biggest risk remains complexity. Waters is layering clinically deployed testing, including BD Onclarity programs with Labcorp and Quest, on top of an already intensive carve out from BD. Any stumble in systems integration, China recovery, or reimbursement dynamics could weigh on margins and call the current growth algorithm into question.
The Quest Diagnostics collaboration around the Onclarity Self Collection Kit is most relevant here. It ties Waters instruments, software, and BD Onclarity testing into Quest’s broad clinician, payer, and consumer channels, plus roughly 2,000 patient service centers, starting in 2027. That expands Waters’ role from research labs into routine cervical screening workflows at real scale.
This matters for the story because it points to more recurring, application specific usage on top of the installed base while the BD Diagnostic Solutions integration is still bedding down. It also increases operational exposure to high volume clinical testing, where any throughput issues, quality problems, or slower than expected kit adoption would quickly show up in utilization and in perceptions of Waters’ execution.
Waters' current analyst script points to revenues of US$7.9b and earnings of US$1.4b by 2029. That profile rests on revenue expanding at 19.3% a year and earnings rising by about US$1.2b from US$166.6m today.
Uncover why Waters' fair value is essentially aligned with its current price.
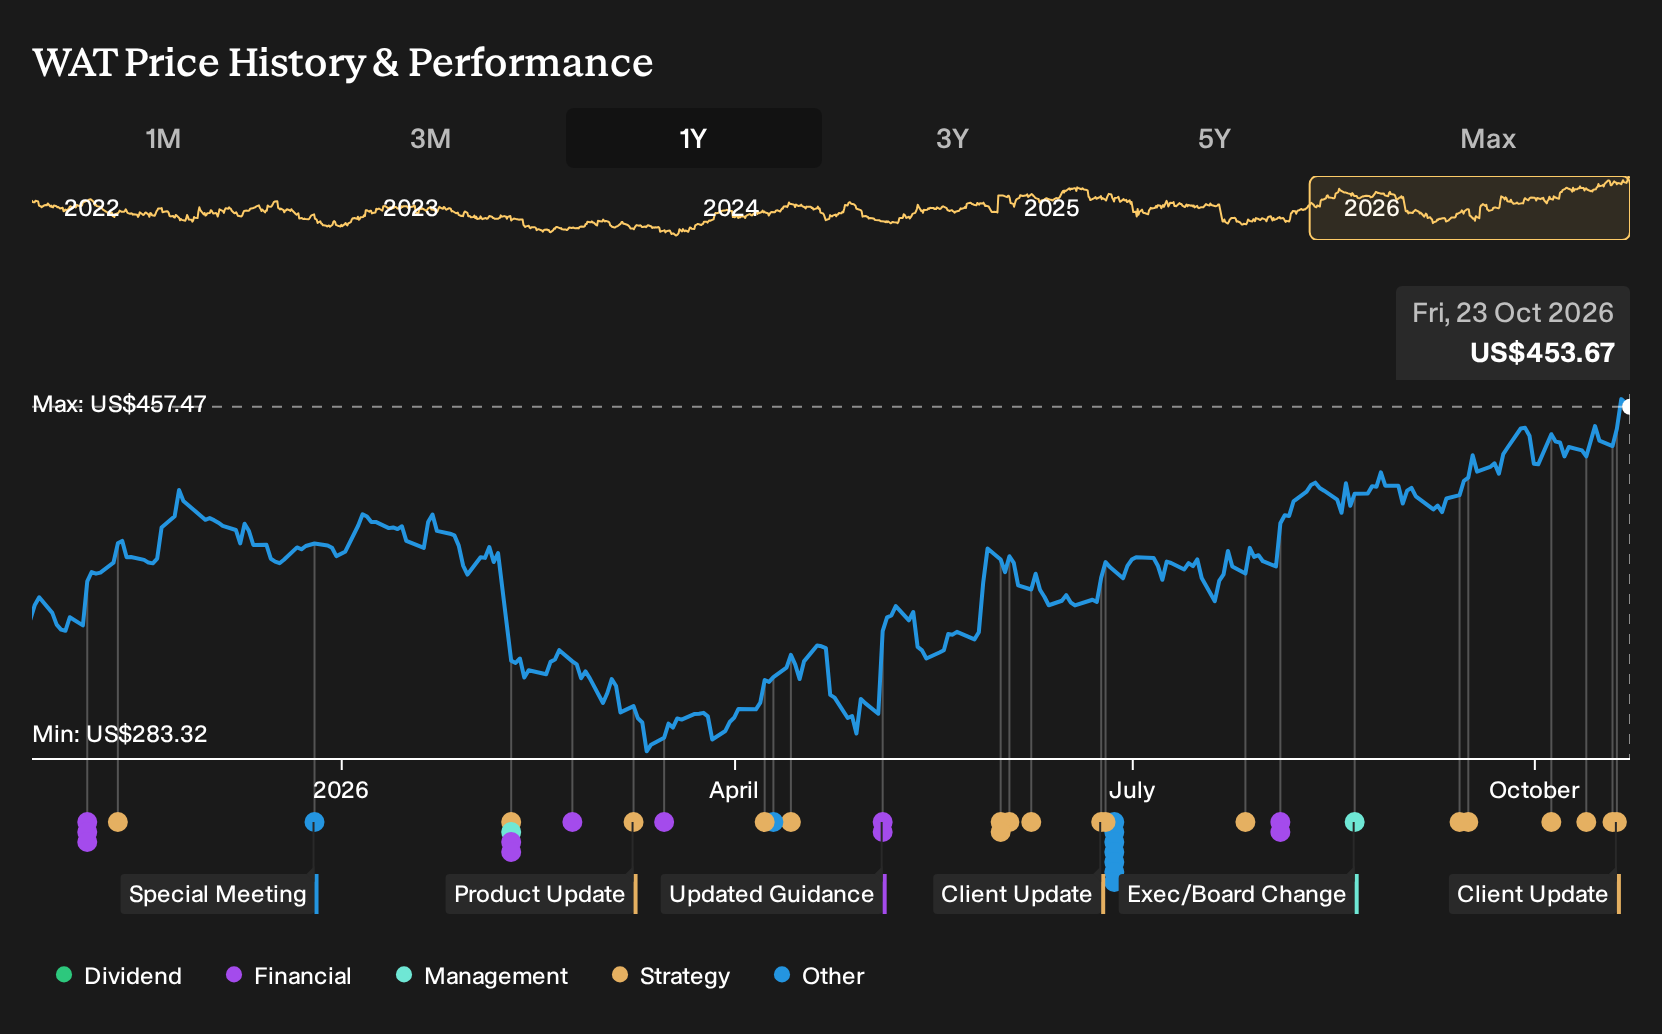
Exploring Other Perspectives
Some of the most optimistic analysts focus less on integration risk and more on Waters using BD Onclarity and other clinical assays to push recurring diagnostics higher. Before this news, the bullish camp was already penciling in US$8.7b of revenue and US$1.6b of earnings by 2029. You can now ask whether the new Labcorp and Quest deals might pull those expectations even further apart from the more cautious US$7.9b and US$1.4b baseline, and decide which version of the story feels closer to your own view.
Explore 3 other Waters fair value estimates, including one that suggests up to 17% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking For More Ideas Beyond Waters?
Once the Waters story is clear in your mind, it can help to set it alongside other opportunities so you can judge risk, quality, and income potential on a broader field.
- If you care most about durable balance sheets and resilient fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can anchor a more conservative core.
- For investors hunting for quality at a sensible entry point, scan through 27 high quality undervalued stocks that may offer a more appealing price tag relative to fundamentals.
- If cash returns matter to you, focus on income streams backed by resilient businesses by reviewing 5 dividend fortresses that combine yield with financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com