


- CGN New Energy Holdings reported consolidated power generation of 1,409.6 GWh for September 2026, up 3.9% year on year. Strong PRC wind and solar output offset weaker gas, hydro and Korea contributions.
- The nine-month figure edged down 0.1% to 14,128.8 GWh. However, PRC solar rose 20.4% and Korea projects gained 11.2%, highlighting a clear tilt toward renewables within the portfolio mix.
- Attention now turns to how CGN New Energy Holdings' investment narrative incorporates this stronger PRC solar and wind performance within an otherwise mixed generation profile.
Scan CGN New Energy Holdings' shift toward wind and solar against a curated 16 nuclear energy infrastructure stocks that could benefit from similar renewable and low carbon infrastructure momentum.
What Is CGN New Energy Holdings' Investment Narrative?
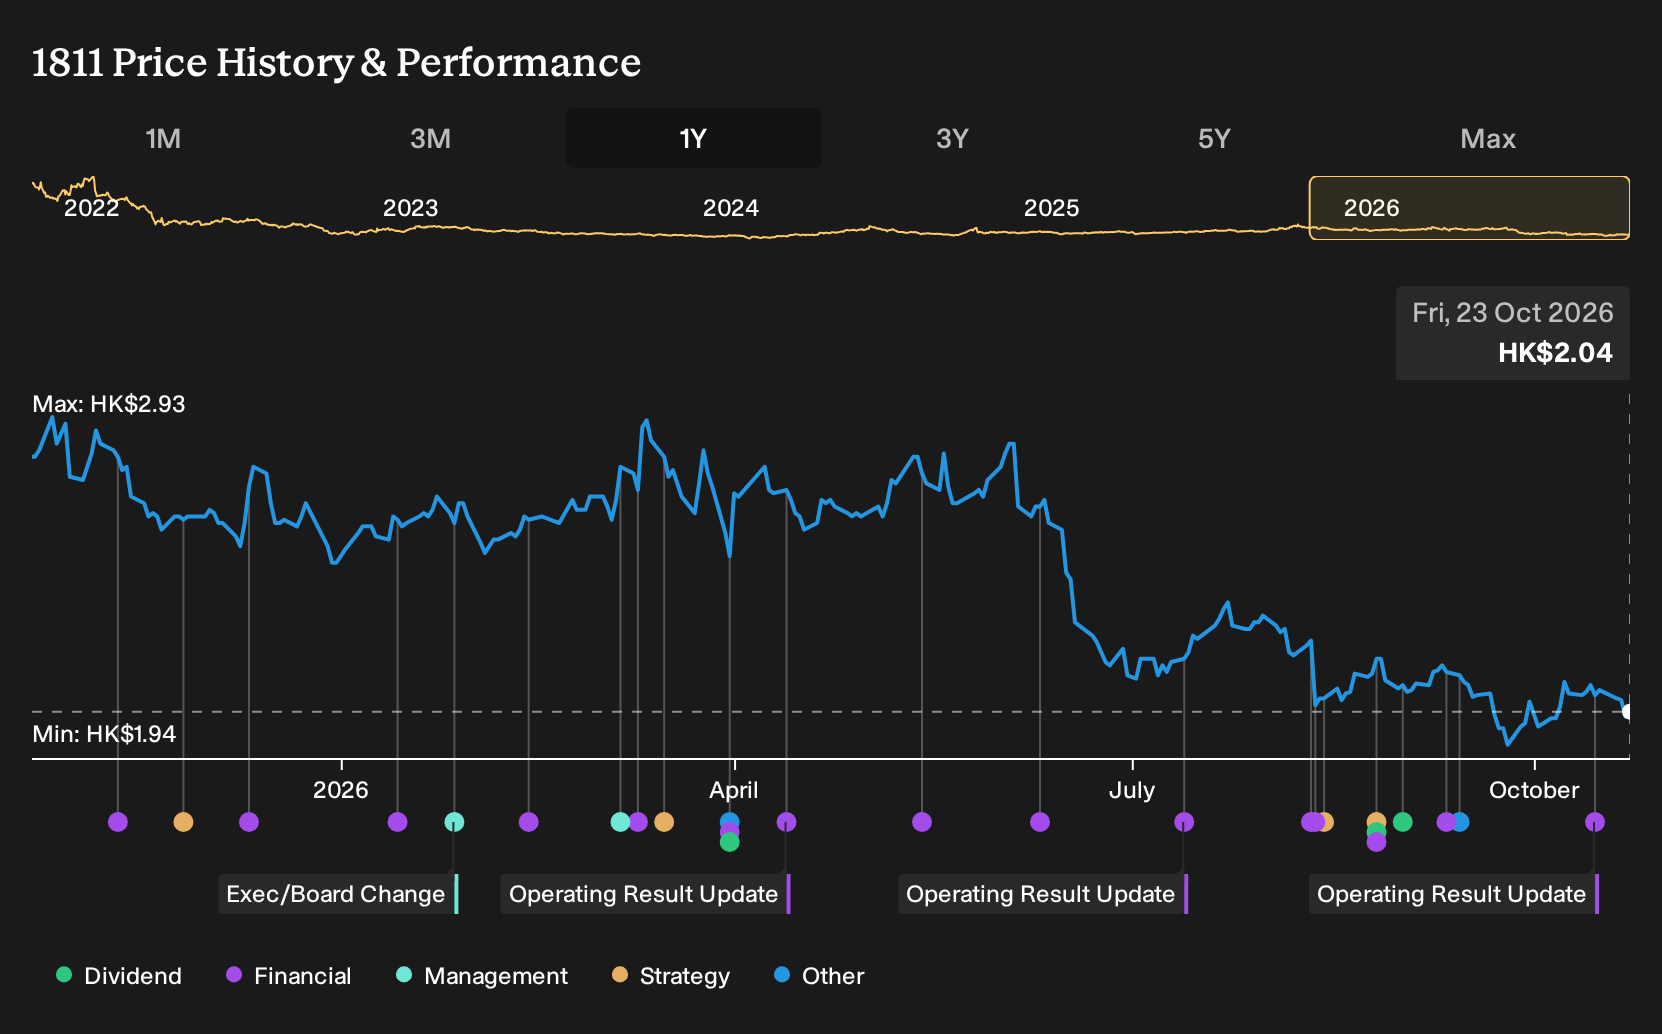
To own CGN New Energy Holdings, you need to be comfortable with a utility that is gradually leaning harder into renewables while carrying some financial strain in the background. September’s data, with stronger PRC wind and solar offset by weaker gas and hydro, underlines that tilt. The near term story still hinges on execution in PRC projects, tariff and offtake stability, and the capital required to keep adding capacity without stretching a balance sheet where interest costs are not well covered by earnings.
In the short term, this operating update looks more like a refinement of the thesis than a reset. The nine month generation figure is broadly flat, yet the mix shifts further toward PRC solar and Korea projects and away from gas. That suits investors who are looking at CGN New Energy Holdings as a lower valuation, renewable heavy platform with forecast earnings and revenue growth that is steady rather than rapid. However, it also puts more pressure on management to control funding costs and an already uneven dividend record.
Even so, there is a catch that sits uncomfortably next to the low P/E and renewable tilt story...
There's only one way to know the right time to buy, sell or hold CGN New Energy Holdings. Head to Simply Wall St's company report for the latest analysis of CGN New Energy Holdings's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CGN New Energy Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CGN New Energy Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGN New Energy Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond CGN New Energy Holdings?
If you want to stress test your view on CGN New Energy Holdings, compare it with a wider watchlist built using targeted stock lists that focus on quality, value, income, and resilience.
- For income focused portfolios that rely on regular cash returns, compare CGN New Energy Holdings with a curated set of 226 dividend fortresses.
- If capital preservation sits higher on your checklist, weigh the profile of CGN New Energy Holdings against 221 resilient stocks with low risk scores that score well on stability and downside resilience.
- When you want to hunt for less crowded ideas with solid fundamentals, contrast CGN New Energy Holdings with 615 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com