


- PPG Industries declared a regular quarterly dividend of US$0.74 per share, payable on 11 December 2026 to shareholders of record on 10 November 2026, while also proceeding with the closure of its Greenville facility that is expected to cut 52 jobs as part of a business restructuring.
- The Greenville shutdown highlights how PPG Industries is adjusting its cost base and footprint while keeping cash returns to shareholders intact through a maintained dividend.
- We will assess how PPG Industries' investment narrative is affected by this Greenville facility closure as management reshapes the operating footprint.
Scan how PPG Industries' dividend stance compares by lining up its profile against a hand-picked 5 dividend fortresses that also keep cash returns front and center as operations evolve.
PPG Industries Investment Narrative Recap
To own PPG Industries, you need to be comfortable with a coatings group that is still shifting its footprint while leaning on cost cuts and product mix to support earnings quality. The Greenville closure fits that pattern. It tightens the manufacturing base, yet the core story still leans on execution in aerospace, protective and marine, and industrial coatings.
The near term swing factor remains how well PPG Industries handles margin pressure in Industrial Coatings as raw materials move ahead of indexed pricing. That sits next to currency and automotive demand as key watchpoints. Greenville looks operationally contained, so the bigger risk still lies in prolonged margin compression rather than this single plant exit.
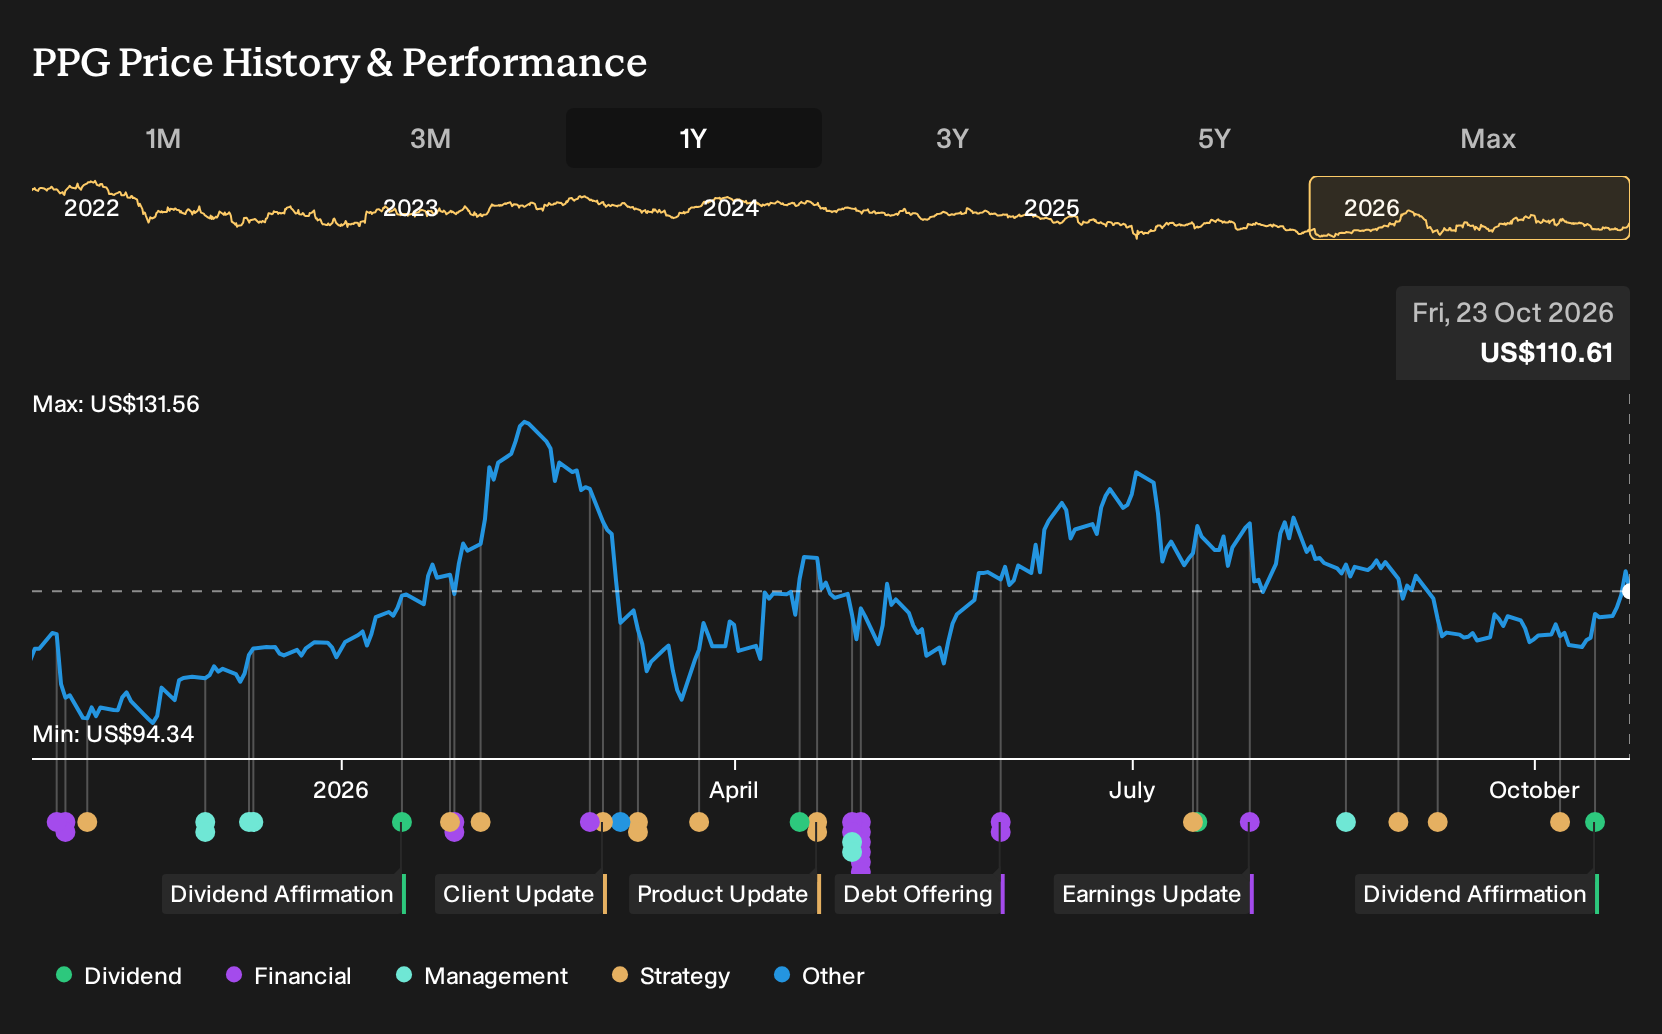
The recent affirmation of a US$0.74 per share quarterly dividend is the clearest signal linked to this news. While the firm restructures its footprint, including Greenville, it is also continuing regular cash distributions. For income focused holders, that combination puts attention on whether future cost savings and growth initiatives comfortably fund both operations and ongoing payouts.
For catalyst minded investors, the dividend decision intersects directly with planned structural savings from plant closures and PPG Industries spending on new capacity in aerospace and industrial coatings. The payout, the Greenville shutdown and other planned site actions all feed into one question: can the business keep funding portfolio upgrades and still service a reliable dividend over time?
PPG Industries' current analyst script points to revenues of US$18.0b and earnings of US$1.9b by 2029, built on assumed annual revenue growth of 3.0% and an earnings step up of US$0.3b from about US$1.6b today.
Uncover why PPG Industries' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$125.50 to about US$202.22, so private investors are assigning very different upside and downside to PPG Industries. Factor in risks such as ongoing EBITDA margin pressure in Industrial Coatings and potential currency drag, then explore these contrasting viewpoints before leaning on any single narrative.
Explore 2 other PPG Industries fair value estimates, including one that suggests up to 83% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your PPG Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PPG Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PPG Industries' overall financial health at a glance.
Looking for more PPG Industries style investment ideas?
If this PPG Industries review has sharpened your thinking, broaden your watchlist by using the Simply Wall St screener to line up other stocks with traits that fit your own playbook.
- For investors who want potential mispricing paired with quality fundamentals, start by scanning a 27 high quality undervalued stocks that may merit a closer look.
- If capital preservation and steadier profiles rank higher for you, narrow the field to a 30 resilient stocks with low risk scores that scores well on resilience.
- When you want strong finances to back the story, filter for a list of solid balance sheet and fundamentals (25 results) and see which businesses clear your quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com