


Ardagh Metal Packaging (AMBP) is back in focus after reporting third quarter 2026 earnings that topped revenue estimates, lifting its full year adjusted EBITDA outlook and backing that update with fresh European capacity investments.
The share price reaction has cooled in the very short term, with Ardagh Metal Packaging down 3.59% on a 1 day basis and 2.56% over 7 days. This comes even though the 1 month share price return of 2.47% and year to date gain of 9.88% point to improving momentum, backed by a 1 year total shareholder return of 32.62% and a 3 year total shareholder return close to 2x. This is set against a weaker 5 year total shareholder return that remains 25.28% lower.
Scan beyond Ardagh Metal Packaging and compare this earnings story with a curated group of income-focused stocks in our 5 dividend fortresses to see how other payouts stack up.
For Ardagh Metal Packaging, the recent pullback comes after strong reported numbers and a higher EBITDA outlook. The live question now is whether valuation still leaves meaningful upside, or if most of the easy money has already gone.
Most Popular Narrative: 12% Undervalued
Set against the last close at $4.56, the most followed fair value narrative for Ardagh Metal Packaging at $5.16 points to a modest gap that hinges on execution around growth, leverage and cash generation.
The combination of resilient double-digit shipment growth in the Americas and disciplined capital investments has led to deleveraging, greater financial flexibility, and a strong liquidity position, positioning the company to grow free cash flow and support ongoing dividends and reinvestment, all of which should drive higher future earnings per share.
See why 10 investors see Ardagh Metal Packaging as 12% undervalued.
Result: Fair Value of $5.16 (UNDERVALUED)
Still, high net leverage and ongoing volatility in aluminum input costs could quickly challenge the current fair value story for Ardagh Metal Packaging.
Find out about the key risks to this Ardagh Metal Packaging narrative.
Another View: What Ardagh Metal Packaging’s P/E Is Telling You
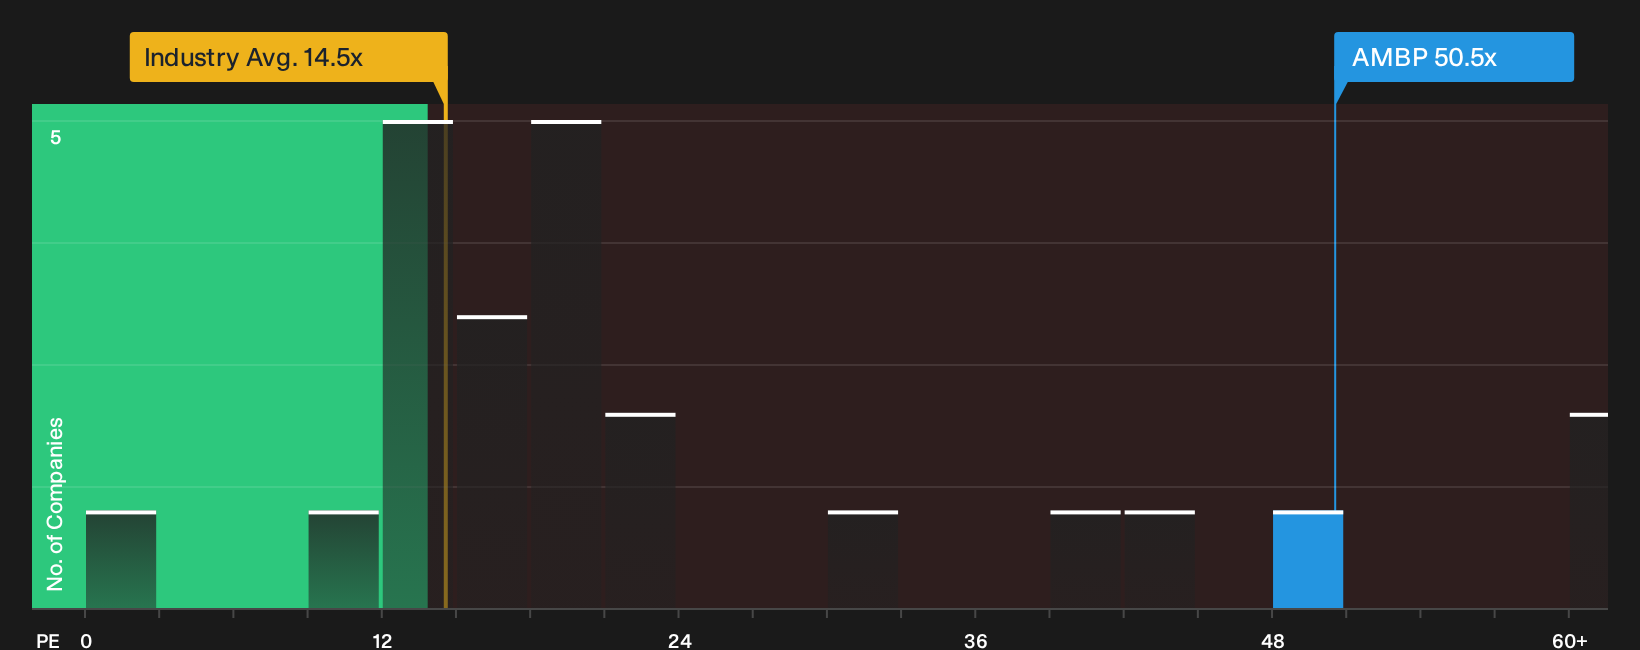
The fair value narrative presents Ardagh Metal Packaging as modestly undervalued, yet the current P/E of 50.5x tells a different story. That figure sits well above the global packaging group at 14.5x and the fair ratio of 26.3x, which suggests meaningful valuation risk if sentiment cools.
For anyone weighing that gap, the key question is whether earnings can grow fast enough to close it before the market pushes the multiple back toward the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Ardagh Metal Packaging leaves you torn, take a closer look at both sides and move quickly to shape your own view with 3 key rewards and 4 important warning signs.
Looking for more Ardagh Metal Packaging sized opportunities?
If you like the Ardagh Metal Packaging story but do not want all your risk in one place, use the Simply Wall Street Screener to build a broader investing shortlist that fits your goals and time horizon.
- Target stability first by scanning a 30 resilient stocks with low risk scores that can help you avoid fragile businesses before they hit your portfolio.
- Hunt for value by reviewing a curated 21 high quality undiscovered gems that might not yet be on every analyst's radar.
- Prioritise resilience by filtering a list of solid balance sheet and fundamentals (25 results) so you are not caught holding companies with stretched finances when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com