


Worthington Enterprises (WOR) is stepping into the spotlight after announcing its participation at the Baird Global Industrial Conference and a dedicated Investor and Analyst Day focused on long-term strategy, financial performance, and growth priorities.
Against that backdrop, Worthington Enterprises is trading at US$63.65, with the share price up 6.62% over the past month and 13.66% across 90 days. The year-to-date share price return of 22.50% and 1-year total shareholder return of 10.28% point to momentum that has cooled slightly compared with the much stronger 3- and 5-year total shareholder returns of 77.17% and 107.37%.
Scan how Worthington Enterprises compares with a hand picked 21 high quality undiscovered gems list that is also drawing fresh attention from investors after catalysts around capital allocation, acquisitions, and long-term plans.
Worthington Enterprises now trades about 10% below the average analyst target and at a deeper implied discount to intrinsic value. Is that a sensible margin of safety, or is the market pricing in real risks?
Most Popular Narrative: 10% Undervalued
Worthington Enterprises is priced at $63.65 against a widely followed fair value view of $70.40, which frames the current discount as a test of how much weight investors put on its data center exposure and higher margin building products push.
The main thing that has to go right is that Worthington Enterprises continues to execute on higher margin building envelope acquisitions and the Worthington Business System so that free cash flow and margins stay strong while new platforms like data center ASME tanks scale.
See why 3 investors see Worthington Enterprises as 10% undervalued.
Result: Fair Value of $70.40 (UNDERVALUED)
Still, the Worthington Enterprises story can change quickly if steel costs spike again or if future acquisitions repeat the margin pressure seen with Elgen.
Find out about the key risks to this Worthington Enterprises narrative.
Another View: What P/E Says About Worthington Enterprises
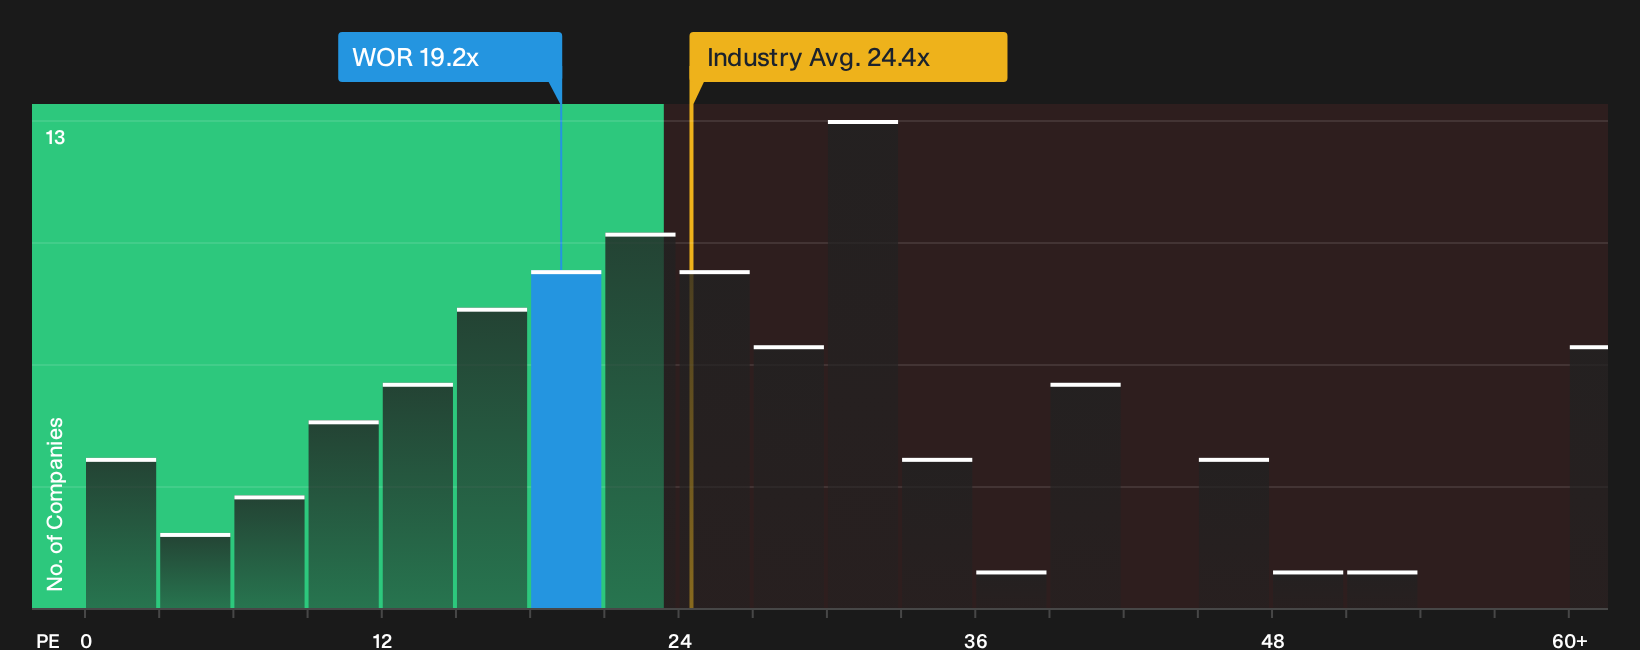
The DCF work presents Worthington Enterprises as undervalued, yet the P/E picture is less generous. At 19.2x earnings, the stock trades above its own fair ratio of 18x, even though it sits below both peer levels at 23.2x and the broader US Machinery industry at 24.8x.
That combination of a premium to its fair ratio but a discount to peers suggests valuation risk in both directions. Investors are not paying the highest sector multiples, yet there is less flexibility if the Worthington Enterprises story disappoints or if sentiment toward the industry cools quickly.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Worthington Enterprises is mixed, which is exactly why it helps to walk through the data yourself and pressure test the assumptions. To see what investors view as the main positives and decide how much weight to give them, start with 3 key rewards.
Looking for more investment ideas beyond Worthington Enterprises?
If you only stop at Worthington Enterprises, you risk missing other opportunities that line up better with your goals, risk tolerance, and time horizon.
- Target value hunting by scanning a curated pool of quality businesses trading below their implied worth through 27 high quality undervalued stocks.
- Prioritize resilience by focusing on companies with cleaner finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Chase under-the-radar potential by zeroing in on high quality smaller players that many investors overlook with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com