


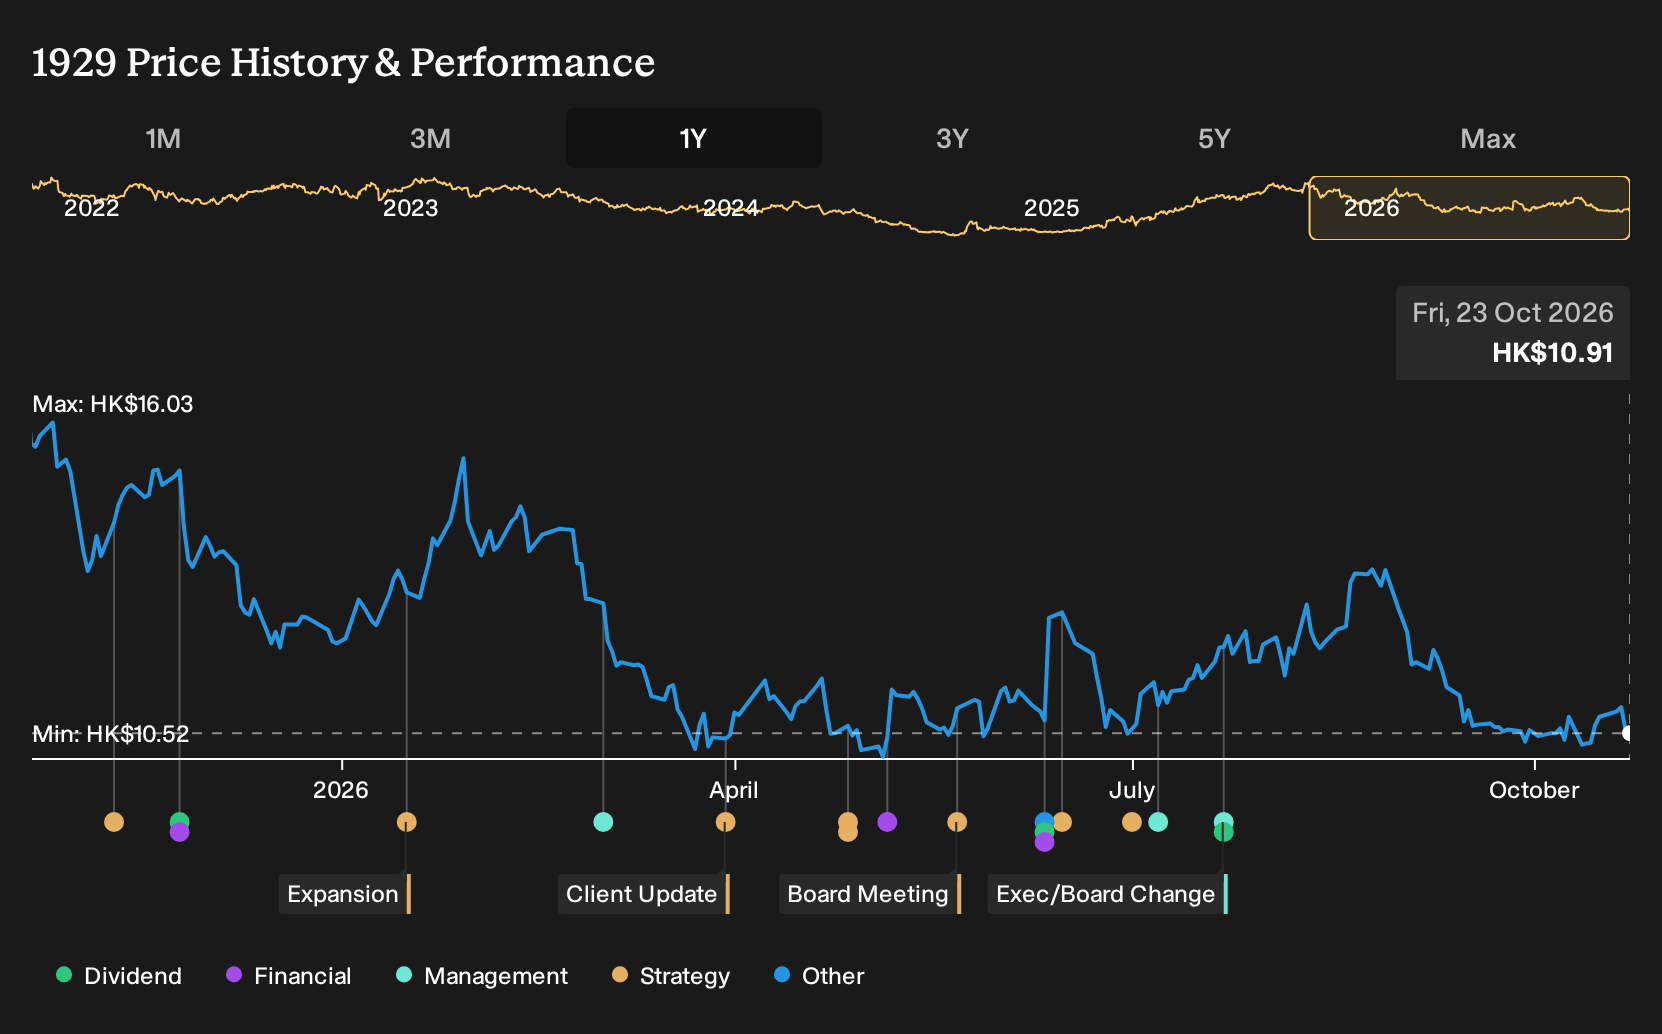
If you had paused in October 2025 and chosen not to back Chow Tai Fook Jewellery Group while analysts argued over HK$17 versus HK$12 fair value, the next year would have looked very different from what that debate implied. Investors who held Chow Tai Fook Jewellery Group over the past year are down 27.1%, including dividends. With that outcome now on the table, which assumptions from those bullish and bearish cases most deserved closer scrutiny at the time?
If the move has made Chow Tai Fook Jewellery Group harder to judge, start where the gap is still open and scan 192 high quality undervalued stocks.
The Argument Investors Faced On Chow Tai Fook Jewellery Group
The shares cost HK$15.63 at the start of the period, and Chow Tai Fook Jewellery Group sat between two very different stories about what might come next.
On the bullish side, one camp saw a Fair Value of HK$17, a price that would only make sense if digital retail, asset light franchising, and premium products turned immersive stores into much higher margin outlets.
The bearish cohort argued for a Fair Value of HK$12, assuming reliance on Greater China and rising lab grown diamond adoption would squeeze pricing power and cap long term jewellery demand.
What The Results Changed For Chow Tai Fook Jewellery Group
Chow Tai Fook Jewellery Group reported H2 2026 revenue of HK$55,412.3m and net income of HK$6,470.7m, with net margin rising to 11.7%. That margin shift gave the bullish profitability story fresh support, while the launch of Chow Tai Fook Home and the flagship Hong Kong store pointed to brand broadening that challenged the most cautious stagnation fears. Overall, the evidence cut both ways.
The useful takeaway is clear. When a thesis hangs on premiumisation and brand transformation, treat net margin and product-mix disclosures as the primary checkpoints. Then weigh them against any claims about slowing end demand.
What You Would Be Paying For In Chow Tai Fook Jewellery Group Today
Chow Tai Fook Jewellery Group now trades at HK$10.91, after the share price declined 27.1% over the past year. The selected narrative sees fair value above that level, built around a premium product mix, higher productivity formats, and wider use of digital planning tools.
For that higher figure to play out, a buyer today would need to believe Chow Tai Fook can sustain record level profitability while scaling its brand transformation and network upgrade.
"Key takeaways: Some analysts expect Chow Tai Fook Jewellery Group to keep shifting its mix toward higher margin fixed price collections, immersive store formats and international flagship concepts, with the aim of compounding revenue and earnings ahead of what is currently priced in. The main thing that has to go right is that the company sustains record level profitability and return on equity while executing its brand transformation, network upgrade and digital planning rollout across a larger store base and product range."
The price and this Narrative do not agree. → Uncover what this Narrative says Chow Tai Fook Jewellery Group is actually worth
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 33% below our estimate - targets tax efficient fundraising mandates across real assets while holding operating costs in check.
- Company 2 - 42% below our estimate - wins forensic software subscriptions as agencies upgrade workflows for complex mobile evidence.
- Company 3 - 21% below our estimate - supplies optical transport gear for bandwidth upgrades tied to AI heavy data traffic.
Those are three of them. See all 204 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com