


S&P Global (SPGI) has just paired a fresh omnibus shelf registration with new AI driven upgrades to its iLEVEL private markets platform, giving the business more funding flexibility alongside deeper data and workflow tools.
Recent news around the shelf registration and AI driven iLEVEL upgrades comes at a time when momentum in S&P Global’s share price has started to firm up over the past month, even though the year-to-date share price return is still down 12.16% and the 1-year total shareholder return is slightly negative at 1.87%.
Compare S&P Global’s AI and data strategy with other potential opportunities by scanning our hand picked 39 profitable AI stocks that aren't just burning cash that are already turning AI into earnings power.
S&P Global is often viewed as a high quality data powerhouse, yet the share price has only recently started to recover while growth has trailed peers. The key question is whether investors are paying up for resilience or overpaying for slower momentum as valuation considerations come into focus next.
Most Popular Narrative: 18.5% Overvalued
On the narrative numbers, S&P Global’s fair value of $380 sits well below the latest close at $450.31. This frames the current rebound as a premium pricing story rather than a bargain.
S&P Global has strong long-term fundamentals, but in the near term, it faces AI-related uncertainty, slower growth expectations, and shifting investor sentiment. At its core, the softer guidance in the ratings segment is being interpreted as a signal about the broader economic environment. When companies pull back on issuing new debt or refinancing existing obligations it often reflects caution.
See why 30 investors see S&P Global as 19% overvalued.
Result: Fair Value of $380 (OVERVALUED)
Still, if S&P Global surprises with stronger debt issuance trends in Ratings, or shows clear AI driven pricing power in data, this overvaluation thesis could crack.
Find out about the key risks to this S&P Global narrative.
Another View On S&P Global’s Valuation
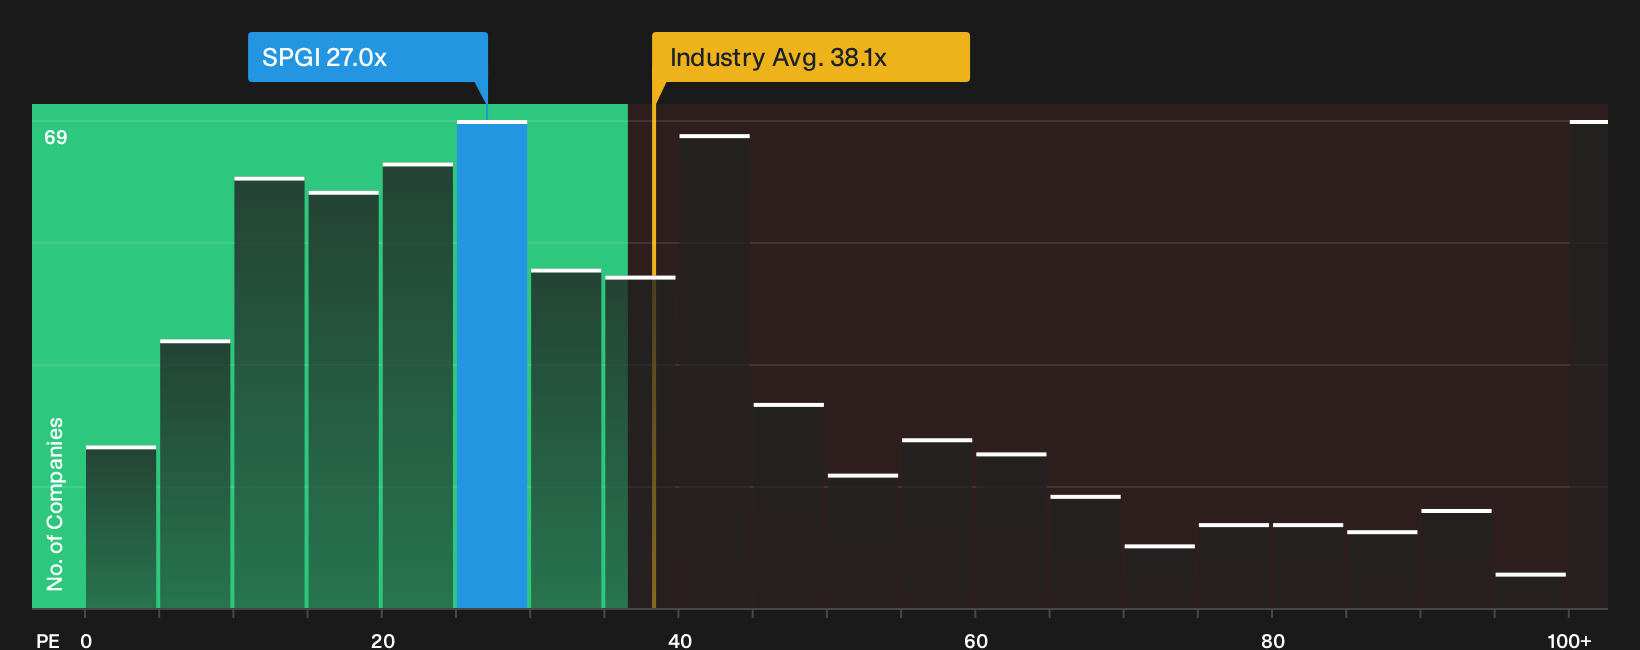
A second lens tells a different story. S&P Global trades on a P/E of 27x, which is lower than the US Capital Markets industry at 38.1x, yet slightly higher than the peer average at 26x and above a fair ratio of 16.5x. That mix of relative discount and fair ratio premium raises a simple question: is this pricing a cushion for quality, or a risk if sentiment cools further?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The story so far leans cautious on S&P Global, yet the upside case has its own supporters. Act before sentiment moves again and review the positives yourself by checking the 3 key rewards.
Looking for more investment ideas beyond S&P Global?
Do not stop with S&P Global. Give yourself options by scanning other opportunities, so your next move is based on a wider field of potential winners.
- Target potential mispricing by hunting for quality companies trading below their estimated worth through our 27 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with reliable cash returns using the 5 dividend fortresses.
- Dial down portfolio stress by zeroing in on financially resilient stocks via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com