


If you had paused on 23 October 2025, staring at Subsea 7 after a year of strong headlines about backlog, alliances and decarbonization risk, the choice hardly felt easy. For Subsea 7 shareholders, the return over the past year was 77.2%, including dividends. If you were weighing that buy decision then, the real question was simple: were the deepwater contracts and early renewables moves enough to outweigh ESG and energy transition pressure?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Subsea 7 has already moved. See which of 192 high quality undervalued stocks still trade below our estimates.
The Two Subsea 7 Stories Investors Were Arguing About
The shares cost NOK193 at the start of the period, and Subsea 7 sat between two clear stories about its future. Both rested on the same backlog and alliance headlines, but they pulled expectations in very different directions.
The bullish Narrative pinned Fair Value at NOK268 and leaned on deep revenue visibility. Supporters focused on rising backlog quality and the idea that closer client engagement and integrated engineering would lift net margins and keep vessel utilization high through industry swings.
The bearish view put Fair Value at NOK159 and stressed decarbonization risk. That camp worried that accelerating ESG pressure, overcapacity in offshore services, and tougher contract terms could compress margins and slow or even reverse future revenue growth.
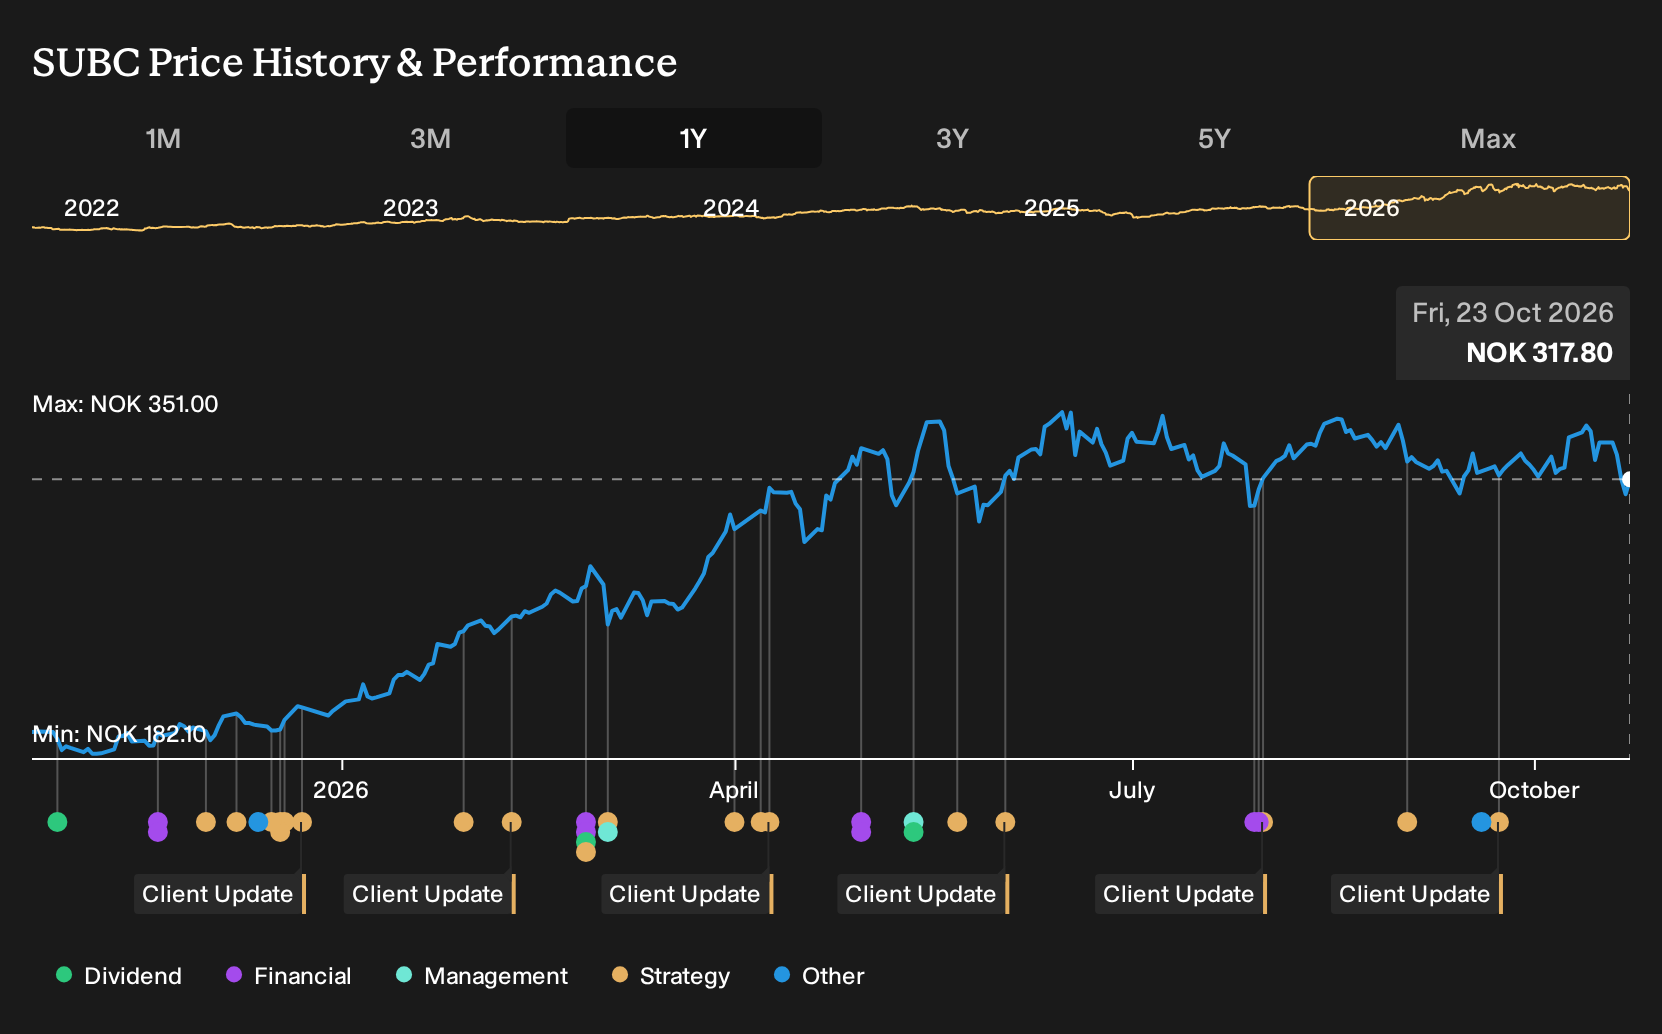
What The Results Changed For The Subsea 7 Debate
Subsea 7’s Q2 2026 report showed revenue at US$1,927.4m and net income at US$253.9m, with net margin rising to 13.2% from 7.6%. That tilt in profitability supported the bullish argument about higher earnings power. At the same time, the ongoing Saipem merger review in Europe kept the regulatory and competition overhang alive, so the evidence still cut both ways.
The key hinge was margin quality versus long term project risk. For a similar stock, test any upbeat story about backlog or alliances directly against reported net margin and how it moves over several reporting periods.
What Subsea 7’s Price Already Assumes
Subsea 7 now trades at NOK318 after a 77.2% gain over the past year, and the selected Narrative’s Fair Value sits below that level. The concern is less about past execution and more about what happens as today’s high margin backlog rolls into tomorrow’s order book and cash flows.
At this price you are effectively assuming strong tender conversion, healthy utilization and solid cash generation carry on. The selected Narrative asks how that stacks up against working capital outflows, a renewables lull and merger scrutiny that could all tug at those assumptions.
"The main thing that has to go right is that Subsea 7 converts its large subsea tendering pipeline, long term alliances and current high margin backlog into future work at similar terms, despite offshore wind sanctioning lulls, working capital unwinds and ongoing merger scrutiny."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Beyond Subsea 7’s Ocean Projects
Once you understand Subsea 7, you start spotting related pressures elsewhere. Offshore engineering still depends on long projects and heavy capital plans.
The same project cycles lean on reliable fuel supply and flexible power. One large integrated operator is quietly trying to span that full chain.
It channels investment into lower cost oil and gas fields with tighter methane controls. At the same time, it is growing a power arm focused on recurring cash.
If that mix keeps tilting toward electricity and cleaner molecules, your energy exposure changes. It can look very different from a pure subsea contractor’s profile.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 20% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com