


- Gates Industrial has launched the Gates IntraLogix LRB-100 live roller belt for high duty warehouse and distribution conveyors, using a homogeneous polyurethane design that aims to extend belt life, reduce maintenance and support lower drive tensions.
- The LRB-100 release gives Gates Industrial another product targeting warehouse automation, a segment closely tied to rising e-commerce fulfillment needs and continuous run conveyor systems.
- The following section examines how Gates Industrial's investment narrative could be influenced by the LRB-100 belt, which is aimed at warehouse automation.
Scan how Gates Industrial's warehouse automation push compares by lining up similar operators using our curated list of 42 power grid technology and infrastructure stocks as a starting point.
Gates Industrial Investment Narrative Recap
To own Gates Industrial, you need to believe the business can keep shifting more of its mix toward higher value belt and fluid solutions while managing slower end markets in traditional auto and industrial OEM channels. The LRB-100 launch fits that story, but on its own it is incremental rather than a game changer for revenue today.
The near term swing factor still sits with execution against margin targets and earnings delivery around upcoming results on 30 October. The biggest risk remains prolonged softness in North American and EMEA industrial and construction demand, which could keep organic growth muted even if products like LRB-100 perform well.
The LRB-100 announcement feels most relevant because it links directly to one of Gates Industrial key catalysts. Management is investing in new belt platforms that aim to convert more warehouse and industrial drive systems from chains and conventional belts.
If LRB-100 and the broader IntraLogix range gain traction, that would support the thesis that research and development spending and product refreshes can expand the installed base and reinforce recurring aftermarket demand. The operational test metrics, such as lower elongation and higher abrasion resistance, provide tangible data points to watch as automation customers adopt the product.
Gates Industrial's current analyst narrative points to revenues of US$4.1b and earnings of US$435.2 million by 2029. This outlook is built on an assumed 5.0% yearly revenue growth rate and an earnings increase of about US$71.1 million from current earnings of US$364.1 million.
Uncover why Gates Industrial's fair value indicates a 33% potential upside to its current price that could narrow quickly.
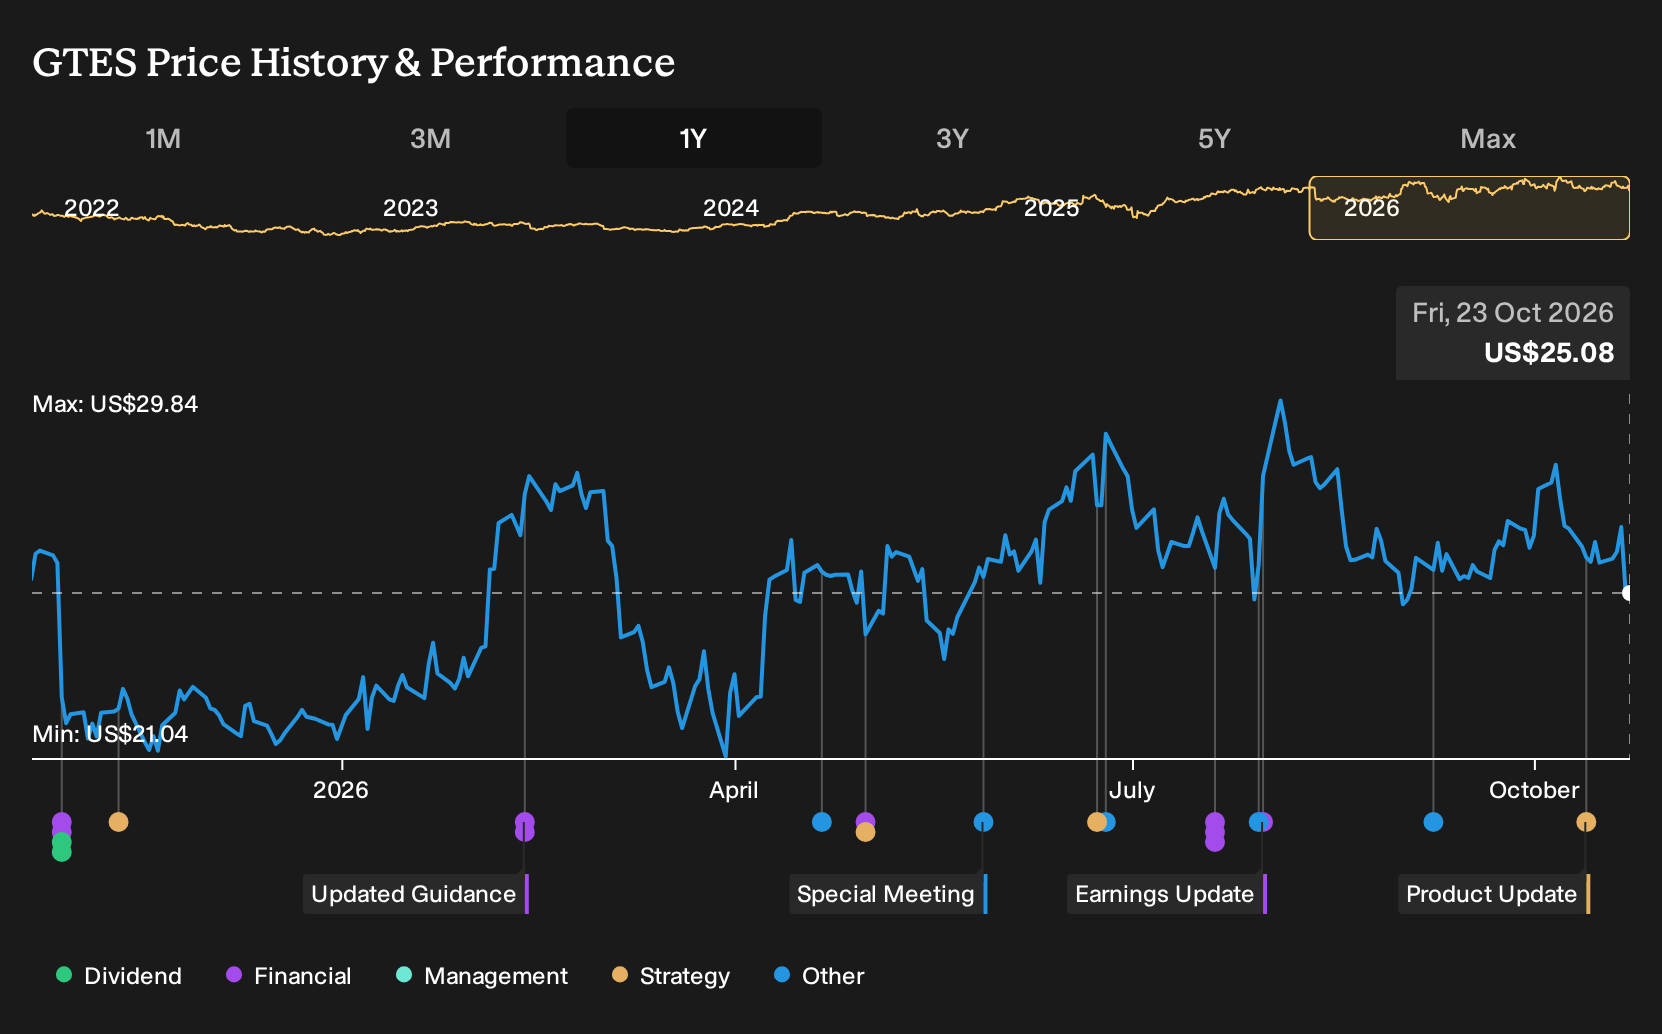
Exploring Other Perspectives
One alternative angle on Gates Industrial focuses less on warehouse automation upside and more on execution risk around footprint and ERP projects. The most cautious analysts were modelling only US$4.0b of revenue and US$399.3 million of earnings by 2029. That is a much cooler story. Use that gap as a prompt to explore several viewpoints that may shift as the LRB-100 launch gets digested.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Gates Industrial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Gates Industrial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gates Industrial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gates Industrial?
If you want to pressure test your view on Gates Industrial, it helps to see how other companies stack up on quality, income potential and balance sheet strength. The Simply Wall St Screener lets you filter for exactly the traits that matter to you.
- If you are hunting for strong businesses that the market might be overlooking, start with this set of 21 high quality undiscovered gems that combine quality fundamentals with under-the-radar profiles.
- If capital protection and steadier companies matter more to you than excitement, focus on this group of 30 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- If you care about robust finances as a foundation for any long-term position, use this list of solid balance sheet and fundamentals (25 results) to filter for companies with balance sheets that can better handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com