


- Jones Lang LaSalle has reshaped its leadership structure, appointing Mark Gibson as U.S. Country CEO, Kevin MacKenzie as future CEO of Capital Markets Americas, and elevating senior leaders in London offices and global hotels to support its Accelerate 2030 plan and deepen client relationships.
- The creation of a U.S. Executive Committee and a dedicated Global Hotel Desk signals a push to better connect JLL’s data platform, sector specialists, and cross border capital flows across transaction and recurring fee businesses.
- We will now examine how Jones Lang LaSalle’s refreshed leadership, particularly the new U.S. Country CEO role, could influence the company’s investment narrative.
Jones Lang LaSalle Investment Narrative Recap
To own Jones Lang LaSalle, you need to believe its push into higher visibility services, data center work and tech enabled execution can offset choppier capital markets and office exposure. The leadership refresh around a U.S. Country CEO leans into that thesis by trying to pull more of the platform together for each client interaction.
In the near term, the key swing factor remains how transaction heavy revenue holds up if deal volumes soften again, especially in Capital Markets and Leasing. Office related activity and contract churn in Property Management keep earnings sensitivity elevated. The latest appointments do not remove those pressures but could help execution if coordination improves.
The Gibson appointment into the new U.S. Country CEO role looks most relevant for these catalysts. His remit over a U.S. Executive Committee ties directly into using JLL’s data platform and AI tools across services, which matters if you care about operating leverage and the mix shift toward recurring Workplace and Project Management fees.
By keeping Gibson in Capital Markets Americas through 2026 and already naming Kevin MacKenzie as his successor, JLL is trying to avoid disruption in a segment that has benefited from recovered investment sales and proprietary bid and debt tools. That continuity reduces leadership risk around the fee pool that most directly amplifies swings in transaction volumes.
Jones Lang LaSalle's current analyst story points to revenues of $34.4b and earnings of $1.4b by 2029, based on 7.8% yearly revenue growth and an earnings increase of about $400.9m from $999.1m today.
Uncover why Jones Lang LaSalle's fair value indicates a 39% potential upside to its current price before momentum closes the discount.
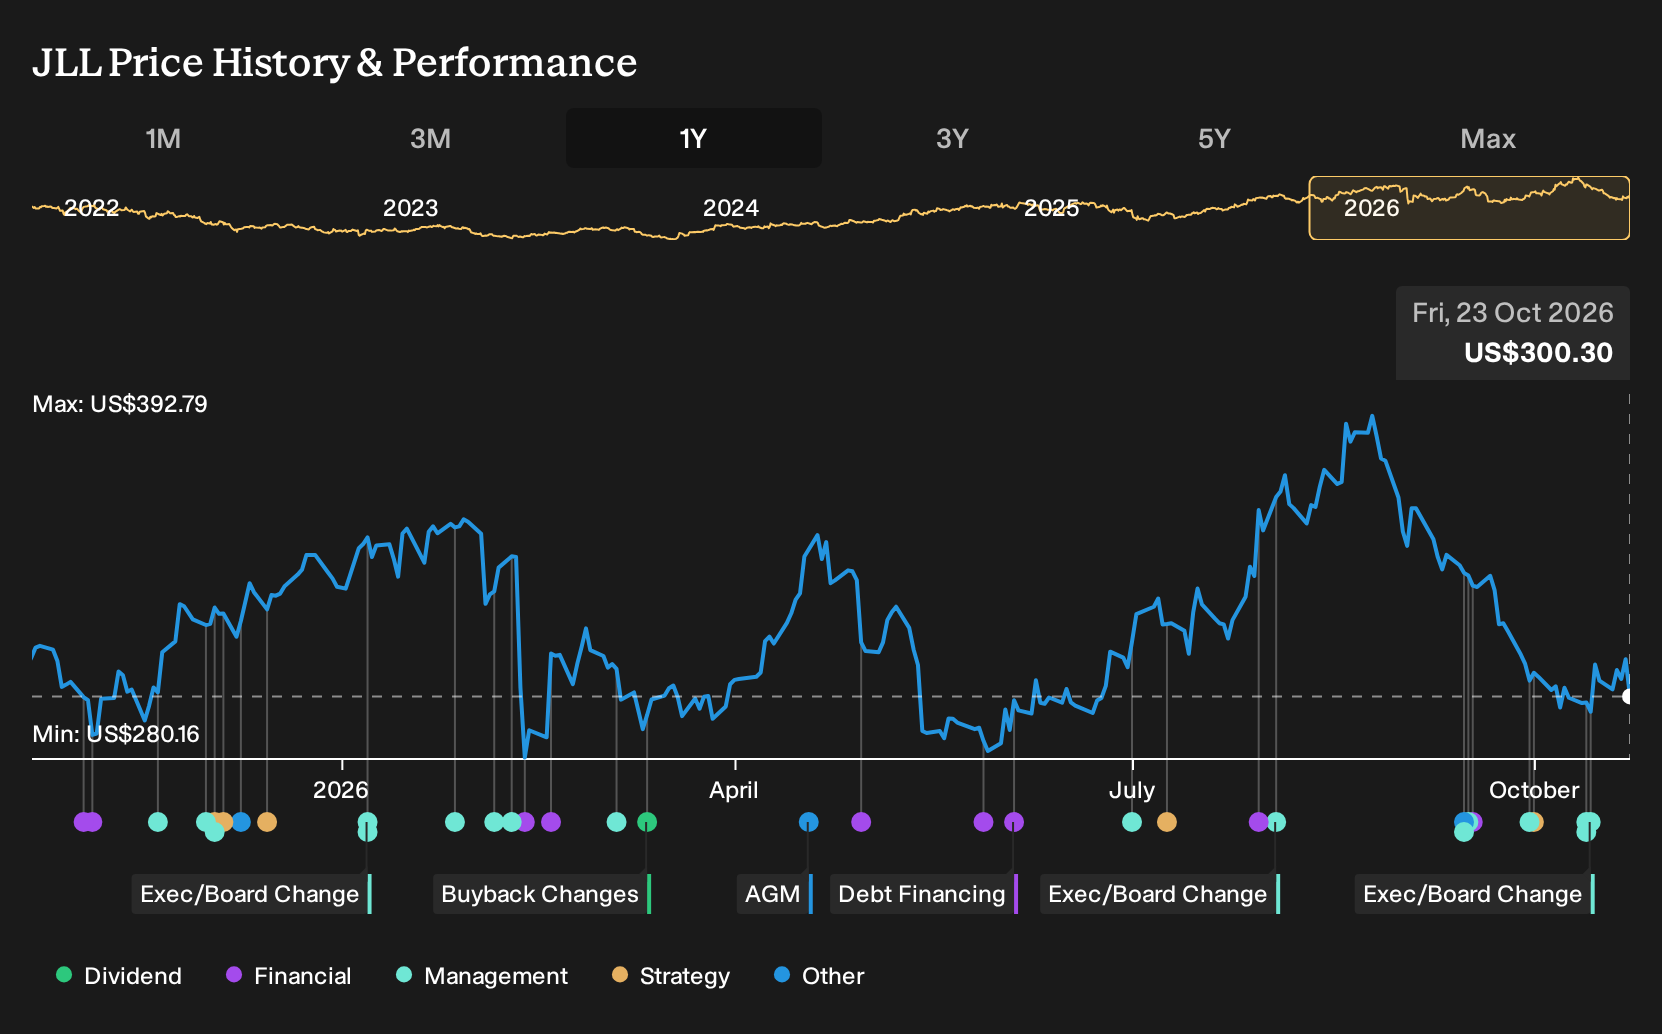
Exploring Other Perspectives
One alternate view puts much more weight on Jones Lang LaSalle’s AI and data platform as a catalyst. Those analysts were already modeling revenue of about $36.1b and earnings near $1.5b by 2029, more optimistic than the baseline. The fresh leadership moves could prompt that camp to revisit, or even stretch, those assumptions further.
Explore 2 other Jones Lang LaSalle fair value estimates, including one that suggests there could be as much as 103% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jones Lang LaSalle research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jones Lang LaSalle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jones Lang LaSalle's overall financial health at a glance.
Looking for more investment ideas beyond Jones Lang LaSalle?
Once the Jones Lang LaSalle story is clear in your mind, it can help to widen the lens and compare it with other potential opportunities that share similar qualities or offer a different risk profile.
- If you want resilient balance sheets and fewer financial surprises, scan our 30 resilient stocks with low risk scores and see which businesses match that profile.
- For investors hunting for mispriced quality, review the 27 high quality undervalued stocks that combine solid fundamentals with more conservative expectations baked into their prices.
- When you care most about financial strength and staying power through different cycles, use the list of solid balance sheet and fundamentals (25 results) as a starting universe before doing deeper research on any single stock.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com