


Williams Companies has delivered a powerful long run for shareholders, and that kind of share price climb naturally puts the focus on what investors are paying for its earnings today. With the stock now in a very different place compared to a few years ago, the question is how well the current multiple lines up with the underlying profit engine.
- Over the past 5 years, Williams Companies has returned 218.0%, which makes it important to ask how much of that move is backed by its earnings power rather than just market enthusiasm for the ticker.
- Recent coverage around fuel market tightness and shifting energy trade routes highlights how a pipeline operator like Williams Companies can see expectations for future cash generation and capital spending recalibrate as flows and pricing change.
- The analysts covering Williams Companies have run their own numbers. See what analysts think Williams Companies's shares could be worth.
The stock's next move may depend on whether Williams Companies' current earnings justify the valuation investors are paying for at today's price.
If you want to pressure test whether Williams Companies' 218.0% five year run lines up with its earnings alongside other opportunities, compare it with 27 high quality undervalued stocks.
Is Williams Companies Getting Expensive on Earnings?
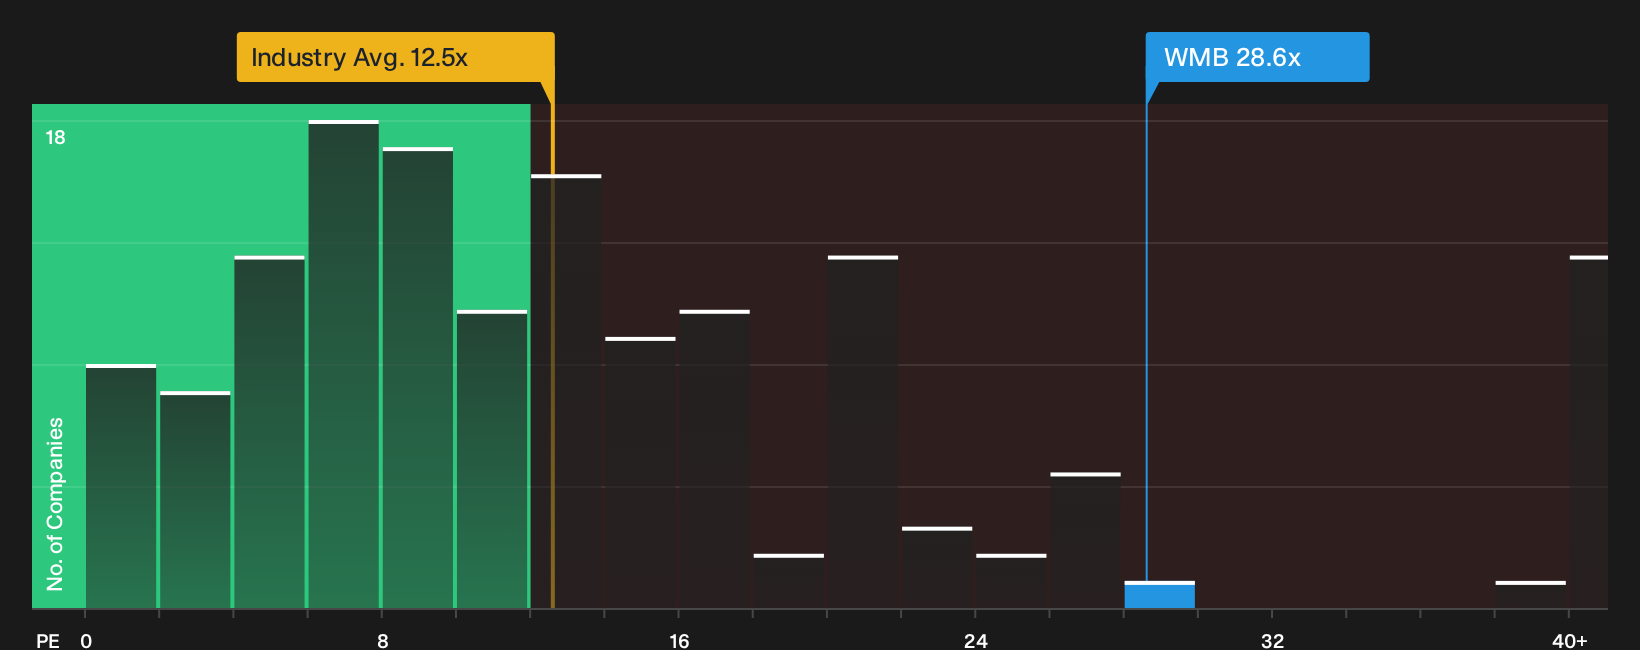
For a mature pipeline operator like Williams Companies, the P/E ratio is a straightforward way to see how much you are paying for each dollar of profit. The stock trades on a P/E of 28.6x, which is materially higher than the Oil and Gas sector average of 12.5x and also above the broader peer group on roughly 15.3x. A tailored fair multiple that adjusts for Williams Companies' margins, risk profile and scale points to a lower figure, so the current earnings valuation screens as overvalued on this framework.
Pipeline stocks have recently lagged in fuel market headlines while tanker operators have grabbed the spotlight. Even so, Williams Companies still carries a premium P/E that already reflects a lot of optimism about its earnings power. That does not mean the shares must fall; it simply indicates that the market is asking you to accept a richer entry multiple than both peers and what the fair value model implies for this business. Explore the numbers behind Williams Companies's P/E valuation.
The Williams Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Williams Companies pick up where the valuation puzzle leaves off and spell out which future paths for earnings, margins and growth would need to play out for the stock to end up meaningfully higher or lower than today’s price. Instead of a single number from a ratio or model, they lay out the underlying story that number rests on so you can see over time whether Williams Companies' actual progress matches the conditions baked into the market view.
One of the top community narratives on Williams Companies: 16% undervalued
"The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects…"
Discover why this Narrative puts Williams Companies at 16% undervalued.
One more Williams Companies check that sits alongside the share price math
The people setting priorities inside Williams Companies, and the way their pay packets line up with long term shareholder outcomes, can matter as much as any P/E chart or model output. See who runs Williams Companies and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com