


How City Holding Stock Has Been Trading Recently
City Holding (CHCO) has been drawing closer attention after a period of steady trading, with the stock last closing at US$142.01. Recent returns over the past week, month, and past 3 months give investors fresh reference points.
Over a longer window, City Holding has been in an upward trend, with an 18.45% year to date share price return and a 19.81% total shareholder return over one year. This suggests that recent weekly softness may reflect short term sentiment shifts rather than a break in longer term momentum.
Scan beyond City Holding and see how it stacks up against a curated 30 resilient stocks with low risk scores with similar resilience in recent returns and financial profiles.
City Holding now trades within a fraction of analyst targets yet screens at an estimated 35% discount to intrinsic value. Is that a pricing anomaly, or is the market flagging real risks?
Price-to-Earnings of 15.3x: Is It Justified For City Holding?
On earnings alone, City Holding trades on a P/E of 15.3x, which leaves the stock on a richer multiple than many US bank peers even though the last close sits at $142.01, only a touch below the $142.40 analyst target.
The P/E ratio compares the share price with per share earnings. For a regional bank like City Holding, it effectively reflects what investors are willing to pay today for each dollar of current profit.
CHCO has factors that can support a premium tag, including high quality earnings, a 40.8% net profit margin, consistent 8.9% annual earnings growth over five years, a seasoned management team with 21.7 years average tenure, and a reliable 2.82% dividend yield. Set against that, earnings are forecast to grow at 1.9% per year, which is slower than the broader US market at 17.2%. Revenue is expected to expand at 3.7% per year, trailing the US market’s 13.5%. Return on equity of 16.3% is below the 20% level often viewed as strong. The estimated fair P/E of 10.3x is materially lower than the current 15.3x, which signals a level the valuation could gravitate toward if expectations cool.
Compared with the US Banks industry average P/E of 11.6x, the 15.3x multiple prices City Holding at a clear premium. Against the peer average of 12.1x the gap is still wide, which suggests investors are paying up considerably relative to both the sector and closer comparables.
Explore the SWS fair ratio for City Holding.
Result: Price-to-Earnings of 15.3x (OVERVALUED)
Still, City Holding could see this premium questioned if earnings growth slows further or if credit quality weakens across its loan book.
Find out about the key risks to this City Holding narrative.
Another View: City Holding And The SWS DCF Model
The P/E workup presents City Holding as expensive, yet the SWS DCF model points in the opposite direction. On that cash flow lens, CHCO at $142.01 sits below an estimated value of $216.96, which frames the shares as undervalued. Which lens do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
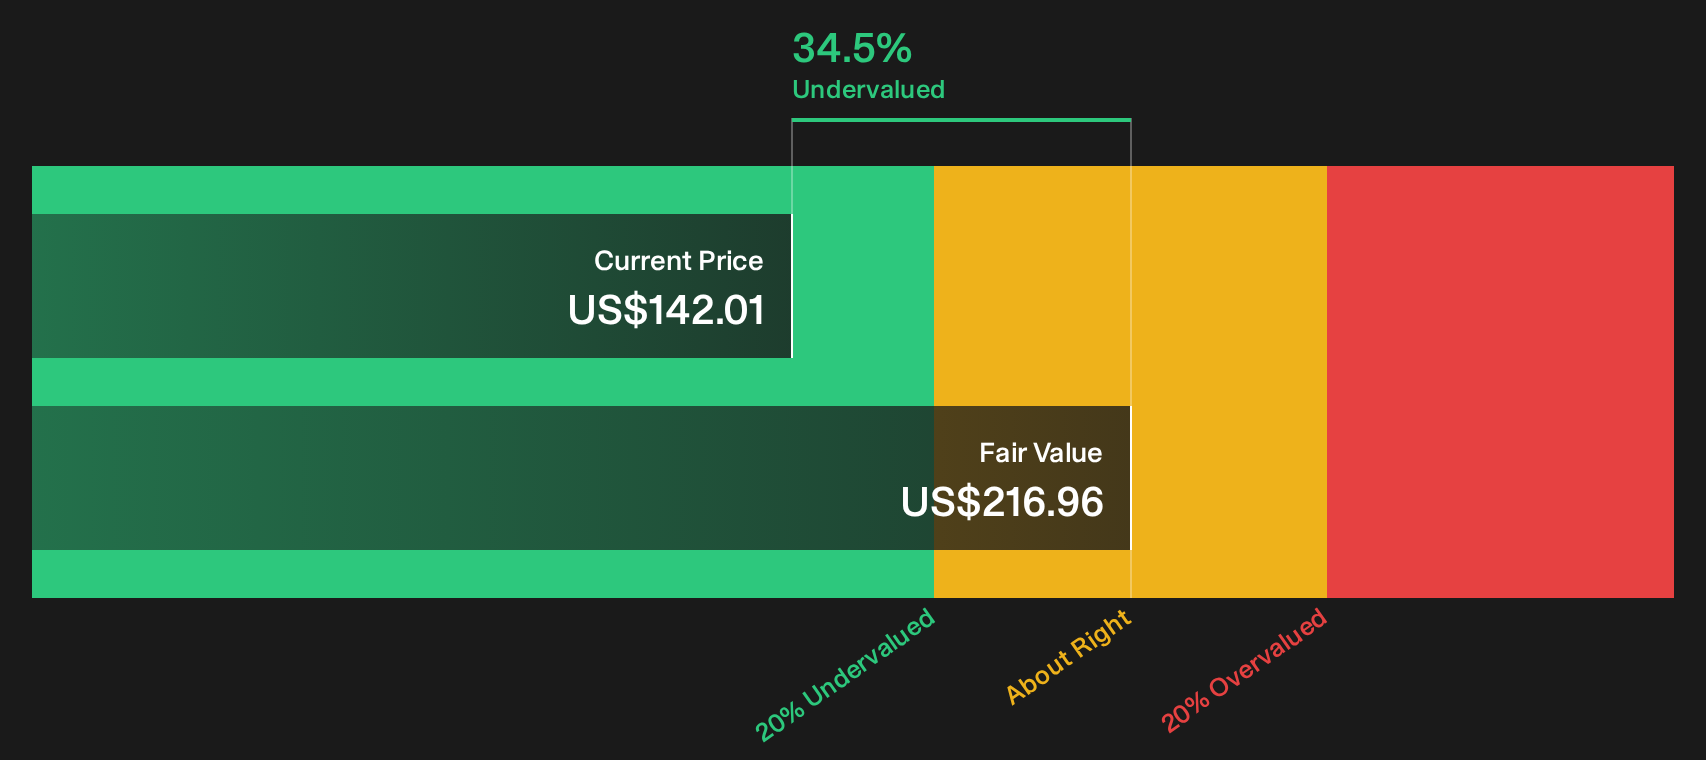
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out City Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on City Holding so far. If you want to move past the headline metrics and closely examine both the potential upside and downside yourself, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond City Holding?
If City Holding has your attention, do not stop there. Broader opportunities emerge when you compare it with other high quality stocks across different return and risk profiles.
- Target potential mispricings and let valuation work for you through a focused set of 27 high quality undervalued stocks that align with stronger fundamentals.
- Strengthen your income stream by reviewing a curated group of 5 dividend fortresses built around higher yields and consistent payout histories.
- Protect your downside by scanning a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com