


Sunshine Insurance Group (SEHK:6963) has moved into focus after recent commentary highlighted its P/E ratio trading below the industry average, prompting investors to reassess how current earnings align with the stock’s depressed valuation.
Recent trading has been choppy. Sunshine Insurance Group’s share price gained 2.73% on the day to HK$3.385, yet the 30 day share price return is down 5.31% and the year to date share price return has declined 14.52%. The 3 year total shareholder return of 5.74% contrasts with a weaker 1 year total shareholder return of 8.74%, pointing to fading momentum recently despite a longer term gain.
Spot opportunities across the sector by comparing Sunshine Insurance Group with a curated 192 high quality undervalued stocks that share solid fundamentals and trade at compressed valuation multiples.Bulls see Sunshine Insurance Group as a mispriced insurer with solid earnings, while bears worry the low P/E flags deeper risks. Which story do the current valuation numbers actually support?
Price-to-Earnings of 4.4x: Is it justified?
On the numbers alone, Sunshine Insurance Group looks cheap, with a P/E of 4.4x at a last close of HK$3.385 and multiple-based metrics pointing to an undervalued insurance stock compared with peers.
The P/E ratio compares what investors are paying today for each unit of earnings. For an insurer like Sunshine Insurance Group, this measure often reflects how the market weighs underwriting quality, the stability of profits, and the perceived risk in the balance sheet.
Here, the market is assigning a P/E of 4.4x, while the Asian insurance peer average sits at 10.4x based on the provided data. That is a steep gap and signals that current earnings are being priced much more conservatively. The fair P/E estimate of 5.7x is also higher than the actual figure, which suggests the current multiple is below a level the market could reasonably move toward if sentiment or perceived risk changes.
Explore the SWS fair ratio for Sunshine Insurance Group.
Result: Price-to-Earnings of 4.4x (UNDERVALUED)
Investors who want to extend this type of valuation work across the wider market and compare Sunshine Insurance Group with other stocks trading on compressed earnings multiples can review a focused screener of companies with solid fundamentals using the 192 high quality undervalued stocks.
Still, the recent 1 year total shareholder return decline of 8.74% and the 14.52% fall year to date suggest sentiment on Sunshine Insurance Group can worsen further if earnings or capital quality disappoint.
Find out about the key risks to this Sunshine Insurance Group narrative.
Another view using the SWS DCF model
The low P/E hints at value, but the SWS DCF model paints an even starker picture. At a share price of HK$3.385, Sunshine Insurance Group is indicated as trading well below an estimated future cash flow value of HK$13.73, which also signals undervaluation. That kind of gap raises a different question: Is the market misreading the cash flow story, or are the DCF assumptions too generous?
Look into how the SWS DCF model arrives at its fair value.
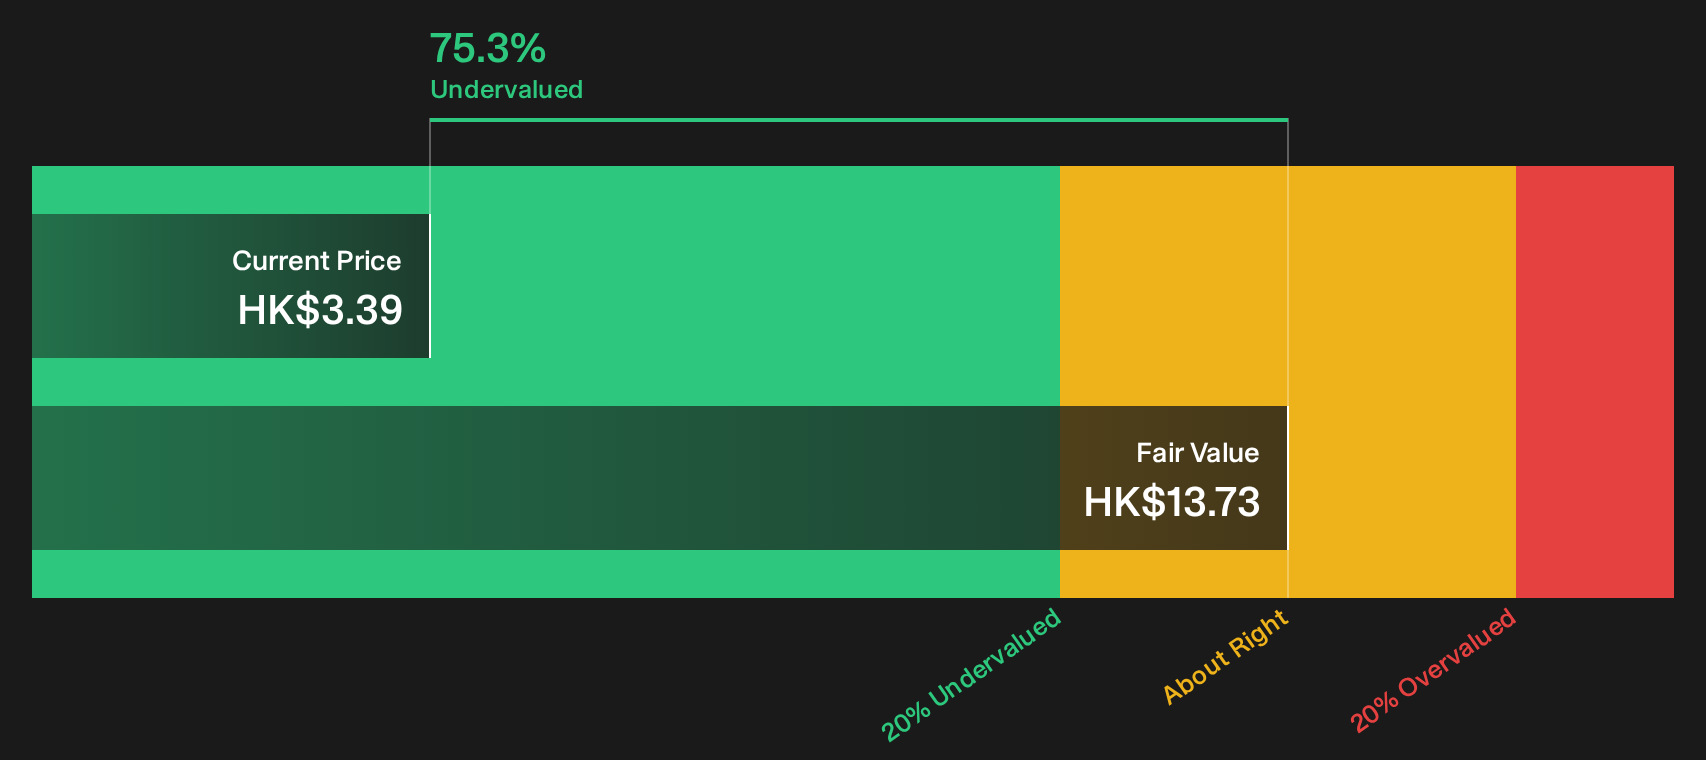
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sunshine Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Market sentiment around Sunshine Insurance Group is mixed, which is exactly when it pays to check the numbers yourself and decide how comfortable you are with the risk reward trade off. To stress test your own view against the bullish angles, review the 4 key rewards.
Looking for more investment ideas beyond Sunshine Insurance Group?
Do not leave your next move to chance. Use the Simply Wall St screener to surface fresh ideas that match your risk tolerance and return goals.
- Target potential mispricing by scanning a curated set of value opportunities with the 192 high quality undervalued stocks that combine compressed valuations with stronger fundamentals.
- Protect your capital by focusing on stability first and filter for companies on the 221 resilient stocks with low risk scores that score well on financial strength and volatility.
- Hunt for potential future leaders before the crowd pays attention by reviewing the 612 high quality undiscovered gems with quality fundamentals and less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com