


Amerant Bancorp (AMTB) just combined a stronger third quarter earnings report with a fresh US$50 million share repurchase authorization, drawing investor focus to how management is using excess capital.
Amerant Bancorp’s recent earnings beat, dividend affirmation and expanded buyback plan have arrived after a strong run, with the year-to-date share price return of 52.51% and a 1-year total shareholder return of 73.97% suggesting that momentum has been building rather than fading.
Compare Amerant Bancorp’s momentum and capital returns with a hand picked set of bank stocks in the 30 resilient stocks with low risk scores that aim to keep balance sheet risk in check.
After Amerant Bancorp’s sharp rerating on stronger earnings and a larger buyback pool, the live question is whether the real upside sits ahead or if investors already captured most of it. The valuation work starts from that point.
Most Popular Narrative: 6% Undervalued
Amerant Bancorp’s most followed narrative pegs fair value at about $31.88, slightly above the latest $30.06 close. This places the recent share price surge against a still constructive valuation anchor that focuses on funding, costs and credit quality rather than sheer loan growth.
Previously the focus was on loan growth and physical expansion to lift revenue and NII. Now the emphasis is on a cleaner balance sheet, more granular underwriting and lower criticized credits to support steadier credit costs and earnings.
See why 0 investors see Amerant Bancorp as 6% undervalued.
Result: Fair Value of $31.88 (UNDERVALUED)
Still, cracks in the story can appear if credit issues resurface or if net interest margin pressure on Amerant Bancorp proves more persistent than analysts assume.
Find out about the key risks to this Amerant Bancorp narrative.
Another View On Amerant Bancorp’s Valuation
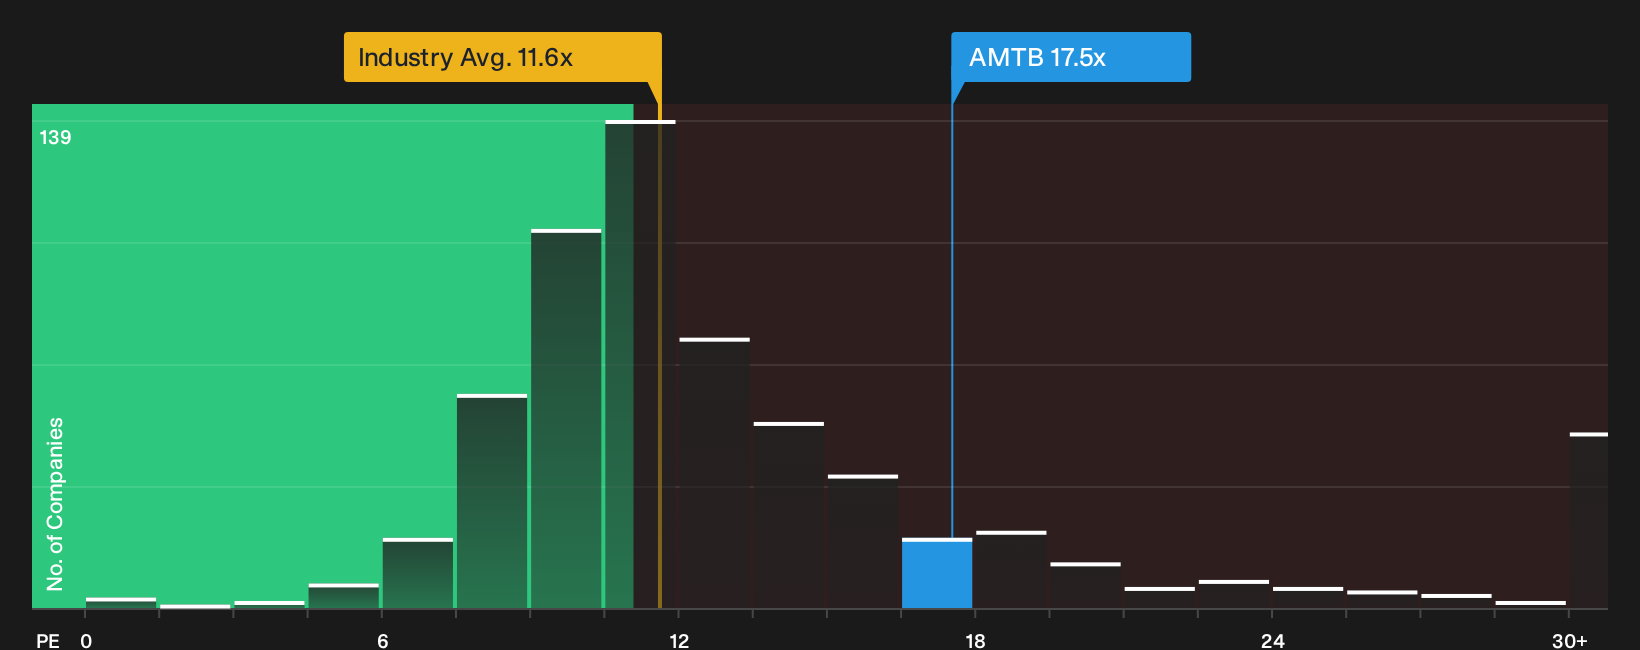
The analyst narrative frames Amerant Bancorp as about 6% undervalued at a fair value of $31.88, yet the market is already paying a P/E of 17.5x. That is well above the US Banks industry at 11.6x, the peer group at 10.8x and a fair ratio of 15.1x that the market could gravitate toward. For investors, that gap points to less room for error on execution. The real question is whether Amerant Bancorp’s earnings path justifies paying a premium multiple for what is otherwise pitched as only modest upside.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Amerant Bancorp is mixed, with risks and rewards both on the table. Move quickly, review the data and weigh the 2 key rewards and 2 important warning signs.
Looking for more Amerant Bancorp investment ideas?
If you want to pressure test your thesis on Amerant Bancorp, widen the lens. Compare it with other opportunities that share strong balance sheets or compelling value angles.
- Target long-term value by weighing Amerant Bancorp against companies in the 27 high quality undervalued stocks that combine robust fundamentals with pricing that still looks appealing.
- Prioritise resilience by cross checking Amerant Bancorp against the list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial strength with consistent execution.
- Spot early stage potential by setting Amerant Bancorp alongside the 7 elite penny stocks with strong financials where smaller companies offer different risk and reward profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com