


Nomura Corporation (TSE:7131) stock is about to trade ex-dividend in three days. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company's books as a shareholder in order to receive the dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Thus, you can purchase Nomura's shares before the 29th of October in order to receive the dividend, which the company will pay on the 28th of January.
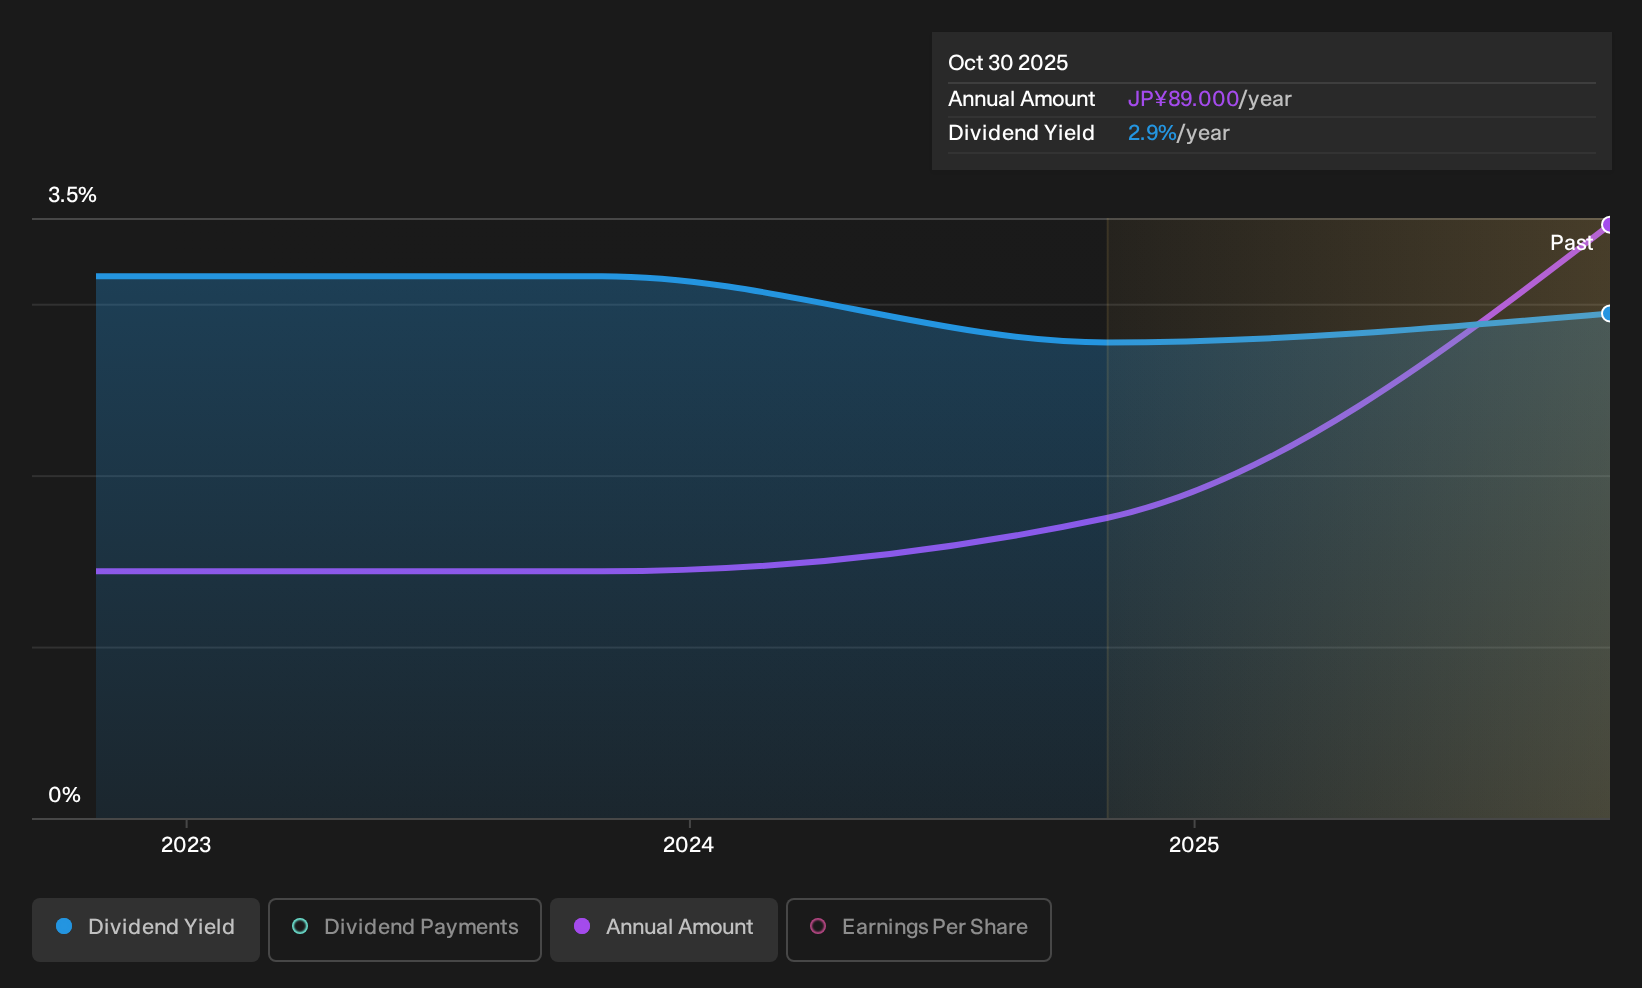
The company's next dividend payment will be JP¥122.00 per share, and in the last 12 months, the company paid a total of JP¥96.00 per share. Based on the last year's worth of payments, Nomura has a trailing yield of 2.6% on the current stock price of JP¥3665.00. Dividends are a major contributor to investment returns for long term holders, but only if the dividend continues to be paid. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Nomura is paying out just 16% of its profit after tax, which is comfortably low and leaves plenty of breathing room in the case of adverse events. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. What's good is that dividends were well covered by free cash flow, with the company paying out 11% of its cash flow last year.
It's positive to see that Nomura's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
View our latest analysis for Nomura
Click here to see how much of its profit Nomura paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Stocks in companies that generate sustainable earnings growth often make the best dividend prospects, as it is easier to lift the dividend when earnings are rising. If earnings fall far enough, the company could be forced to cut its dividend. It's encouraging to see Nomura has grown its earnings rapidly, up 70% a year for the past five years. With earnings per share growing rapidly and the company sensibly reinvesting almost all of its profits within the business, Nomura looks like a promising growth company.
Another key way to measure a company's dividend prospects is by measuring its historical rate of dividend growth. In the past five years, Nomura has increased its dividend at approximately 21% a year on average. It's exciting to see that both earnings and dividends per share have grown rapidly over the past few years.
To Sum It Up
From a dividend perspective, should investors buy or avoid Nomura? Nomura has been growing earnings at a rapid rate, and has a conservatively low payout ratio, implying that it is reinvesting heavily in its business; a sterling combination. Overall we think this is an attractive combination and worthy of further research.
With that in mind, a critical part of thorough stock research is being aware of any risks that stock currently faces. For example, we've found 1 warning sign for Nomura that we recommend you consider before investing in the business.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.