


- Sartorius reported third quarter 2026 sales of €926.3 million and net income of €66.1 million, alongside confirmed and refined 2026 guidance that reflects tariff related revenue headwinds of up to €40 million.
- The group is pairing this earnings update with a shift to Bioprocessing Solutions and Research Solutions segments and refreshed Executive Board roles that consolidate commercial and product responsibilities under a One Sartorius operating model from 2027.
- Now the focus shifts to how Sartorius’s refined 2026 guidance, together with its new operating structure, reshapes the broader investment narrative.
What Is Sartorius' Investment Narrative?
Sartorius appeals to shareholders who support a long term build out of tools for biopharmaceutical production and lab research, even if the stock is not cheap on P/E and returns on equity are still modest. The shift to Bioprocessing Solutions and Research Solutions and the One Sartorius model is mainly about cleaner execution. Investors are being asked to believe management can sharpen focus on product development and global sales without disrupting a complex, capital intensive manufacturing base.
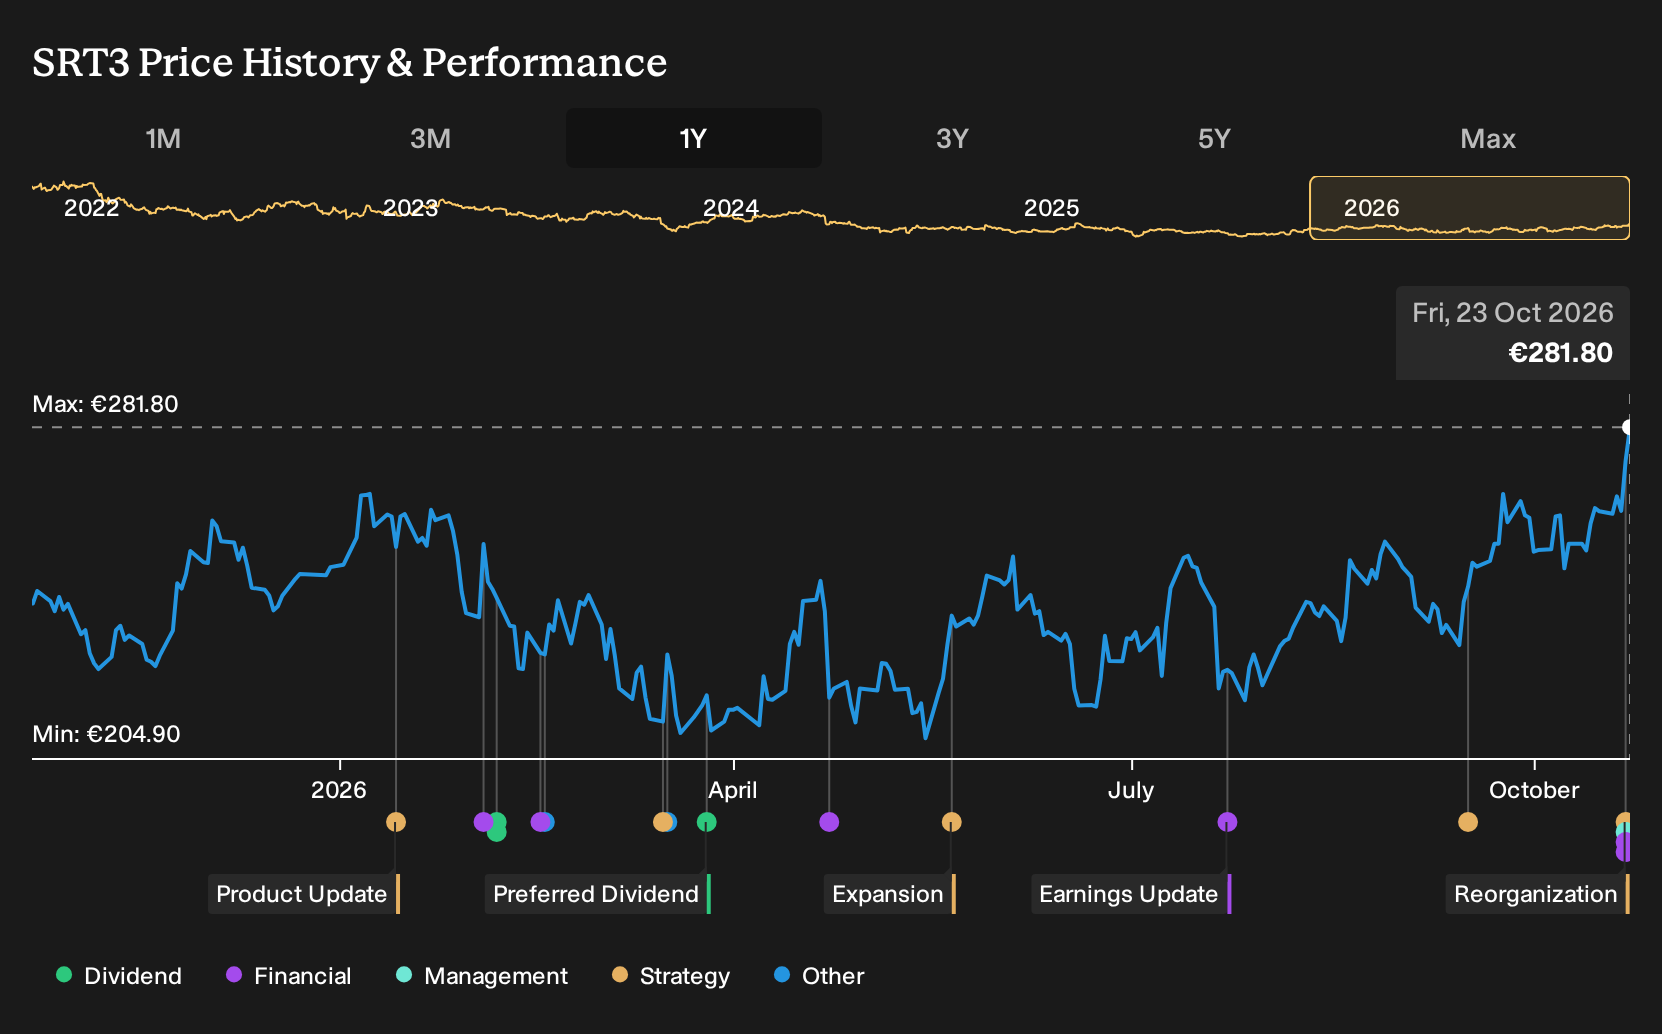
In the short term, the refined 2026 outlook and up to €40 million tariff hit keep attention on demand resilience, pricing discipline and how much operational headroom Sartorius has if conditions stay choppy. The recent share price rebound and strong year on year earnings in the latest quarter give management some flexibility. Debt levels and external funding reliance mean missteps on this reorganisation or on cash generation could matter quickly.
That said, alongside the cleaner story there is a more uncomfortable angle investors may need to examine more closely...
There's only one way to know the right time to buy, sell or hold Sartorius. Head to Simply Wall St's company report for the latest analysis of Sartorius's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sartorius research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sartorius. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sartorius' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sartorius?
If this Sartorius update has sharpened your thinking and you want to line it up against other potential opportunities, the Simply Wall St Screener can help you quickly filter for businesses that better match your risk, income, or value preferences.
- If capital preservation sits high on your priority list, you can focus on companies that pair resilient earnings with steadier balance sheets by reviewing a 222 resilient stocks with low risk scores.
- For readers who care most about paying a reasonable price for quality, you can use the screener to concentrate on companies trading below their estimated worth through a 196 high quality undervalued stocks.
- If you prefer cash returns while you wait, you can target higher yielding payers with a history of distributions by scanning a 225 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com