


Waste Connections (WCN) just paired a Q3 earnings beat with a higher full year revenue outlook and a 10% dividend hike, giving investors fresh numbers to reassess the waste services stock.
At a share price of $186.6, Waste Connections has seen momentum pick up recently, with an 11.14% 7 day share price return and a 19.95% 30 day share price return as investors reacted to the Q3 beat, higher full year revenue guidance and the 10% dividend increase.
See how Waste Connections compares with a hand picked group of resilient peers using the 30 resilient stocks with low risk scores, which screens for companies with stronger balance sheets and lower risk scores.
The Q3 beat, higher guidance and dividend hike have pushed Waste Connections closer to analyst targets, yet a discount to both those targets and some intrinsic value estimates remains. Is the market’s caution still warranted here?
Most Popular Narrative: 5.5% Undervalued
Against the last close at $186.60, the most followed narrative pegs Waste Connections’ fair value at $197.40, pointing to a modest valuation gap that hinges on how well the business turns current projects into future cash.
Waste Connections is investing about $100 million across seven AI and digital projects. Management expects these projects to deliver about 100 basis points of EBITDA margin uplift as they fully roll through 2028 and 2029. Several of these initiatives, such as routing and customer service tools, are still in pilot or early deployment and will take years to reach scale. If execution issues, slower adoption in the field or weaker than expected savings mean these tools do not deliver the anticipated $100 million of EBITDA benefit, the margin improvement and earnings profile that many analysts are underwriting into valuation work could fall short of expectations.
See why 19 investors see Waste Connections as 5% undervalued.
Result: Fair Value of $197.40 (UNDERVALUED)
Still, the Waste Connections narrative can crack if Chiquita cash outflows run above plan or if fuel and diesel costs keep squeezing profitability longer than analysts model.
Find out about the key risks to this Waste Connections narrative.
Another View: What Waste Connections’ P/E Is Telling You
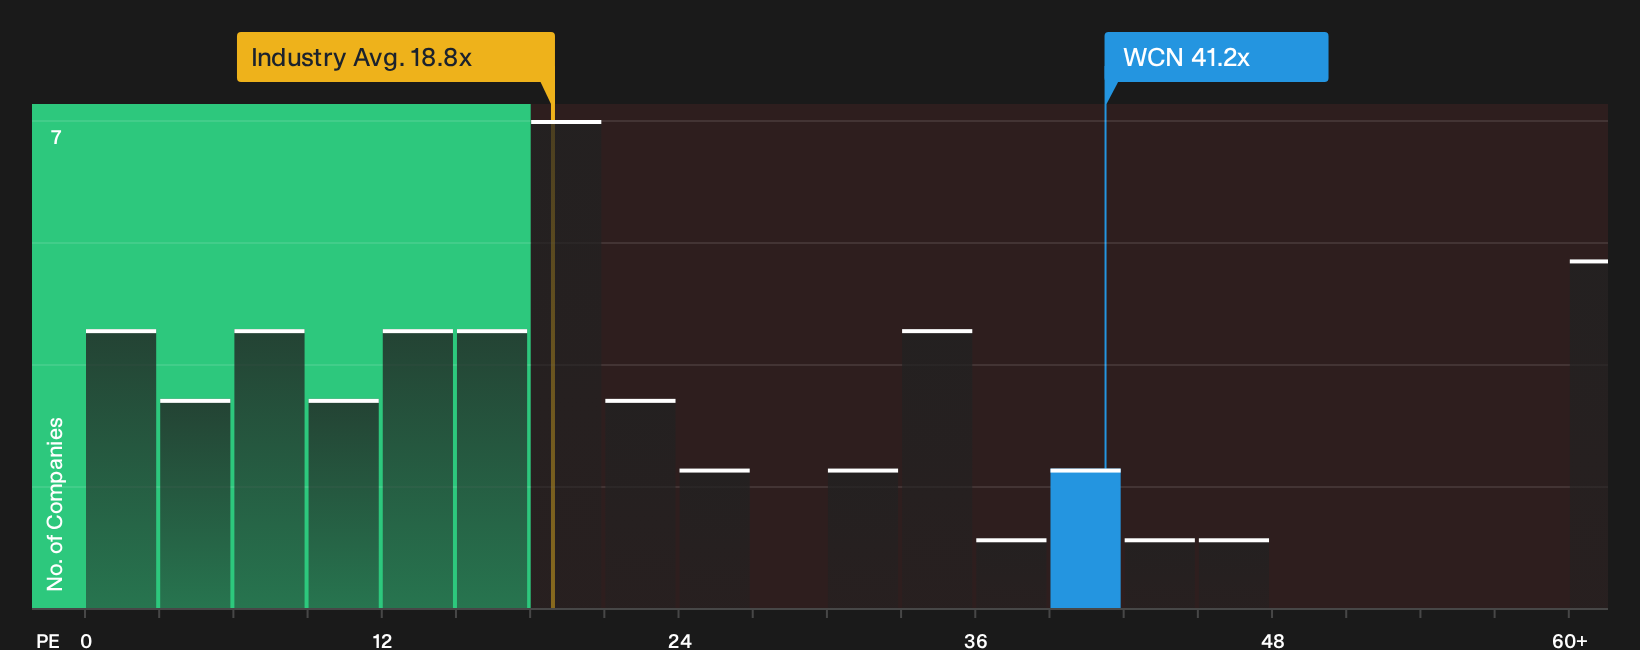
The first narrative leans on future cash flows and points to Waste Connections trading at a discount to fair value. The simple P/E comparison paints a tougher picture. At 41.2x earnings, the stock sits well above its own fair ratio of 25.7x, the peer average of 31.2x and the US Commercial Services industry on 18.8x. That kind of premium can be read as confidence in durable earnings, or as valuation risk if growth or margins fall short. Which side of that trade off feels more realistic to you?
Before leaning too hard on any one set of multiples, it helps to see how the detailed valuation stack fits together in context, including cash flow and quality metrics, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals run through this Waste Connections story, with valuation questions sitting beside both red flags and bright spots in the data. If you want to move quickly and base your decision on more than headlines, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more Waste Connections style ideas?
If you only stop at Waste Connections, you risk missing other opportunities that match your goals, risk comfort and income needs across the market.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that filters for financially robust businesses trading below their assessed worth.
- Lock in potential income streams with the 5 dividend fortresses to spot companies combining higher yields with resilient payout histories.
- Prioritize resilience first and check the list of solid balance sheet and fundamentals (24 results) to focus on businesses with sturdy finances that can better handle shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com