


- HP disclosed that Infinity.inc used its Auto Research platform to tune the NVIDIA Nemotron 3 Super model on the HP ZGX Fury AI workstation, doubling concurrent workloads and overall token throughput on NVIDIA GB300 hardware without altering the underlying configuration.
- The speed of Infinity.inc’s first gains, produced in under 24 hours of engineering effort, highlights how HP’s AI focused workstations could attract developers who want more performance from existing hardware rather than higher capital spending.
- Next, the focus shifts to how this HP and Infinity.inc throughput optimization on ZGX Fury might reshape the broader investment narrative.
Scan the HP ZGX Fury story for clues, then compare it with hand-picked AI infrastructure plays screened as 55 AI infrastructure stocks to see where similar throughput gains might already be priced in.
HP Investment Narrative Recap
To own HP, you need to believe the shift toward AI capable PCs, richer configurations and higher value services can keep earnings resilient even as traditional PC and print markets stay mature. The Infinity.inc work on ZGX Fury fits that story because it points to higher performance per dollar on HP’s premium AI hardware rather than just bigger spend.
In the near term, the key swing factor is whether AI PCs, premium devices and cost savings actually support margins while HP carries high debt and negative shareholder equity. The ZGX Fury momentum helps the narrative, but the bigger risk still sits with execution on mix, pricing and the multiyear efficiency plan.
Recent commentary around AI PCs reaching 46% of HP’s shipment mix and a target of 60 to 70% by 2027 lines up directly with the ZGX Fury work. If buyers see concrete throughput gains on HP workstations, that can support the case for paying up for AI capable devices instead of chasing lower cost PCs.
The same applies to HP’s push into more recurring, service led revenue like Device as a Service and the Workforce Experience Platform. ZGX Fury and AI tuned workloads give those offerings a higher end hardware anchor, while the main watchpoints remain input cost pressure, the pace of mix shift and whether industrial and 3D print can keep offsetting supplies headwinds.
HP's outlook anticipates US$63.2b in revenue and US$3.0b in earnings by 2029. This is based on an assumption of 2.2% annual revenue growth and an increase in earnings of about US$0.5b from US$2.5b today.
Uncover how HP's fair value indicates a 19% potential downside to its current price, suggesting a premium that may not leave much room for error.
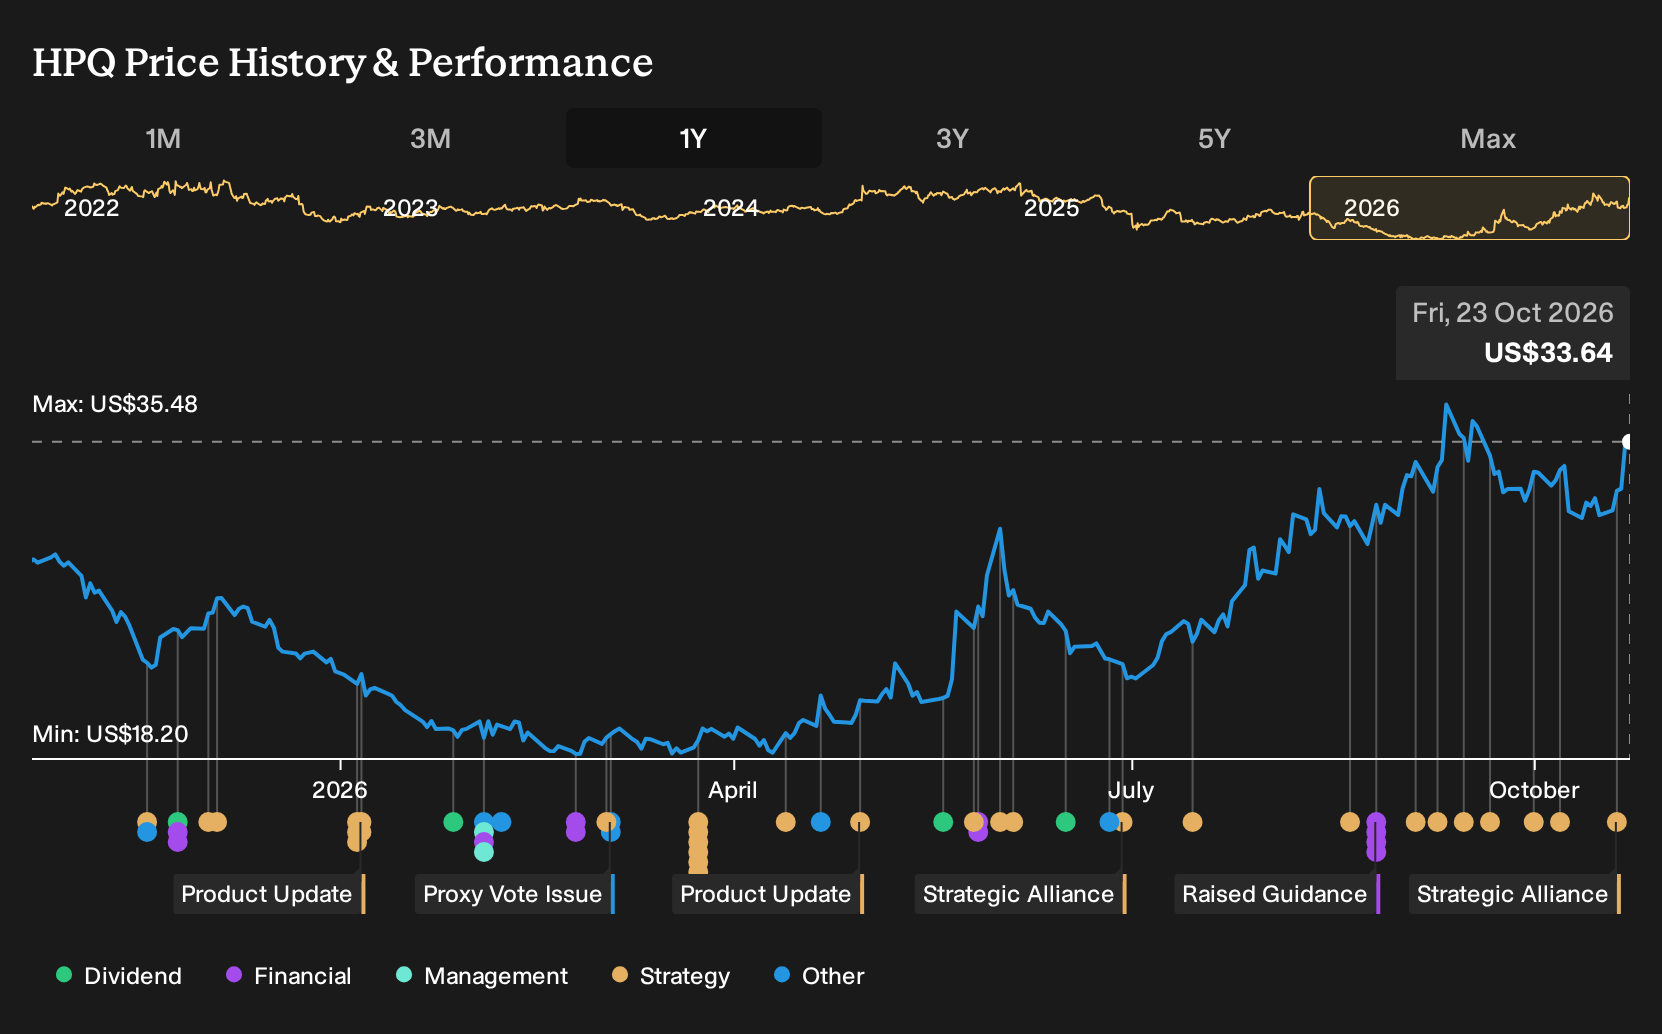
Exploring Other Perspectives
One bearish angle on HP focuses on AI at the edge not scaling. The lowest analysts were modelling revenue at about US$56.0b and earnings of US$2.7b by 2029, which is well below the consensus path. Those forecasts came before this Infinity.inc throughput work, so you may see those narratives shift as views update.
Explore 5 other HP fair value estimates, including one that suggests as much as 44% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so focus on independent analysis.
- A great starting point for your HP research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HP's overall financial health at a glance.
Looking for more HP-sized investment ideas?
If the HP ZGX Fury story has you thinking about where else throughput, balance sheet strength or income potential might be underappreciated, it can help to widen the lens and scan a broader set of companies using the Simply Wall St Screener.
- For investors who care most about quality at a reasonable entry point, start with a 29 high quality undervalued stocks that already score well on fundamentals.
- If capital preservation is a priority, narrow your search to a 30 resilient stocks with low risk scores that might offer a smoother ride through market swings.
- When you want exposure to sturdier finances and cleaner accounts, filter for a list of solid balance sheet and fundamentals (24 results) so you can focus your time on businesses with stronger footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com