


Becton Dickinson (BDX) is back in focus after a new U.S. manufacturing agreement and execution updates ahead of its upcoming fourth quarter fiscal 2026 earnings report drew fresh attention to the stock.
The fresh U.S. manufacturing agreement and execution progress come on top of a strong run in Becton Dickinson’s shares, with the 90-day share price return of 25.16% and 1-year total shareholder return of 39.61%. Investors appear to be treating this as momentum that is building rather than fading.
Scan other healthcare and medtech stocks that are showing strong execution and fresh contract momentum with our hand picked 34 healthcare AI stocks to compare them with Becton Dickinson’s latest moves.
Becton Dickinson has already moved sharply on contract news and execution updates. The real tension is simple: Is it worth paying up now, or does patience for a cheaper entry make more sense once valuation is on the table?
Most Popular Narrative: 2% Overvalued
Becton Dickinson closed at $198.91, modestly above the most widely followed narrative fair value of about $195.67. This frames the recent contract momentum against an already full long term outlook.
The ongoing shift toward a focused medtech portfolio, where more than 90% of revenue comes from businesses growing in the mid to high single digits and key platforms like biologic drug delivery, Advanced Patient Monitoring, PureWick and advanced tissue regeneration grow at double digits with higher gross margins than the corporate average, supports a richer margin mix and provides a base for revenue and earnings growth.
See why 28 investors see Becton Dickinson as 2% overvalued.
Result: Fair Value of $195.67 (OVERVALUED)
Still, pressure in China, along with any fresh product quality or regulatory setbacks, could quickly challenge the case for Becton Dickinson’s current valuation premium.
Find out about the key risks to this Becton Dickinson narrative.
Another View: DCF Points To Undervaluation
The first lens on Becton Dickinson framed the shares as about 2% above a $195.67 fair value. A different tool, the SWS DCF model, values future cash flows at $234.50 per share while the stock trades at $198.91. That gap suggests a built in discount rather than a premium. Which perspective do you find more compelling?
For a closer look at how those projected cash flows translate into that $234.50 figure, and what would need to change for the estimate to move meaningfully, Look into how the SWS DCF model arrives at its fair value.
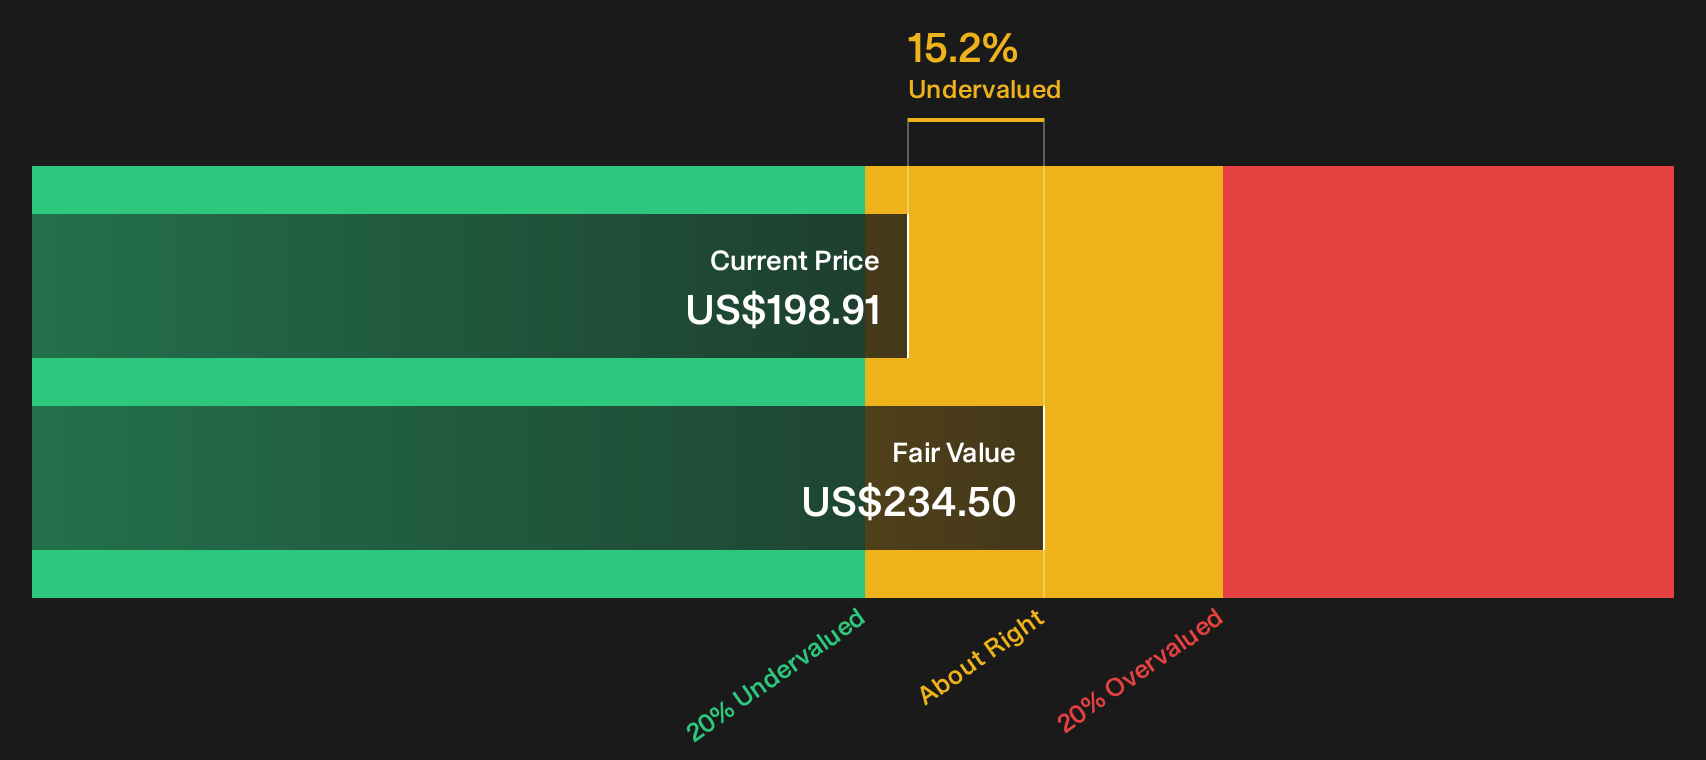
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Becton Dickinson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Becton Dickinson’s valuation and outlook can be useful, as long as you pressure test them yourself and move quickly while the data still feels fresh. To weigh the upside against the concerns in one place, start with 4 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Becton Dickinson?
If Becton Dickinson has your attention, the next smart move is lining up a few alternative ideas so you are not relying on a single story.
- Target resilient opportunities with strong balance sheets and solid fundamentals using our curated list of solid balance sheet and fundamentals (24 results) before the crowd catches on.
- Lock onto potential value candidates by scanning 29 high quality undervalued stocks that currently trade below their assessed worth based on underlying financial strength.
- Boost your income focus by reviewing 5 dividend fortresses that combine higher yields with business profiles built around consistent shareholder payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com