


- American Airlines Group reported third quarter 2026 revenue of US$16.3b and nine month revenue of US$47.0b, yet posted wider losses as higher fuel expenses and other costs outweighed demand strength and premium-focused initiatives.
- The carrier is slowing capacity growth, concentrating on higher margin international and premium segments, and leaning on its expanding AAdvantage loyalty program and new 10 year Citi co-branded card agreement to support more durable revenue streams over time.
- The next area of focus will be how American Airlines Group's investment narrative is affected by strong sales alongside continued pressure from fuel costs.
Compare how American Airlines Group’s fuel pressured earnings story stacks up against other carriers and capital intensive businesses in our hand picked 30 resilient stocks with low risk scores for a different risk profile.
American Airlines Group Investment Narrative Recap
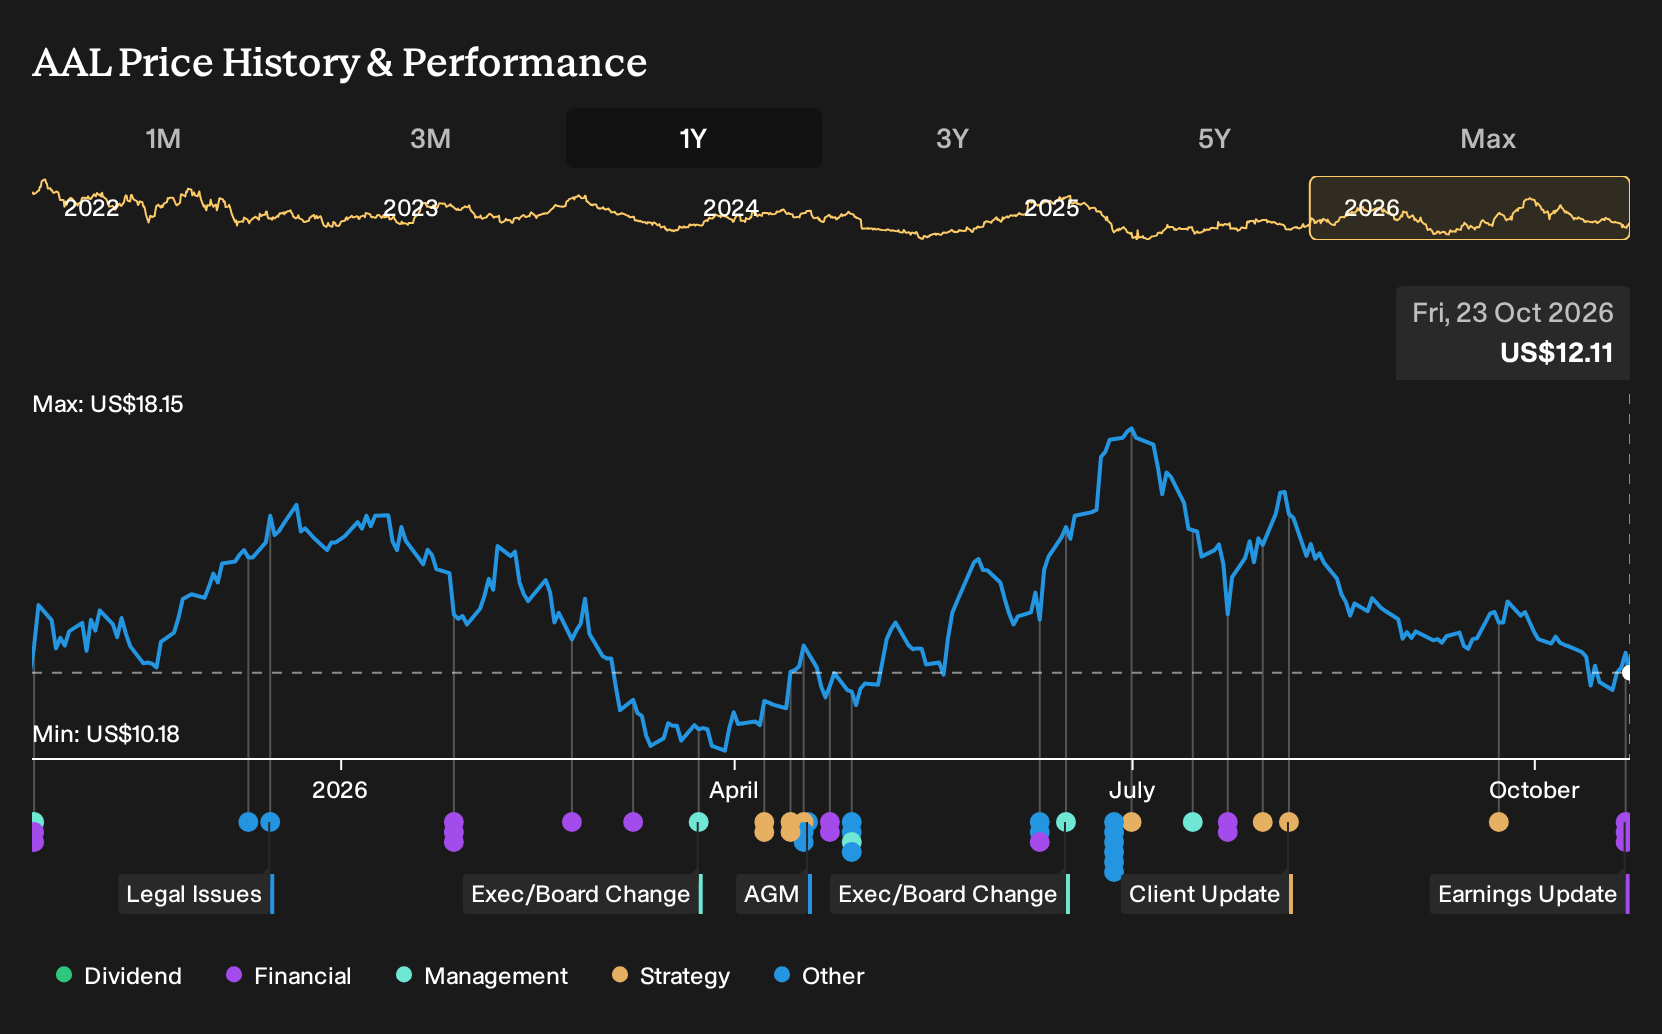
To own American Airlines Group, you need to be comfortable with a simple trade off. The story is about strong demand, especially in premium and international cabins, offset by a cost base that is heavily exposed to fuel and labor. Recent results underline that tension, with record Q3 revenue alongside a US$269 million loss and pressure on load factor.
The near term hinge is whether the business can convert this higher revenue into meaningful profitability as capacity growth is slowed. Fuel remains the biggest swing factor right now, with higher prices feeding directly into a wider nine month loss of US$580 million and keeping leverage and interest coverage key watchpoints.
The most relevant new data point is American Airlines Group’s Q4 2026 outlook for total revenue growth of 19.5% to 22.5%, paired with planned capacity growth of 5.5% to 6.5% in available seat miles. This guidance keeps the focus firmly on revenue quality per seat rather than just flying more volume.
For you, that means the catalyst to watch is execution on premium and international yield while that slower capacity plan is in place. If fuel costs remain elevated, the risk is that even double digit top line growth does not translate into healthier margins, which matters given the sizeable net debt and high interest burden already flagged by analysts.
American Airlines Group's narrative projects US$68.9b revenue and US$1.8b earnings by 2029. This assumes 5.7% yearly revenue growth and an earnings swing of about US$2.1b from earnings today of a US$326.0m loss.
Uncover why American Airlines Group's fair value indicates a 32% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
Fuel risk is the big swing factor. Bearish analysts focus almost entirely on that. Before this Q3 2026 update, the lowest forecasts only pencilled in about 2.2% yearly revenue growth to roughly US$62.4b by 2029 and still just US$1.8b of earnings. That is a much harsher American Airlines Group story. Use it as a foil and compare several viewpoints, because this new fuel hit and guidance could push those bearish cases to shift again.
Explore 6 other American Airlines Group fair value estimates, including one that suggests up to 15% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Airlines Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Airlines Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Airlines Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Airlines Group?
If the American Airlines Group story has you thinking about risk, balance sheets, and where you want volatility in your portfolio, it can help to line it up against very different business profiles using the Simply Wall St Screener.
- For investors who want potential upside without taking on extreme balance sheet stress, consider a curated 21 high quality undiscovered gems that pair strong fundamentals with lower market attention.
- If durability and financial resilience are a priority, compare American Airlines Group with a list of solid balance sheet and fundamentals (24 results) that could handle shocks very differently to a highly leveraged carrier.
- For those who care most about capital preservation and smoother return profiles, focus on a 30 resilient stocks with low risk scores that filters for companies with more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com