


Kimbell Royalty Partners (KRP) has set up a major capital move. The partnership plans to redeem 81,250 Series A Cumulative Convertible Preferred Units on November 16, 2026 for about US$100.2 million.
That redemption notice comes after a strong run for Kimbell Royalty Partners, with a 1-month share price return of 16.4% and a year-to-date share price gain of 41%, supported by growth-focused deals and richer distributions that have produced a 5-year total shareholder return of 91.6%.
Scan for other energy income plays showing similar momentum and capital moves by reviewing the curated 5 dividend fortresses alongside Kimbell Royalty Partners.
Kimbell Royalty Partners now trades below both analyst targets and some intrinsic value estimates after this preferred redemption move, so where does a fair entry point really lie once those gaps are lined up?
Most Popular Narrative: 12% Undervalued
The most followed narrative on Kimbell Royalty Partners pegs fair value at $19.20 against a last close of $16.96, which points to a discount that rests on how credibly management can keep compounding deal driven cash flows.
The capital allocation framework that directs 75% of cash available for distribution to unitholders, uses 25% for debt reduction and funds unit repurchases under the US$100 million program is expected to support distributable cash flow per unit and earnings through a mix of payouts, lower interest expense and a smaller unit count.
See why 16 investors see Kimbell Royalty Partners as 12% undervalued.
Result: Fair Value of $19.20 (UNDERVALUED)
Still, the story can break if competition keeps pushing royalty deal prices higher, or if weaker drilling activity cuts into Kimbell Royalty Partners production linked income.
Find out about the key risks to this Kimbell Royalty Partners narrative.
Another View: What The P/E Ratio Says About Kimbell Royalty Partners
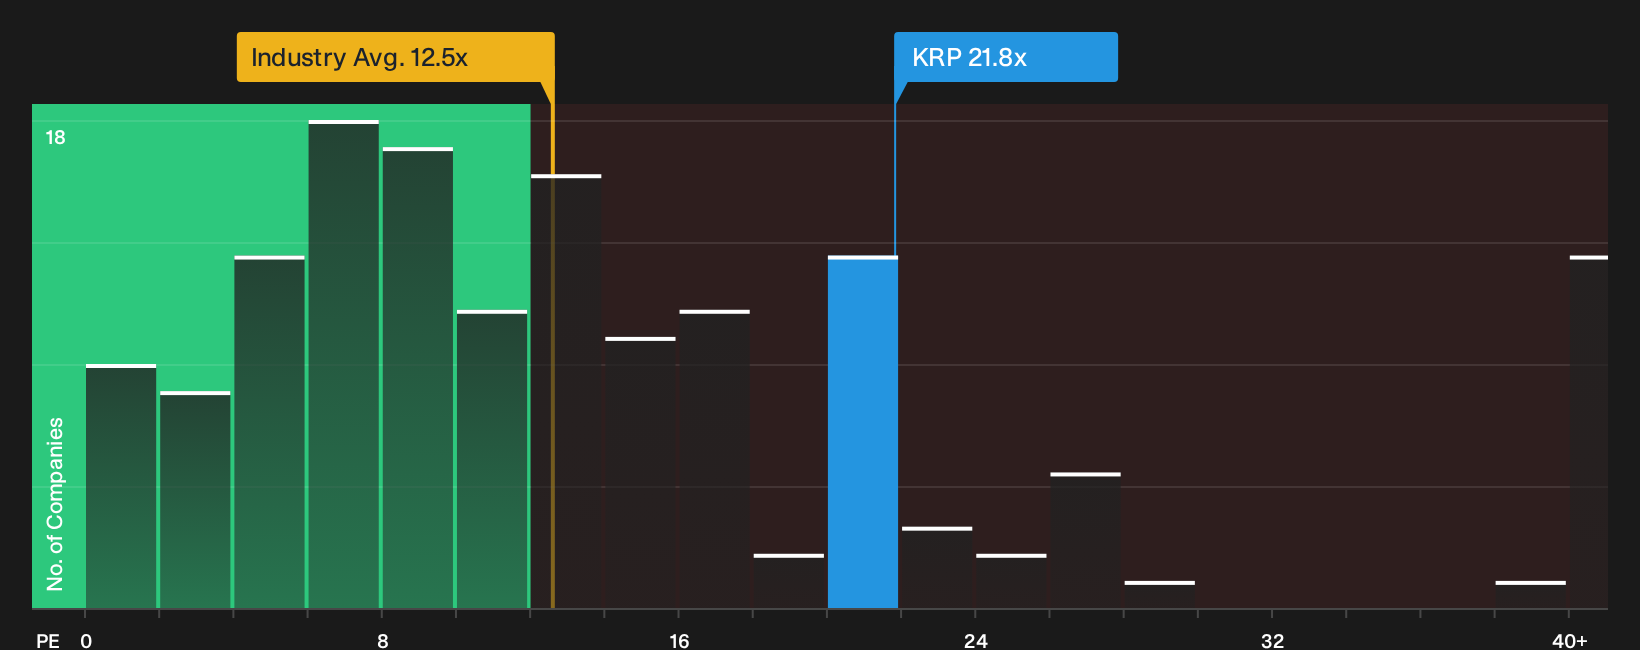
The SWS DCF model points to upside, yet the simple P/E check sends a different message. Kimbell Royalty Partners trades at 21.8x earnings, while the US Oil and Gas group sits around 12.5x and closer peers average 12.6x. The fair ratio estimate is 16.1x, so the current tag looks rich and leaves less room for error if growth assumptions soften.
See what the numbers say about this price in more detail in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Kimbell Royalty Partners is mixed, with real risks on one side and clear potential on the other. Move quickly and review the detail yourself to decide where you stand by checking the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Kimbell Royalty Partners?
If Kimbell Royalty Partners has your attention, do not stop here. Broaden your watchlist now so you are not late to the next setup.
- Target companies with strong cash generation and appealing entry points by scanning the 29 high quality undervalued stocks that fit your return and risk preferences.
- Lock in potential resilience by reviewing the list of solid balance sheet and fundamentals (24 results) to spot businesses that pair financial strength with steady execution.
- Hunt for future leaders early by running the 21 high quality undiscovered gems and flagging quality operators before they hit the mainstream.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com