


CorVel has logged a solid share price run over multiple years, which naturally raises a simple question for holders and would-be buyers: Do the cash flows that CorVel can generate actually line up with where the stock trades today?
- Over the past 5 years the stock has returned 37.3%, which puts a meaningful spotlight on whether the current price can still be explained by the cash it is expected to produce.
- The business model leans heavily on converting healthcare and workers compensation services into consistent free cash flow, which can influence how much value investors ascribe to each dollar of future inflows and how sensitive that value is to changes in assumptions.
- Prefer to judge CorVel on earnings? See what CorVel's 36.7x P/E says about the price.
The stock's next move may depend on whether CorVel's present share price can be squared with its intrinsic value estimate based purely on its cash flows.
If you are weighing whether CorVel's recent cash flow profile justifies the current price, it can help to cross check that thinking against a wider group of 29 high quality undervalued stocks.
Has CorVel Run Too Far on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash CorVel is expected to generate for shareholders and then discounts it back to today. On the latest twelve month numbers, the group produced free cash flow of about $110 million, which anchors the whole exercise in actual cash generation rather than accounting profit.
The projections then assume CorVel can grow that free cash flow steadily over the next decade, at low single digit rates each year, before settling into a more mature phase. On those inputs, the DCF output sits meaningfully below the current share price of $83.87. This suggests the market is paying a higher price than this cash flow model supports on its own. For anyone holding or researching CorVel, the key question is whether the business can produce stronger cash flows than these fairly measured assumptions build in, or whether the stock is simply pricing in qualities the DCF does not capture easily, such as competitive positioning or balance sheet strength. Find out what CorVel could be worth using our Discounted Cash Flow (DCF) estimate.
The CorVel Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the CorVel valuation puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Instead of a single output from a ratio or cash flow model, these scenarios lay out the future path that number rests on so you can watch how CorVel’s actual progress lines up over time on the Community page.
A fresh, number driven narrative on CorVel offers a clear view of which growth, margin, and execution assumptions need to be met for today’s price to be sustained. It turns loose expectations into a concrete roadmap that can be checked against CorVel's actual results as they are reported over time.
Share your own Narrative for CorVel and set out the assumptions behind your valuation.
One more CorVel signal investors often overlook
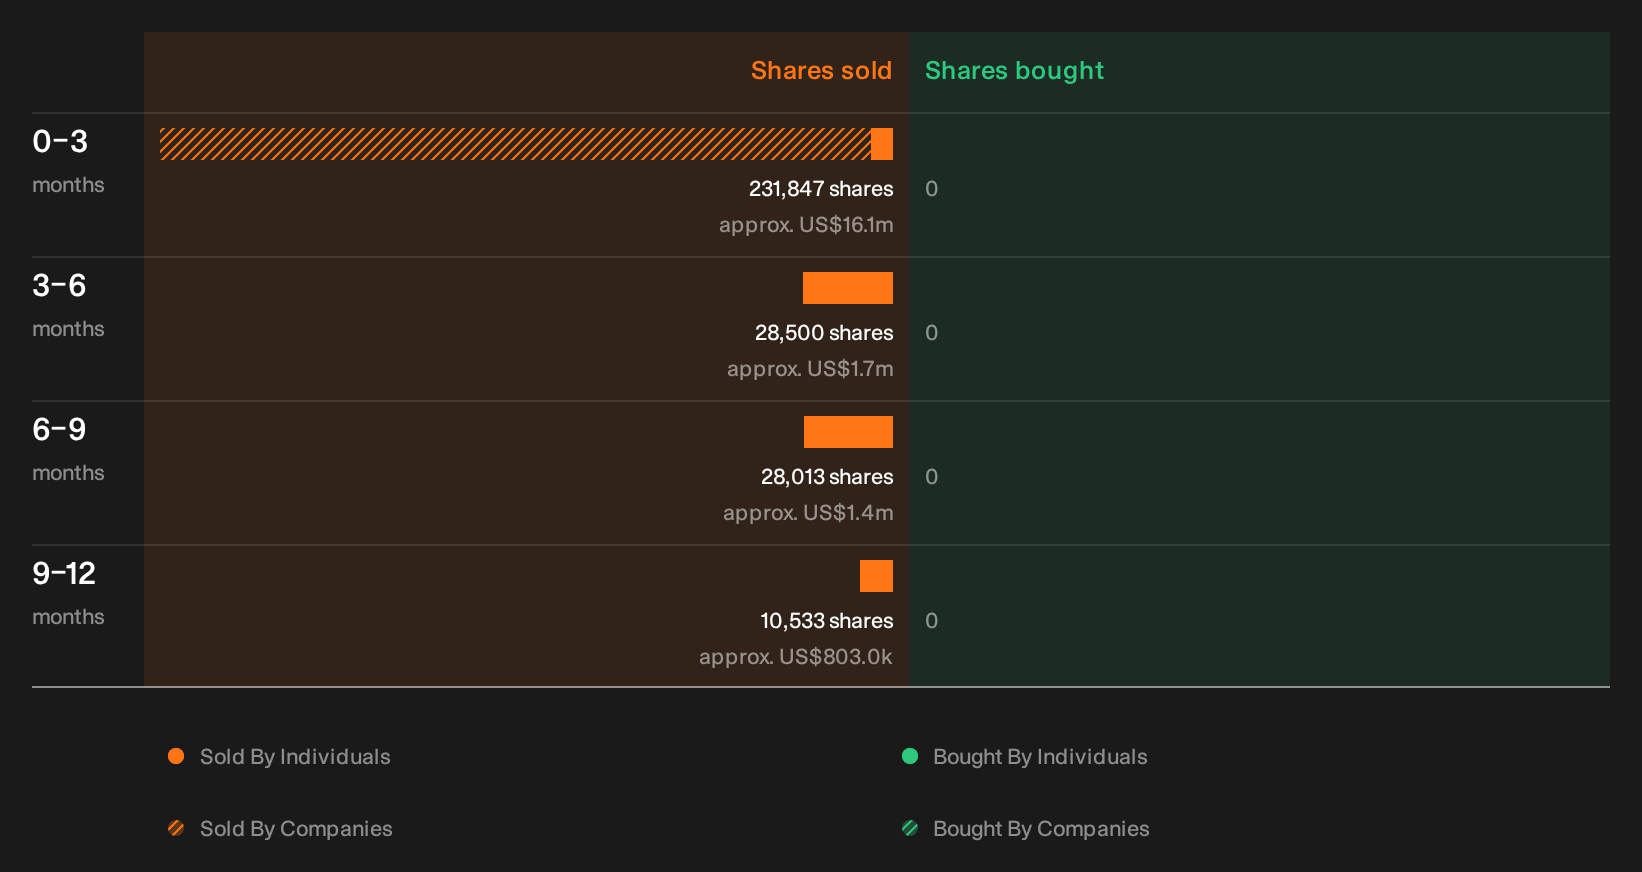
CorVel's valuation story is only part of the picture, because recent share transactions by people inside the business have been flagged by our checks and the who, how much and why are still for you to explore. See the recent insider selling flagged for CorVel.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com