


Interest rates look stuck on hold as the Federal Reserve signals a pause while inflation and energy costs stay stubborn. Cash in the bank now feels safer, yet future returns are uncertain. Reliable dividend payers start to look like a paycheck you do not have to work for. This piece walks through three high yielding US dividend stocks that combine income strength with disciplined payout habits.
The three stocks highlighted here offer a compelling starting point if you want exposure to well covered, growing and stable dividend income. However, if you want the absolute best, these 5 dividend aristocrats stocks are the cream of the crop.
Fulton Financial (FULT)
Fulton Financial brings the Dividend Powerhouses theme to life through a traditional regional banking engine that throws off steady cash for shareholders.
Fulton Financial is a regional banking group that earns most of its money from classic banking and wealth management, paying dividends out of this recurring interest and fee income. It generated about US$1.37b from banking activities and has a market value near US$4.5b.
"Fulton Financial is progressing its acquisition led expansion in Philadelphia and Northern New Jersey, where the Blue Foundry deal has already added about US$1.6b of loans and US$1.5b of deposits, and management still expects cost saves to move the acquired quarterly expense base from about US$10.5 million to under US$7 million, which could support higher earnings as integration benefits are reflected."
Dividend strength now leans heavily on how one quiet shift in the cost and funding mix ultimately filters through to long term margins.
If that funding mix shift is what you care about, read the full narrative for Fulton Financial to see how Fulton Financial’s acquisition push could reshape its payout story.

United Bankshares (UBSI)
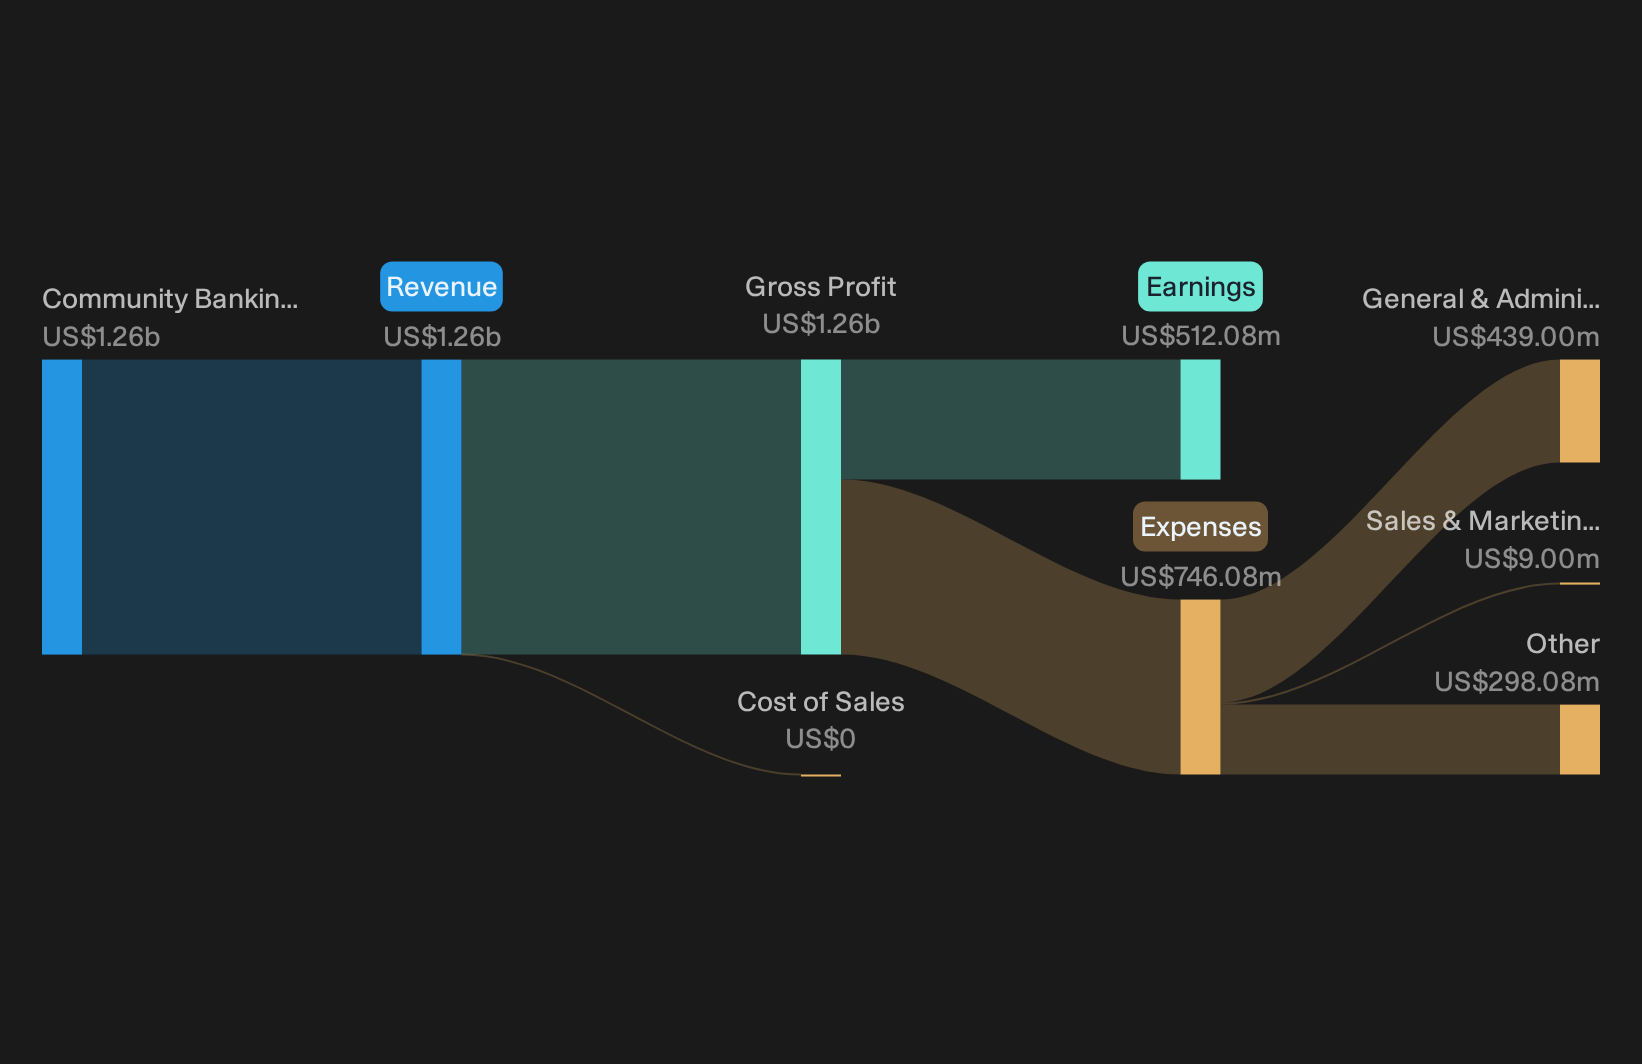
United Bankshares runs a traditional commercial and retail banking franchise that turns everyday lending and deposit activity into dividend power. It earned about US$1.26b from community banking in the United States and has a market value near US$6.5b.
United Bankshares pays a 3.12% yield backed by core lending and fee income, with 40.7% net profit margins and steady earnings growth helping to cover the payout. Dividend focused investors may watch what happens if one quiet pressure on those banking margins shifts direction.
If that margin pressure is what you are watching, go straight to the analyst forecasts for United Bankshares to see how United Bankshares earnings expectations could reshape the dividend story.
OceanFirst Financial (OCFC)
OceanFirst Financial leans into the Dividend Powerhouses theme by using traditional community banking to turn net interest income and fee based services into a regular cash payout for shareholders.
OceanFirst Financial runs a US community bank focused on deposits and loans, generating about US$428 million from community banking services and a dividend funded mainly by net interest income and related fees. The group is valued at roughly US$1.6b.
For dividend focused investors, OceanFirst Financial offers a 4.79% yield that is closely tied to how effectively its community banking engine can turn deposits and loans into recurring cash flows that support ongoing payouts.
"The June 2026 acquisition of Flushing Financial added about US$7.4b of deposits and 30 branches across New York City and Long Island. This creates more scope to grow relationship based deposits and fee income over time and could support higher revenue and earnings as the combined franchise matures."
What happens if one quiet shift in how those new deposits are priced against loan yields changes the cushion under OceanFirst Financial’s dividend coverage?
If that pricing shift is what you are weighing, read the full narrative for OceanFirst Financial to learn how OceanFirst Financial’s expanded footprint could support income strength while keeping risks in check.

Seeking Fresh Alternatives Beyond Dividends
New ideas move fast. Some tickers start building momentum, others drop back once the crowd catches on. Scan fresh potential breakouts while it still matters and get in early.
- Spot cash rich businesses before they are fully priced by running the 29 high quality undervalued stocks and filtering for balance sheets and cash flows that still look under the radar for now.
- Ride infrastructure momentum by using the 42 power grid technology and infrastructure stocks to focus on companies tied to grid upgrades, electrification and long dated capital projects.
- Target real assets that can respond differently to inflation by reviewing the curated 35 elite gold producer stocks and checking which producers match your risk and return preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com