


NatWest Group has seen its share price climb sharply over the past few years, yet recent setbacks and shifting sentiment now put a spotlight on a basic question for you as a shareholder or potential buyer. Is the current valuation of NatWest stock still supported by the earnings power of the business?
- Over the past 3 years the share price has delivered a return of about 3.1x, which raises the stakes on whether the earnings profile can carry that kind of re-rating.
- Fresh headlines around possible changes to the UK bank surcharge tax, along with analyst upgrades that lean on a stronger earnings outlook, mean expectations for NatWest's future profitability and capital needs sit front and center in any price discussion.
- There is a second opinion on NatWest Group worth weighing. See what analysts think NatWest Group's shares could be worth.
The issue now is whether NatWest's current share price is adequately justified by the earnings it is generating and is expected to produce.
If you want a broader watchlist while assessing whether NatWest Group's current price lines up with its earnings, a focused stock screen of 8 high quality undervalued stocks can be a useful next step.
Where Does NatWest Group Sit on Earnings?
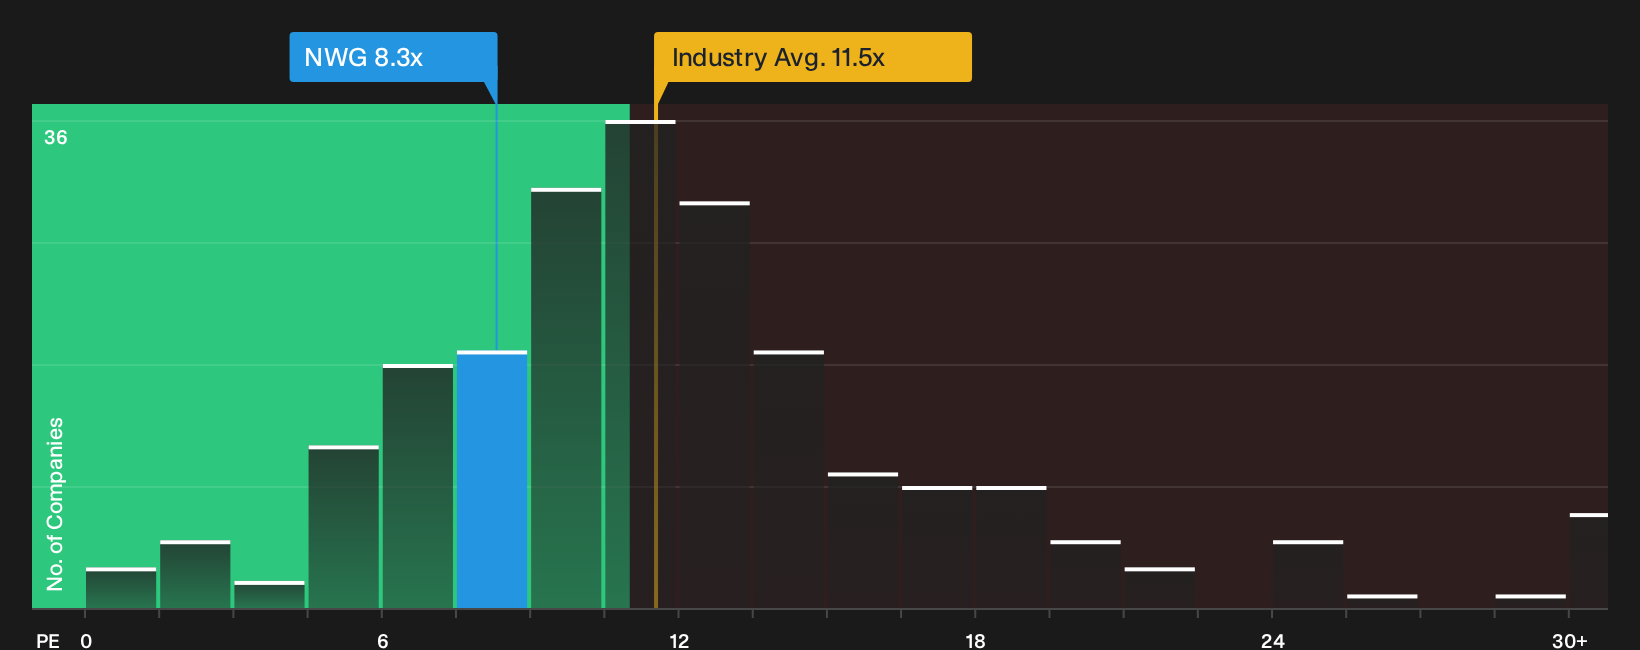
P/E fits NatWest Group because earnings remain the main anchor for how investors judge large banks. On this measure, the stock trades on about 8.3x, compared with a Banks sector average of roughly 11.1x and a peer group closer to 10.4x, so the market is paying less for each pound of current earnings than for many comparable institutions.
The fair multiple implied by the excess returns model, which blends NatWest Group’s forecast profitability, book value profile, size and risk, sits slightly above the current P/E. The shares therefore come across as modestly cheap on this framework rather than stretched. Because recent headlines have focused on a possible rise in the UK bank surcharge tax, that discount suggests investors are already building some caution into the price despite the recent broker upgrade. Explore the numbers behind NatWest Group's P/E valuation.
The NatWest Group Narrative: What Would Justify Today's Price?
NatWest Group's current P/E and sector discount raise a simple follow up question for you as an investor. What needs to happen to earnings, margins and risk for that gap to close, or to widen? Narratives on Simply Wall St's Community page pick up that thread and spell out the specific futures that would make the stock worth materially more or less than today. Each scenario ties its number to a clear view on how growth, profitability and potential downsides might evolve over time, which you can revisit as fresh information comes through.
One of the top community narratives on NatWest Group: 21% undervalued
"Completion of the Evelyn Partners acquisition at the end of June 2026, which more than doubled NatWest Group assets under management and administration to £131b..."
Discover why this Narrative puts NatWest Group at 21% undervalued.
NatWest Group: why the share price is only one piece of the decision
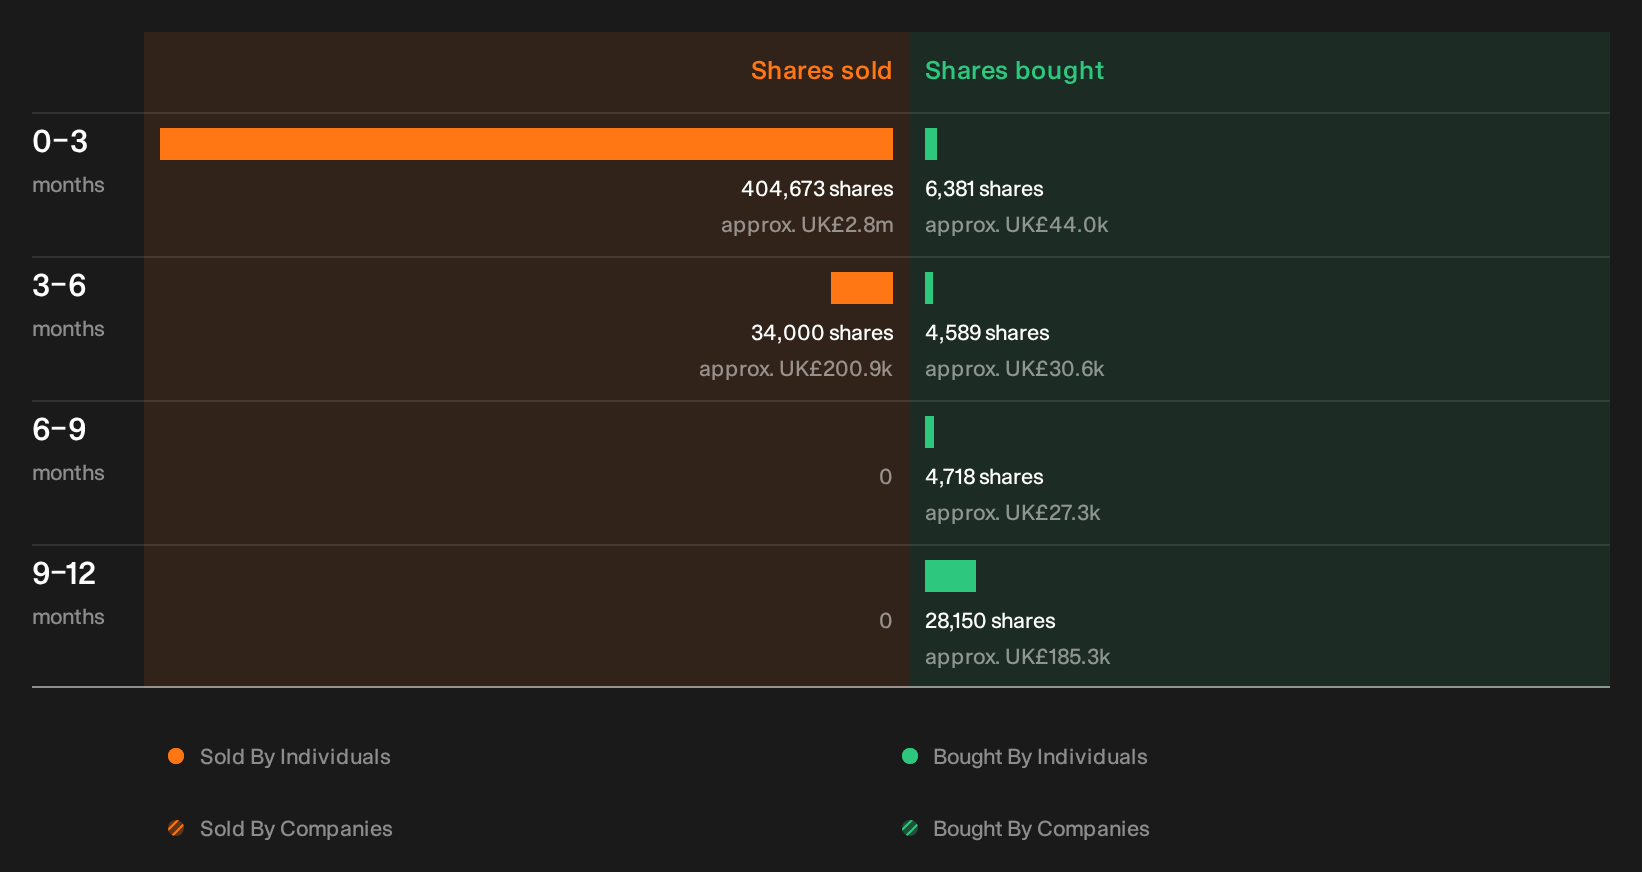
Price multiples tell you what the market thinks today, but recent director share transactions can hint at what those closest to NatWest Group are doing with their own money. See the recent insider selling flagged for NatWest Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com