


Labcorp Holdings (LH) just signed a partnership with Waters Corporation to roll out the FDA approved BD Onclarity HPV Assay nationwide, expanding its cervical cancer screening toolkit for clinicians, health plans, and direct consumers.
All of this is landing while Labcorp Holdings’ share price sits at US$328.95 and has climbed 6.24% over the past 30 days and 9.22% over 90 days, with a 30.71% year to date share price return supporting a 71.21% three year total shareholder return that signals momentum has been building rather than fading.
Capitalize on Labcorp Holdings’ momentum in diagnostics by scanning a curated field of resilient healthcare players through our 30 resilient stocks with low risk scores.After that sharp run in Labcorp Holdings on the back of new diagnostics partnerships, the share price now sits only a modest distance below analyst targets. Is the remaining discount a genuine opportunity or a warning signal about market caution?
Most Popular Narrative: 4% Undervalued
Labcorp Holdings is trading at $328.95 against a widely followed fair value estimate of $344.25. The narrative still sees a modest valuation gap that hinges on how specialty diagnostics and biopharma services play out.
Labcorp Holdings continues to expand higher value specialty testing in oncology, neurology, autoimmune disease and women’s health, with this franchise now around US$2b in diagnostics revenue and a rising share of esoteric and specialty work, which supports higher revenue per patient encounter and contribution to earnings.
See why 6 investors see Labcorp Holdings as 4% undervalued.
Result: Fair Value of $344.25 (UNDERVALUED)
Still, the narrative around Labcorp Holdings can fray quickly if PAMA cuts hit harder than planned or if acquisitions fail to translate into healthier margins.
Find out about the key risks to this Labcorp Holdings narrative.
Another View: Labcorp Holdings Through The P/E Lens
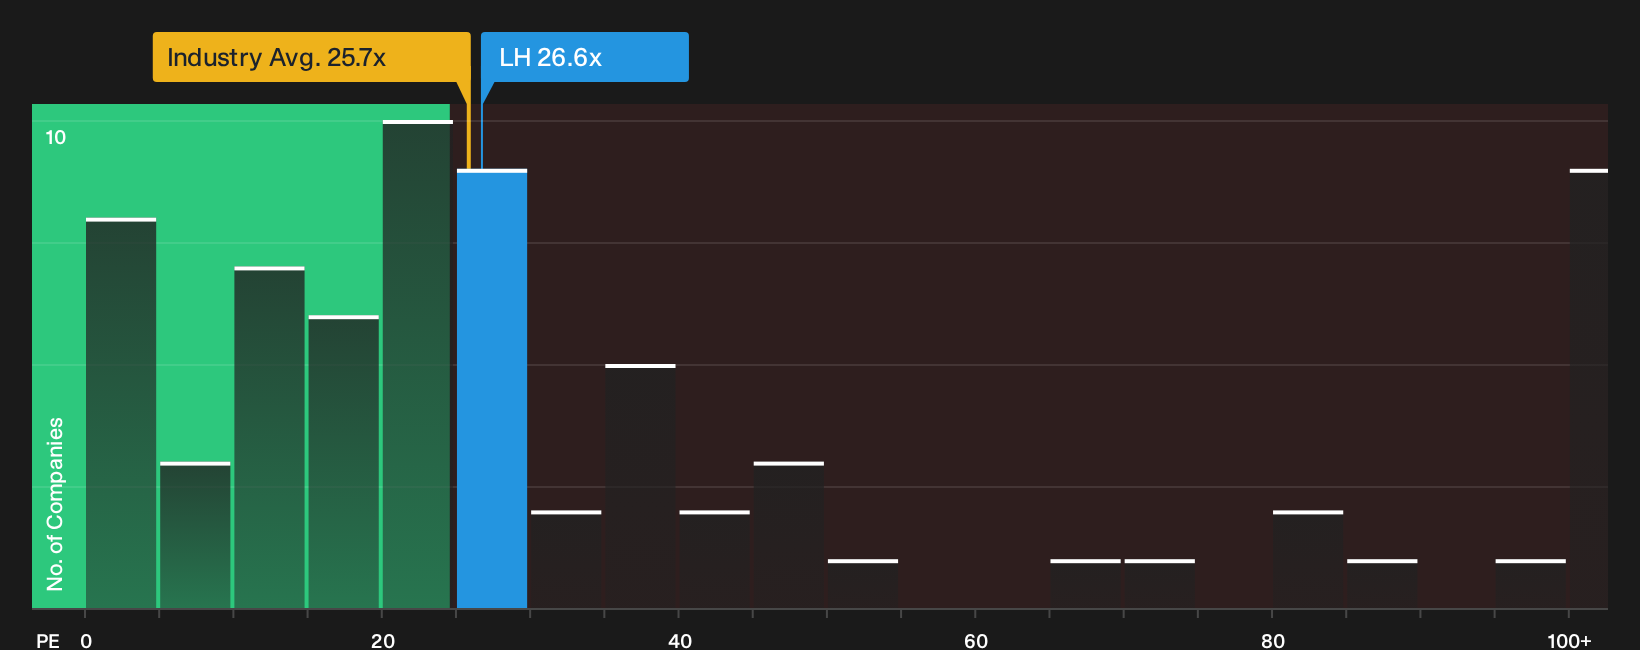
On one hand, the fair value narrative around Labcorp Holdings suggests a modest 4% upside. On the other, the current P/E of 26.6x sits above both the US Healthcare sector at 25.7x and the fair ratio of 25.9x, which points to some valuation risk if sentiment cools.
The peer group trades much richer at 43x earnings, so Labcorp Holdings still screens cheaper than many direct comparables. The gap between sector level, peer level and the fair ratio raises a simple question for investors: Is this a reasonable premium for quality earnings or a thin cushion if expectations slip?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Labcorp Holdings story can create noise, so review the numbers, weigh the trade offs, and then judge the balance of 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Labcorp Holdings?
If you only stop at Labcorp Holdings, you might miss other opportunities that better match your risk appetite, income needs, or valuation checklist.
- Target potential mispricing by scanning a curated pool of companies that combine quality fundamentals with a valuation gap through our 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that pair higher yields with staying power using the 5 dividend fortresses.
- Protect your downside by filtering for financially resilient candidates via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com