


- Edwards Lifesciences received FDA approval for its PASCAL Precision system for tricuspid valve repair and PASCAL Ace with Capture Clarity for degenerative mitral TEER, expanding its U.S. transcatheter repair toolkit across two complex valve diseases.
- The dual approvals make Edwards Lifesciences the only provider in the U.S. offering both repair and replacement transcatheter options for mitral and tricuspid valves. This can influence hospital purchasing decisions, procedure mix and how cardiology programs allocate capital across valve therapies.
- Now the focus shifts to how Edwards Lifesciences’ investment narrative absorbs wider PASCAL coverage in tricuspid repair and mitral TEER.
Scan beyond Edwards Lifesciences and identify other potential beneficiaries of cardiology and medtech demand with a curated list of list of solid balance sheet and fundamentals (24 results)
Edwards Lifesciences Investment Narrative Recap
To own Edwards Lifesciences, you need to believe the structural heart portfolio can turn guided TMTT growth and planned margin expansion into cleaner earnings, even after a year where profit declined and margins compressed from 24.8% to 15%. The recent PASCAL approvals strengthen that multi platform repair and replacement story but do not change the need to execute.
The key near term swing factor remains the push toward at least US$760 million to US$780 million of TMTT sales in 2026, while protecting profitability in the face of tariff risk and higher legal and compliance costs. Governance questions and insider selling sit in the background as potential overhangs.
The fresh FDA approval of the PASCAL Precision tricuspid repair system this week is the announcement most tightly tied to those TMTT ambitions. It broadens the pool of patients Edwards Lifesciences can treat in tricuspid regurgitation and could help utilisation across U.S. centers that are already investing in transcatheter programs.
That operational hook links directly to the longer term goal of at least US$2b of TMTT revenue by 2030 and to management’s aim for 50 to 100 basis points of annual operating margin expansion. The opportunity is balanced by execution risk around new program ramp up, competitive responses and ongoing cost pressures from trade and compliance requirements.
Edwards Lifesciences’ current analyst playbook points to US$8.5b of revenue and US$2.2b of earnings by 2029, based on 9.3% yearly revenue growth and an earnings increase of roughly US$1.2b from US$979.9m today.
Uncover why Edwards Lifesciences' fair value indicates a 13% potential upside to its current price that could narrow quickly.
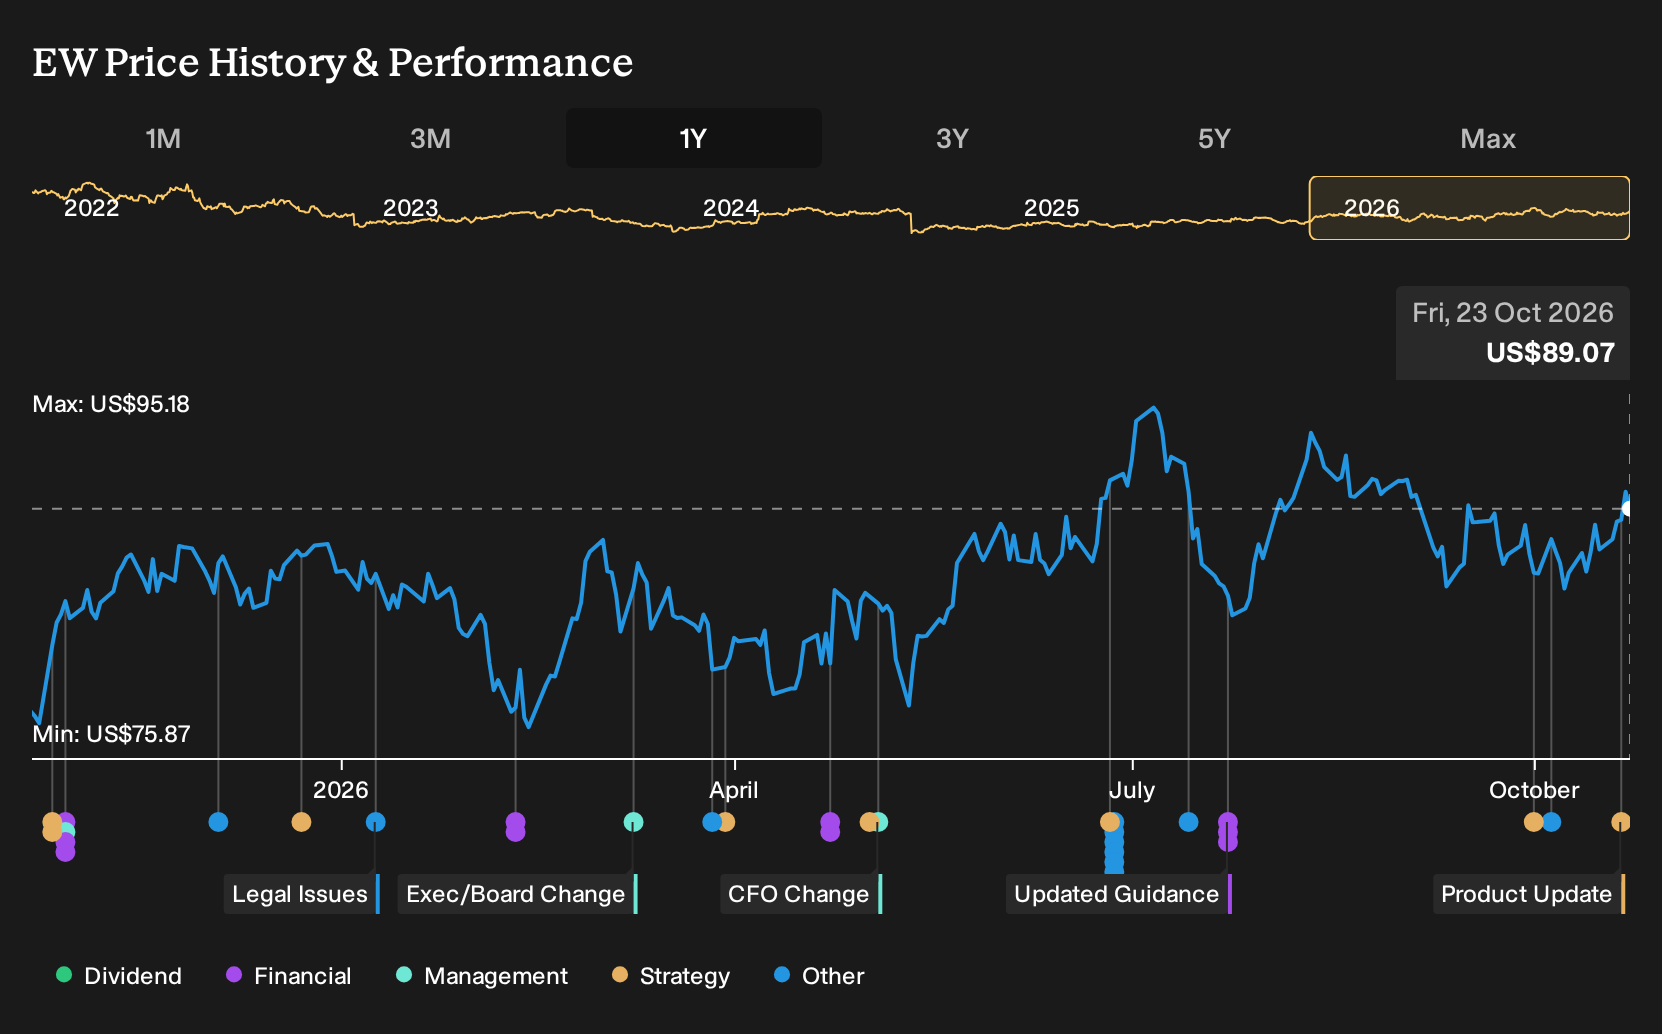
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$90.46 and US$100.96 per share, which already shows how far opinions on Edwards Lifesciences can stretch. Those views did not factor in the new PASCAL approvals, tariff and governance risks or Medicare and TMTT catalysts, so use them as starting points and explore several competing angles before forming a stance.
Explore another Edwards Lifesciences fair value estimate, including one that suggests there could be as much as 13% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Edwards Lifesciences?
Once the Edwards Lifesciences story is on your radar, it often helps to widen the lens and compare it with other opportunities that match your risk tolerance and style. The Simply Wall St Screener can surface different sets of companies that fit clear, data driven filters so you are not starting from scratch each time you research a new stock.
- If you want potential upside with stronger fundamentals doing the heavy lifting, review a curated set of 21 high quality undiscovered gems that pair quality profiles with smaller market footprints.
- For investors who care most about resilient balance sheets and dependable financial footing, focus on companies from the 30 resilient stocks with low risk scores and see which ones match your own risk guardrails.
- If dependable income matters more than fast price moves, zero in on payout focused opportunities using the 5 dividend fortresses and sort for yields and coverage ratios that fit your plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com