


Texas Pacific Land: Earnings, Data Centers, And Project Kilby In Focus
Renewed attention on Texas Pacific Land (TPL) is building ahead of its November 4 third quarter report, as investors weigh new data center partnerships and the company’s role in Chevron’s Project Kilby.
Against this backdrop, Texas Pacific Land’s share price has pulled back, with a 7 day share price return of 3.61% and a 90 day share price return of 14.71% pointing to fading short term momentum. At the same time, a 5 year total shareholder return of 153.68% still reflects strong long haul gains.
Scan how Texas Pacific Land compares to other potential breakouts in energy and infrastructure by reviewing our hand picked list of 42 power grid technology and infrastructure stocks.
Texas Pacific Land’s recent pullback can be read as either a cool down in enthusiasm or a reset that aligns the price more closely with its fee and royalty engine. How does that trade off appear in the valuation numbers investors are now facing?
Most Popular Narrative: 24% Undervalued
Texas Pacific Land’s most followed narrative anchors fair value at $445 per share, compared with a last close of $338.26. This puts the current debate squarely on whether its royalty and water assets justify that gap under a 7.1% discount rate.
Beneficial reuse and desalination initiatives, combined with advancing transmission and data center infrastructure in the Permian, provide exposure to future monetization avenues (industrial water supply, renewable energy, land leases), enhancing potential for diversified long-term revenue and asset value growth.
See why 27 investors see Texas Pacific Land as 24% undervalued.
Result: Fair Value of $445 (UNDERVALUED)
Still, concentrated reliance on Permian royalties and tightening ESG and water regulations could pressure Texas Pacific Land’s future earnings path and challenge today’s optimistic assumptions.
Find out about the key risks to this Texas Pacific Land narrative.
Another View: Texas Pacific Land Through Market Multiples
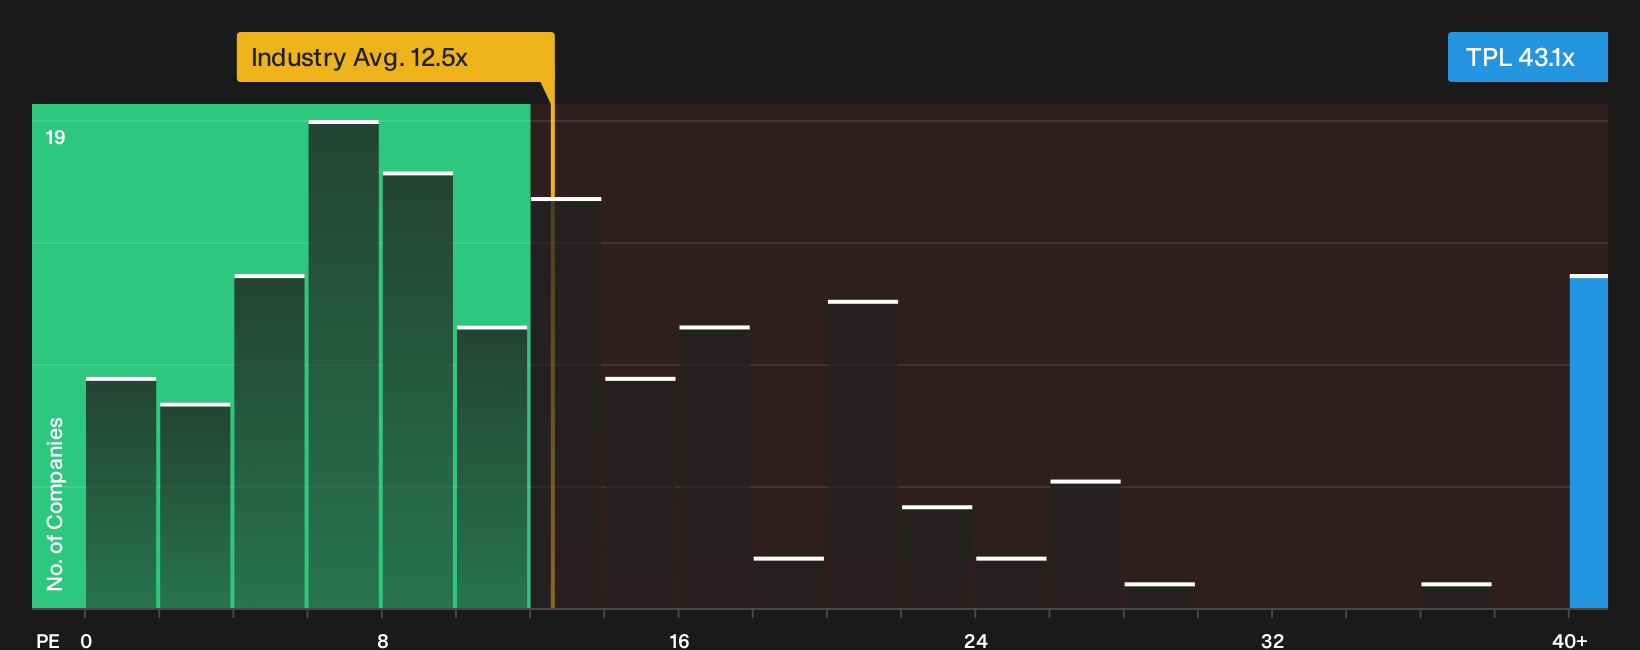
Texas Pacific Land screens very differently when you switch from fair value estimates to what investors are actually paying today. The stock trades on a P/E of 43.1x, compared with a fair ratio of 19.4x and a peer average near 12x, which suggests a rich valuation built on strong expectations.
That kind of premium can reward holders if the growth case plays out, but it also raises the risk that any disappointment in royalties, water revenue, or data center fees hits the share price harder than the broader oil and gas group. The open question for investors is whether that multiple gap reflects durable strengths or just crowded optimism.
For a closer look at how these P/E gaps stack up against both peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Texas Pacific Land can feel messy, so move quickly, review the data carefully, and decide where you stand on its 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Texas Pacific Land?
Once you have formed a view on Texas Pacific Land, do not stop there. Broader context from other opportunities can sharpen your judgment and highlight blind spots.
- Target potential upside by scanning 21 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that filters for businesses with stronger risk profiles.
- Strengthen your core holdings with a list of solid balance sheet and fundamentals (24 results) that focuses on companies with sturdier finances and cleaner leverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com