


Event-driven reappraisal of Tessenderlo Group
Renewed commentary around Tessenderlo Group (ENXTBR:TESB) has focused on claims that the stock trades well below a custom revenue-based benchmark, with discussion shifting toward earnings quality rather than raw expansion.
Recent trading tells a different story from the valuation chatter. Tessenderlo Group’s share price has fallen 33.1% year to date and its 1-year total shareholder return is also down 33%. Shorter term momentum has weakened, with a 30-day share price return of down 13.7%, despite a 1-day gain of 1.3% at €17.52. This suggests that the renewed debate around revenue-based undervaluation and earnings quality is arriving against a backdrop of fading price strength rather than a strong momentum run.
Scan revenue-led value ideas beyond Tessenderlo Group by reviewing the hand-picked 194 high quality undervalued stocks that investors are watching for potential reappraisals.
Tessenderlo Group now trades at €17.52 while one prominent target sits at €25.50. Where does a reasonable view of fair value actually land between those two anchors?
Most Popular Narrative: 31% Undervalued
The prevailing thesis values Tessenderlo Group at €25.50 per share, which sits well above the last close at €17.52 and puts the debate firmly on whether earnings quality can catch up with that valuation anchor.
The focus on higher value and more sustainable fertilizers, including the acquisition and planned ramp up from Q1 2027 of the Swedish SOP plant using low temperature green energy, can support future revenue and margin quality in Agro once production volumes build.
The planned PB Leiner and Rousselot gelatin and collagen joint venture, together with ongoing closures of older plants such as Vilvoorde and the impaired SOP facility in Ham, points to a leaner portfolio that can lift group EBITDA margins once the restructuring charges are behind the company.
See why 5 investors see Tessenderlo Group as 31% undervalued.
Result: Fair Value of €25.50 (UNDERVALUED)
Still, if fertilizer raw material costs stay elevated or the Machines & Technologies segment remains weak, the upbeat Tessenderlo Group thesis could quickly lose traction.
Find out about the key risks to this Tessenderlo Group narrative.
Another View: SWS DCF Puts Tessenderlo Group In A Different Light
The analyst narrative leans on a €25.50 fair value for Tessenderlo Group, yet the SWS DCF model points in almost the opposite direction. On that future cash flow view, the shares at €17.52 trade well above an estimated value of €6.08, which screens as overvalued rather than cheap. When two methods disagree this sharply, which one do you trust with your capital decision?
Look into how the SWS DCF model arrives at its fair value.
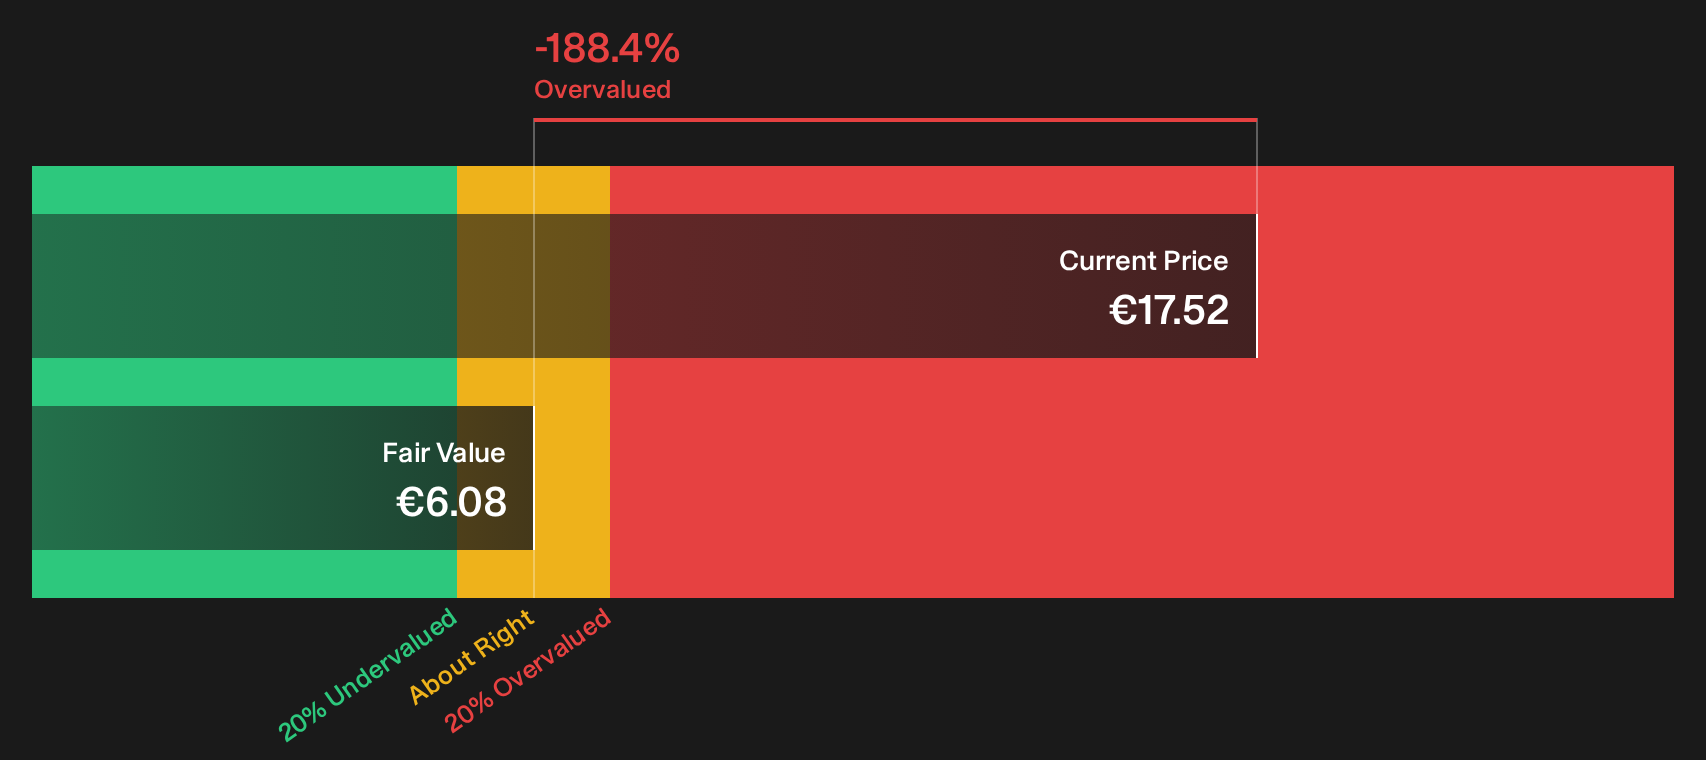
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tessenderlo Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Tessenderlo Group’s valuation and narrative can cut both ways, so move fast, review the data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Tessenderlo Group style ideas?
If Tessenderlo Group has you reassessing value, do not stop here. Put a structured lens over the wider market using focused screeners that surface clear, data backed ideas.
- Target reliable income streams by reviewing companies we flag as potential income anchors through the 226 dividend fortresses.
- Hunt for mispriced opportunities by scanning our hand picked pool of quality candidates in the 194 high quality undervalued stocks.
- Prioritise resilience and capital preservation by shortlisting candidates from the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com