


Raya Financing’s decision to deploy Temenos (SWX:TEMN) Core for its expansion in Saudi Arabia puts fresh attention on the stock, as investors weigh what this new client win might mean.
Temenos shares have picked up momentum recently, with a 30 day share price return of 11.32% and a 90 day gain of 14.74%. This comes even though the year to date share price performance is down 8.28% and the five year total shareholder return shows a 41.58% decline.
See how Temenos compares with other financial software players by checking a curated set of list of solid balance sheet and fundamentals (205 results) as potential alternatives in the same space.
Recent momentum, a long stretch of weaker multi year returns, and a fresh contract win leave Temenos at an awkward crossroads. Is it worth paying up today, or does it make more sense to wait for a cheaper entry?
Most Popular Narrative: 9.8% Undervalued
Against a last close of CHF74.75, the most followed Temenos narrative pins fair value at CHF82.88, which leaves a modest gap that hinges on how recurring revenue and margin ambitions play out.
The company is calling out a broad based and stable sales environment, with banks continuing to prioritise digital transformation and no visible impact so far from U.S. bank credit concerns. This could support ongoing demand for Temenos platforms and underpin revenue and earnings.
See why 6 investors see Temenos as 10% undervalued.
Result: Fair Value of CHF82.88 (UNDERVALUED)
Still, Temenos relies heavily on premium maintenance with limited churn, and long implementation cycles and the timing of large deals could quickly unsettle that undervaluation story.
Find out about the key risks to this Temenos narrative.
Another View On Temenos Valuation
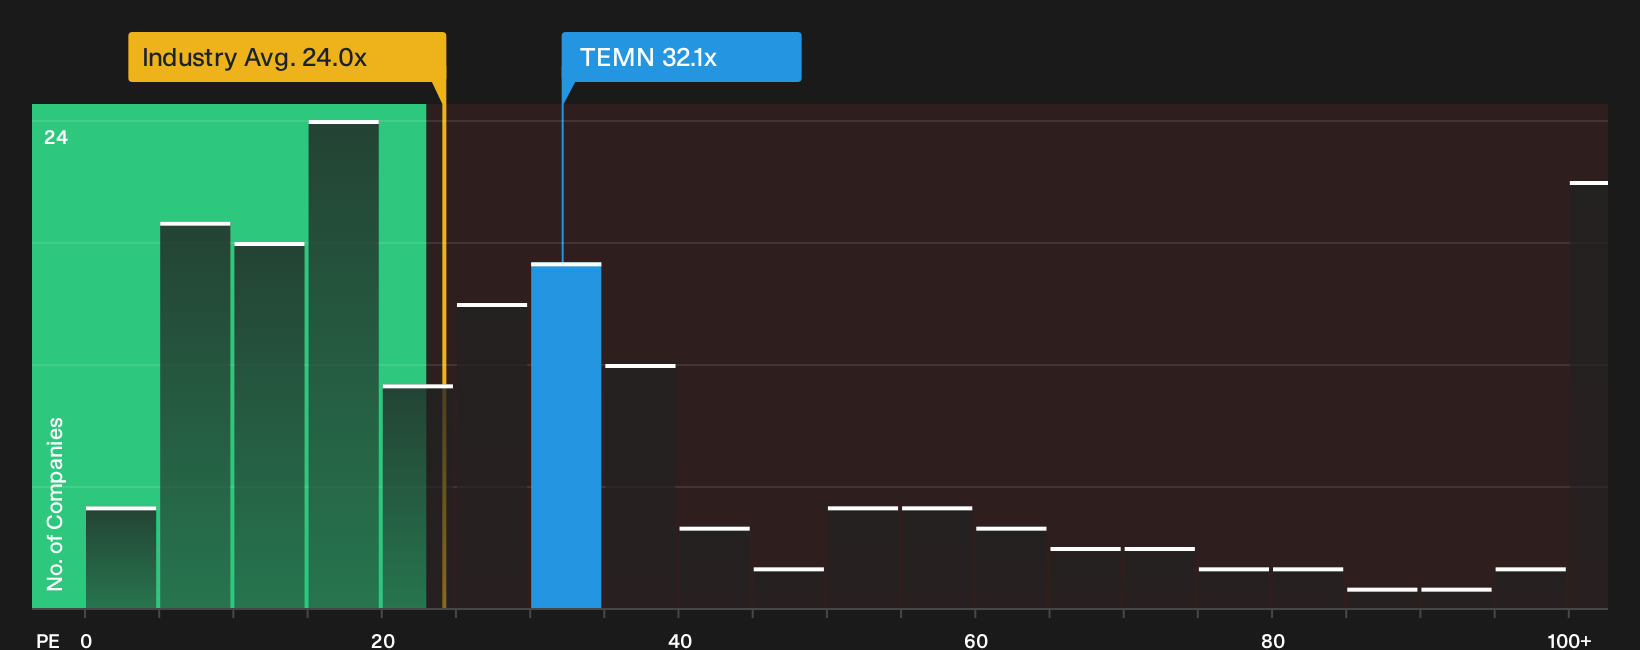
The earlier fair value of CHF82.88 leaned heavily on future cash flows and recurring income. A simple P/E cross check tells a cooler story. Temenos trades on 32.1x earnings, compared with 28.7x for peers and 24x for the broader European software group.
That premium can signal belief in Temenos quality earnings and forecast 12.1% annual profit growth, or it can mark a thinner margin for error if execution slips again after last year’s profit decline and lower net margin. With the stock already above peer multiples, which story do you think the market is really paying for right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Temenos can pull you in both directions. Move quickly, review the full data yourself, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Temenos alternatives?
If Temenos has your attention but you want a wider watchlist, use the Simply Wall Street Screener to surface fresh ideas before the crowd catches on.
- Target resilient compounding potential by scanning a curated set of 226 dividend fortresses that aim to pair income with balance sheet strength.
- Hunt for mispriced quality by reviewing a focused group of 613 high quality undiscovered gems that score well on fundamentals yet attract limited market attention.
- Dial down portfolio stress by filtering for 221 resilient stocks with low risk scores that score well on resilience and financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com