


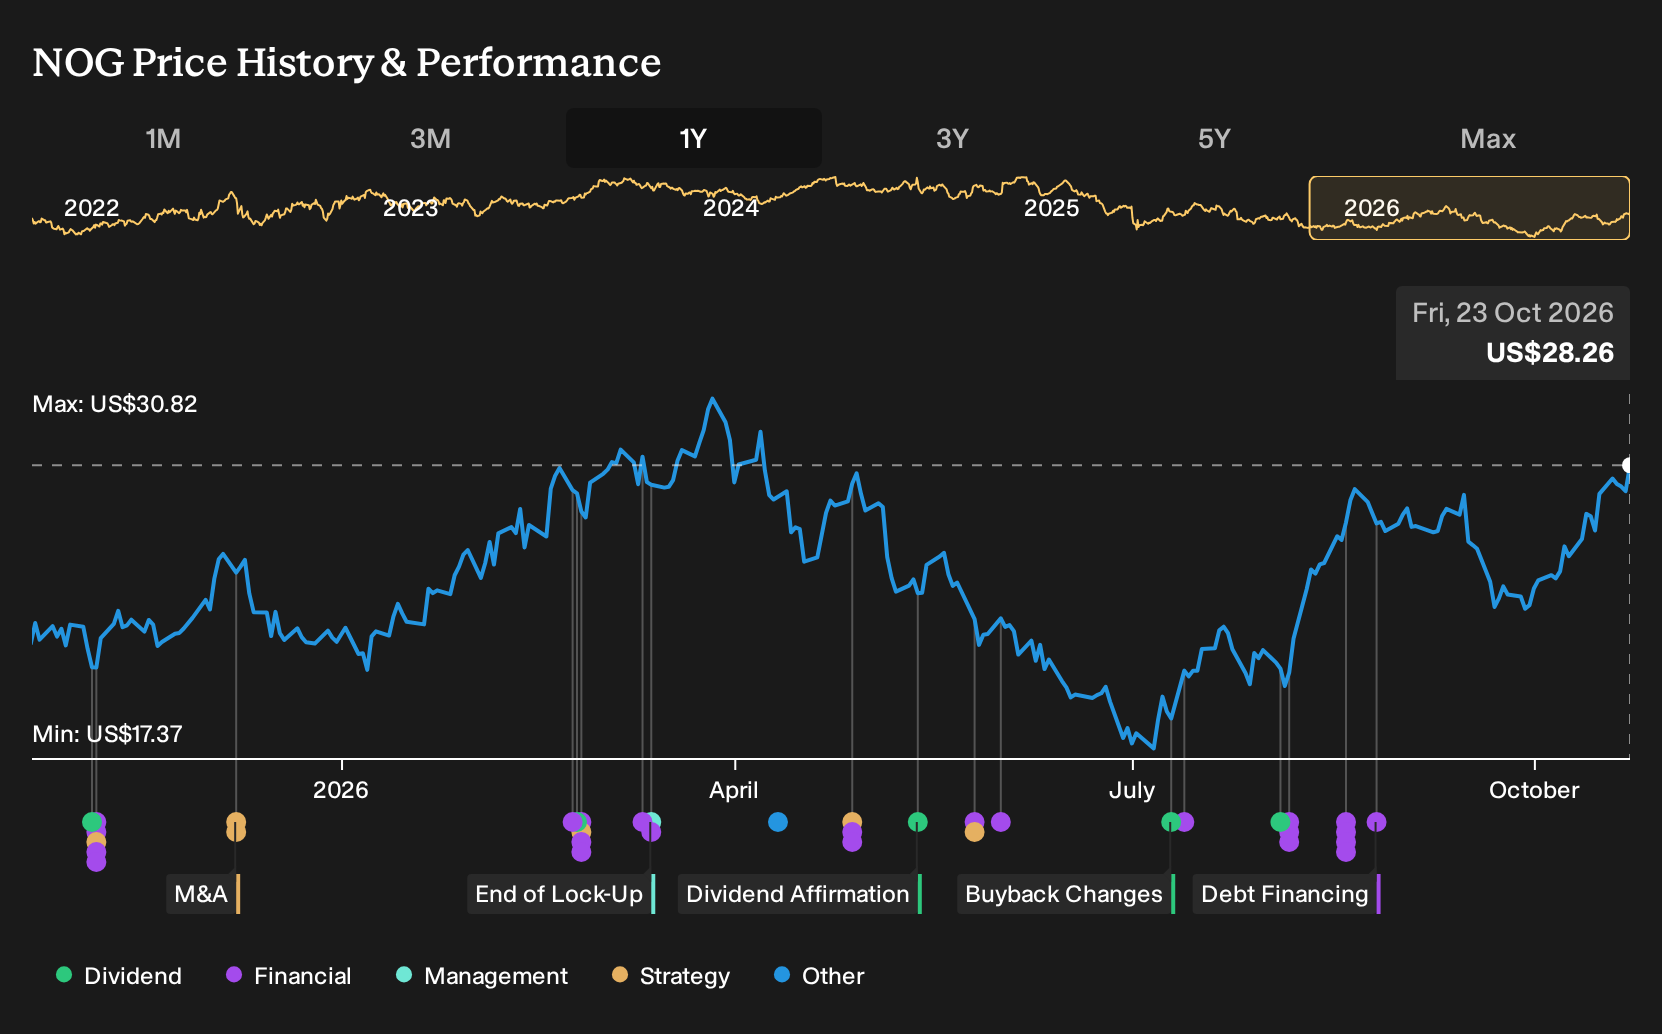
- Northern Oil and Gas completed its July 2024 repurchase program in the third quarter of 2026, buying a total of 6,656,391 shares for US$172.66 million, including 667,989 shares in the most recent quarter.
- The finished buyback, combined with reaffirmed 2026 production guidance and defined third quarter capital spending plans, highlights a focus on capital returns alongside maintaining operational activity levels.
- We will now look at how Northern Oil and Gas's completed buyback program could influence the existing investment narrative around capital allocation.
See how Northern Oil and Gas fits alongside other potential capital return and cash flow plays by comparing it with 29 high quality undervalued stocks in the current market backdrop.
Northern Oil and Gas Investment Narrative Recap
To own Northern Oil and Gas, you need to be comfortable with a non operated, multi basin model that leans on partners to deliver the drilling plan while management concentrates on capital allocation. The reaffirmed 2026 production guidance and defined third quarter capital spending suggest operating activity is being held steady. That keeps near term attention on execution in Utica, Duvernay and core U.S. plays rather than on volume surprises.
The biggest short term catalyst is the upcoming third quarter report around November 5, which should show how realized prices, hedges and costs translate into cash generation. The key risk is that higher expenses and interest costs limit free cash flow, especially for a business that is still reporting a net loss and carries higher coupon debt.
The completed US$172.66 million buyback, retiring 6,656,391 shares or 6.51% of the register since July 2024, is the announcement that ties most directly to the current story. Northern Oil and Gas has leaned into capital returns at the same time as it guides to third quarter capital spending of US$250 million to US$253 million and reiterates production targets.
For you, the operational question is whether ongoing free cash flow can comfortably support this level of repurchases alongside a dividend that is flagged as not well covered by earnings or cash flows and interest that is not well covered by profits. The upcoming earnings release will be an important check on how sustainable that balance looks.
Northern Oil and Gas Analyst Assumptions In Focus
Northern Oil and Gas sits on a fairly punchy set of analyst assumptions. The current consensus builds in revenue growth of 8.2% each year for the next 3 years and a swing in profitability from a reported loss of US$486.0 million today to forecast earnings of US$498.5 million by 2029. That move represents an earnings change of roughly US$985 million from current earnings to the 2029 consensus profit figure. On those estimates, analysts see the business earning US$4.57 per share and applying a P/E multiple of 10.0x, which they note is below the current 12.3x level quoted for the wider US oil and gas peer group.
Northern Oil and Gas' narrative projects US$2.5b revenue and US$498.5 million earnings by 2029. This requires 8.2% yearly revenue growth and an earnings increase of roughly US$985 million from current earnings of a US$486.0 million loss.
These forecasts also assume that margins recover meaningfully, with analysts expecting profit margins to move from a loss position of 24.2% today to a positive margin of 19.6% over the next 3 years. At the same time, the share count is projected to rise by 7.0% per year. This means per share outcomes depend not just on the income statement but also on how aggressively Northern Oil and Gas continues to issue equity or offset dilution through buybacks. For you, the key judgment is whether a swing of this size in both profitability and share count feels realistic given the existing leverage, the higher coupon notes and the current pattern of non cash charges.
On the valuation side, analysts have tied these earnings and revenue targets to a consensus price target of US$30.44 per share, compared with a current share price of US$23.83. The spread between the most optimistic and most cautious targets is wide, from US$38.00 down to US$25.00. That range underlines how much disagreement exists around how Northern Oil and Gas will balance growth, acquisitions, free cash flow and capital returns by 2029. Before leaning on any of these figures, it is worth stress testing them against your own view on commodity price volatility, capital efficiency in Utica and Duvernay, and the ability of the non operated model to deliver the margin and earnings profile embedded in these estimates.
Uncover why Northern Oil and Gas' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Another angle to weigh is the bearish focus on debt pressure. The lowest analysts were pencilling in US$2.3b of revenue and US$622.8 million of earnings by 2029, yet still anchored on a US$25.00 target. That is a far more cautious narrative than consensus, and the completed Northern Oil and Gas buyback could prompt those views to shift.
Explore 5 other Northern Oil and Gas fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northern Oil and Gas research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northern Oil and Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Oil and Gas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Northern Oil and Gas?
If you want to put Northern Oil and Gas in context and widen your opportunity set, it helps to line it up against other stocks with different capital return profiles, balance sheets and risk levels using the Simply Wall St Screener.
- For investors who care most about quality and valuation, compare Northern Oil and Gas to a wider set of potential compounders using the 29 high quality undervalued stocks to see which businesses combine strong fundamentals with appealing pricing.
- If resilience and capital protection matter most to you, filter for companies with more durable financial profiles through the 30 resilient stocks with low risk scores and see which tickers carry lower overall risk scores.
- To widen the opportunity set beyond well known tickers, scan for underfollowed prospects with healthier fundamentals using the 21 high quality undiscovered gems and see which businesses might deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com