


Tractor Supply (TSCO) just put fresh numbers on the table, with third quarter earnings beating Wall Street expectations even as profitability stayed under pressure and management kept its full year outlook in place.
The fresh earnings beat has not yet turned sentiment around. Tractor Supply’s share price is up 5.09% over the past 90 days and 3.56% over the last month. However, the year-to-date share price return is still down 34.25%, with a 1-year total shareholder return decline of 39.19%, pointing to pressure that predates this quarter’s guidance reaffirmation and new digital leadership hires.
Spot 29 high quality undervalued stocks that, like Tractor Supply after this earnings beat and guidance reaffirmation, pair established business models with pressure on sentiment and an active plan to repair profitability.Bulls see Tractor Supply as a profitable rural retailer under temporary pressure. Bears see margin strain and a falling share price. Which story lines up better with the current valuation setup?
Most Popular Narrative: 7.9% Undervalued
On the most followed view of Tractor Supply, a fair value of $36.30 sits modestly above the latest $33.42 close. This puts the fresh earnings beat and guidance reaffirmation against a valuation that already bakes in some caution.
The new automated distribution center in Nampa, Idaho, which is expected to support more than 200 stores over time and is targeted to add about 20 basis points to gross margin in late 2026, could provide ongoing net margin benefits as supply chain efficiencies scale.
See why 45 investors see Tractor Supply as 8% undervalued.
Result: Fair Value of $36.30 (UNDERVALUED)
Still, the narrative can break if comparable sales remain weak and tariff refunds run out before freight and fuel costs ease for Tractor Supply.
Find out about the key risks to this Tractor Supply narrative.
Another View: Tractor Supply Through The P/E Lens
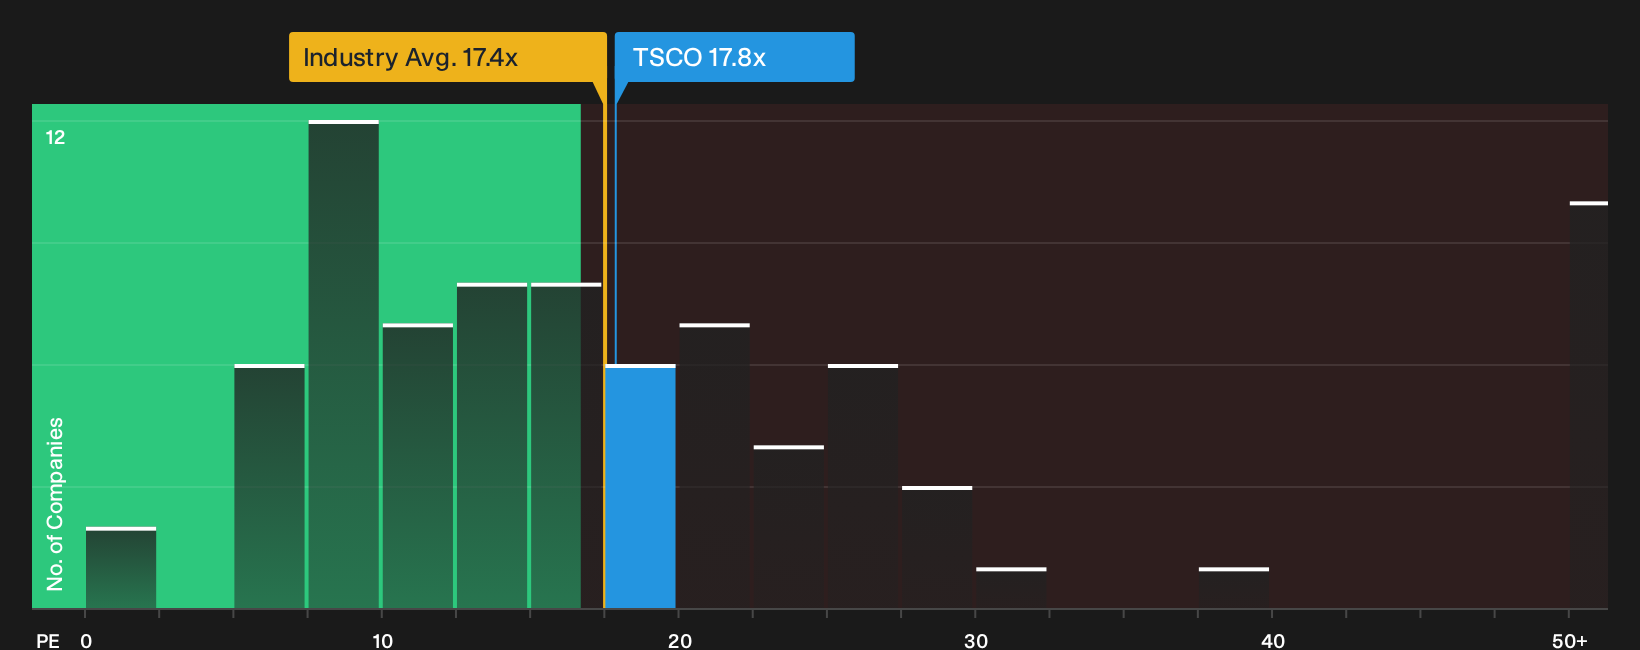
That 7.9% undervaluation on fair value is only one angle. On P/E, Tractor Supply trades at 17.8x earnings, slightly richer than the US Specialty Retail industry at 17.4x and above its fair ratio of 15.7x. Does paying a premium multiple for an underpriced cash flow story stack up for you?
For a closer look at how this earnings multiple compares to peers and what it could mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Tractor Supply story so far. Move quickly, review the numbers yourself, then weigh up the balance between 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tractor Supply?
If Tractor Supply has you rethinking what the market is pricing in, broaden the view with a few focused stock lists that can surface fresh opportunities fast.
- Target quality at a discount and scan companies that pair resilient fundamentals with compressed sentiment using the 29 high quality undervalued stocks.
- Strengthen your income stream by hunting for reliable payout candidates through the 5 dividend fortresses.
- Dial down portfolio risk and focus on resilient businesses with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com