


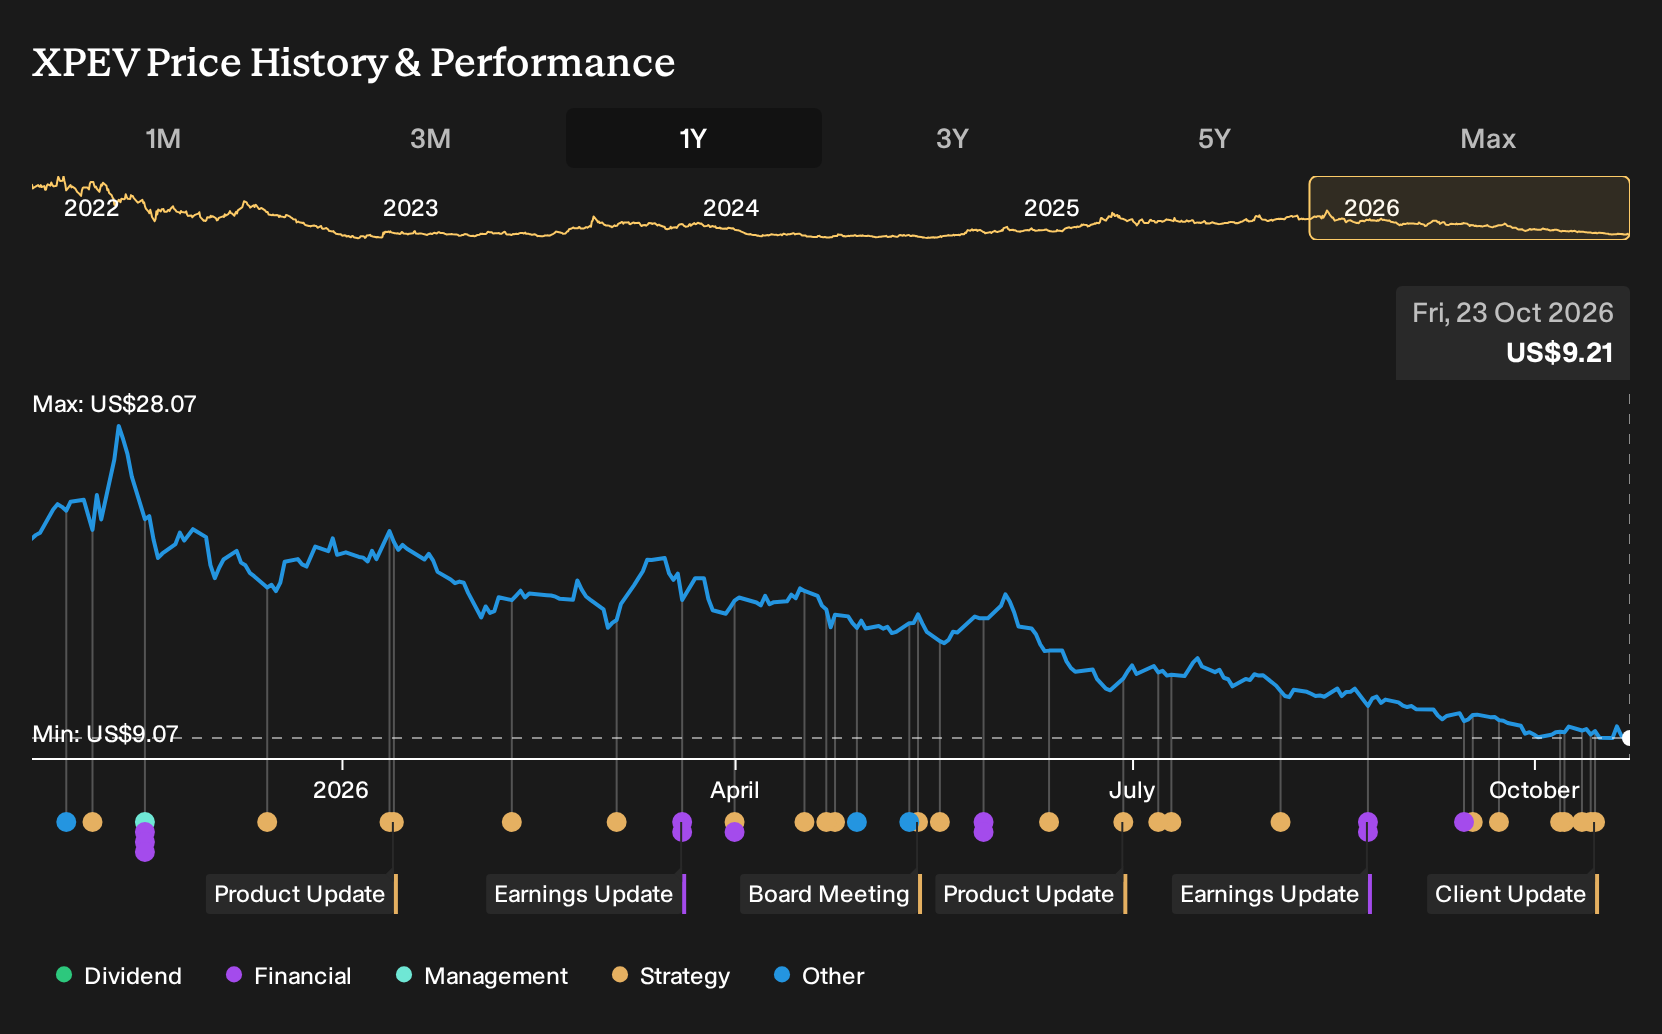
If you backed the XPeng story built on proprietary AI chips, physical AI, and global robotaxis, the recent scorecard is painful. Investors who held XPeng over the past year are down 57.4%, including dividends. If you made that decision in October 2025, you were leaning on analyst models that assumed strong revenue growth, a swing to positive margins, and a premium P/E multiple. Which of those specific assumptions did the outcome challenge rather than completely invalidate the original thesis?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put XPeng in the middle of this trade. Scan 95 robotics and automation stocks for other companies exposed to it.
The Argument XPeng Investors Were Weighing Up
The shares cost US$21.47 at the start of the period, and anyone buying XPeng then was choosing between two sharply different stories that still both sounded reasonable.
The bullish narrative pinned fair value at US$26.29. It referenced XPeng’s proprietary AI hardware and smart-driving stack, along with analyst assumptions of 31.6% annual revenue growth and profit margins moving from a loss to 4.6% over three years.
The more cautious view set fair value at US$18.06. That perspective focused on global EV rivalry, potential pricing pressure, and the risk that regulatory barriers could slow or complicate XPeng’s international expansion.
What The XPeng Evidence Put To The Test
XPeng’s rollout of mass-produced L4 robotaxis and humanoid robot production lines supported the bullish argument about proprietary AI and physical AI products. At the same time, Q2 2026 figures showed revenue at CNY 19,743.593m but a wider net loss of CNY 1,337.064m and net margin falling from -2.6% to -6.8%. The evidence pointed in both directions.
The key lesson is to view tech milestones separately from the income statement. When a thesis leans on margin repair, track net margin and absolute profit each quarter and check whether new products are improving those figures or simply adding capital intensity.
What XPeng’s Drop Leaves You Weighing Today
XPeng trades at US$9.21, which is well below where holders were a year ago, while the selected Narrative’s Fair Value sits above the current price based on its own modelling rather than any settled truth.
The Narrative leans on XPeng’s Physical AI platform across vehicles, robotaxis and humanoid robots. A buyer today must believe those projects eventually support higher margin revenue that can cover heavy R&D and recurring losses.
"XPeng's shift from a pure EV maker to a broader Physical AI group that reuses its in-house chips, models and software across vehicles, Robotaxi and humanoid robots is expected to create multiple revenue streams from a single technology stack and improve long term returns on R&D investment."
The price and this Narrative do not agree. → Uncover what this Narrative says XPeng is actually worth
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 35% below our estimate - focuses on improving margins and expanding higher-value aftermarket support in complex flow systems.
- Company 2 - 24% below our estimate - embeds artificial intelligence across enterprise cloud, workplace productivity, security and software development stacks.
- Company 3 - 43% below our estimate - expands from solar tracking hardware into storage, inverters and integrated energy platform solutions.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com