


Bank of America Securities upgraded Pharvaris (NasdaqGS:PHVS), noting what it sees as an attractive entry point after clinical risk around lead therapy deucrictibant eased and a key FDA decision came into focus.
Recent trading tells a mixed story for Pharvaris. The share price gained 2.38% over the last day and 13.23% over the past week. However, the 90-day share price return is down 7.54% while the 1-year total shareholder return is 36.62%. This suggests that momentum has picked up again as investors reassess regulatory and clinical risk.
Scan how Wall Street’s interest in Pharvaris compares with other late-stage opportunities by reviewing our curated list of 21 high quality undiscovered gems across the market.
Pharvaris now carries a late stage asset, fresh momentum and a higher analyst view after the upgrade. The open question is whether the current US$31.41 share price already reflects that reality or still lags it.
Most Popular Narrative: 45% Undervalued
Against Pharvaris' last close at $31.41, the most followed narrative points to a fair value of $57.33. This implies a sizable valuation gap built on expectations for deucrictibant across multiple angioedema indications and time horizons.
Combined development of deucrictibant immediate release for on demand use and extended release for prophylaxis, backed by data supporting safe concurrent use, can position Pharvaris to capture both acute and chronic hereditary angioedema treatment spend and potentially support higher overall revenue per patient as physicians consolidate therapy around a single mechanism.
See why 2 investors see Pharvaris as 45% undervalued.
Result: Fair Value of $57.33 (UNDERVALUED)
Still, Pharvaris faces real pressure if regulators delay deucrictibant decisions or if ongoing quarterly losses and any future capital raises weigh on shareholder returns.
Find out about the key risks to this Pharvaris narrative.
Another View: Pharvaris Looks Pricey On Book Value
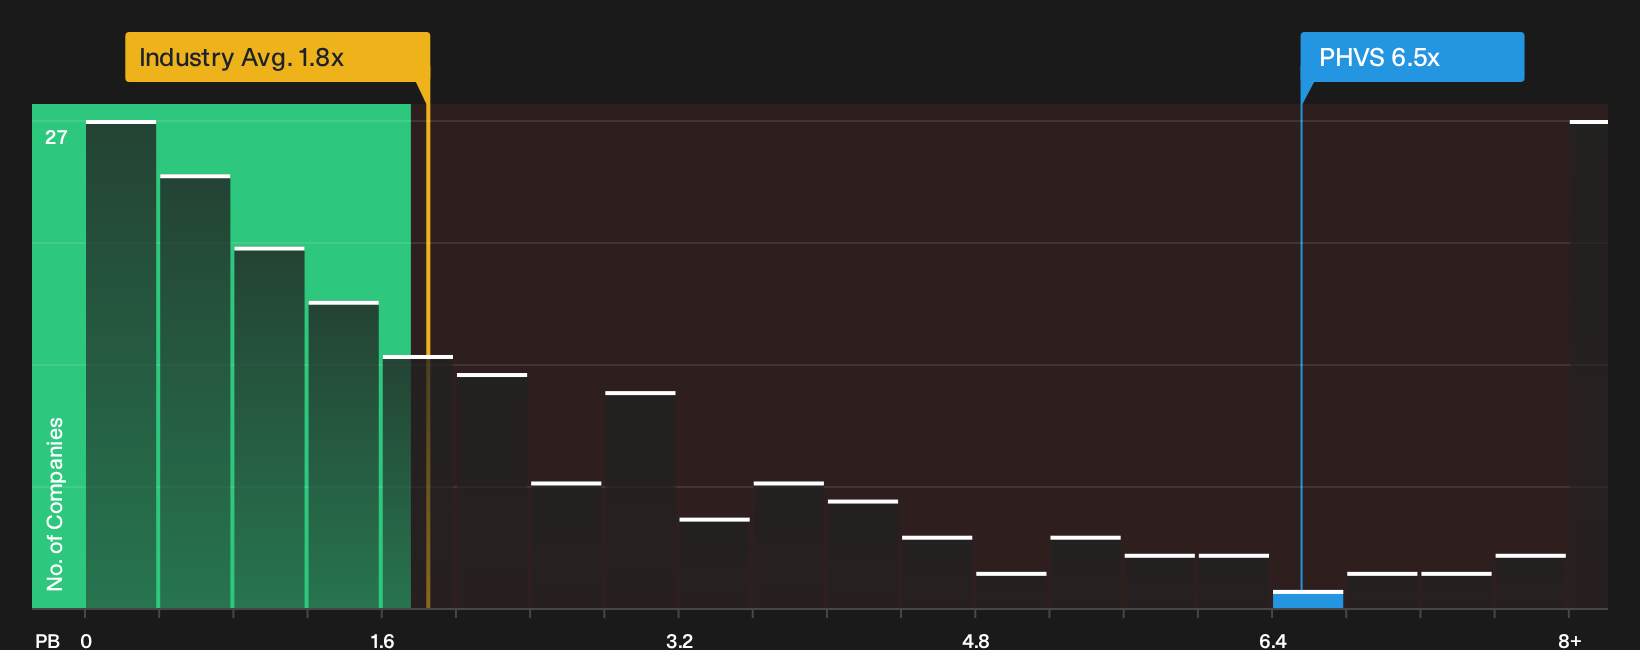
Analyst narratives lean on future earnings for Pharvaris, yet the current P/B ratio of 6.5x is well above both peer levels at 2.5x and the broader US Pharmaceuticals group at 1.8x. That gap signals investors are already paying a steep premium. Does that premium leave much room if the story stumbles?
To see how this premium stacks up against detailed valuation work, including future cash flows and assumptions, it helps to step through the numbers in more detail with our SWS DCF model. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Pharvaris can feel messy, yet waiting for perfect clarity often means reacting late. To understand what investors are weighing, pressure test the upside story against the risks and rewards by stepping through 2 key rewards and 2 important warning signs
Looking for more Pharvaris-sized ideas?
If Pharvaris has you thinking about what else might be hiding in plain sight, do not stop here. Broaden your watchlist with a few targeted searches.
- Target potential upside by scanning a curated set of 29 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their financial profile.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) and focus your research on businesses with stronger financial footing when conditions get tougher.
- Reduce downside surprises by starting with 30 resilient stocks with low risk scores and concentrate your time on companies with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com