


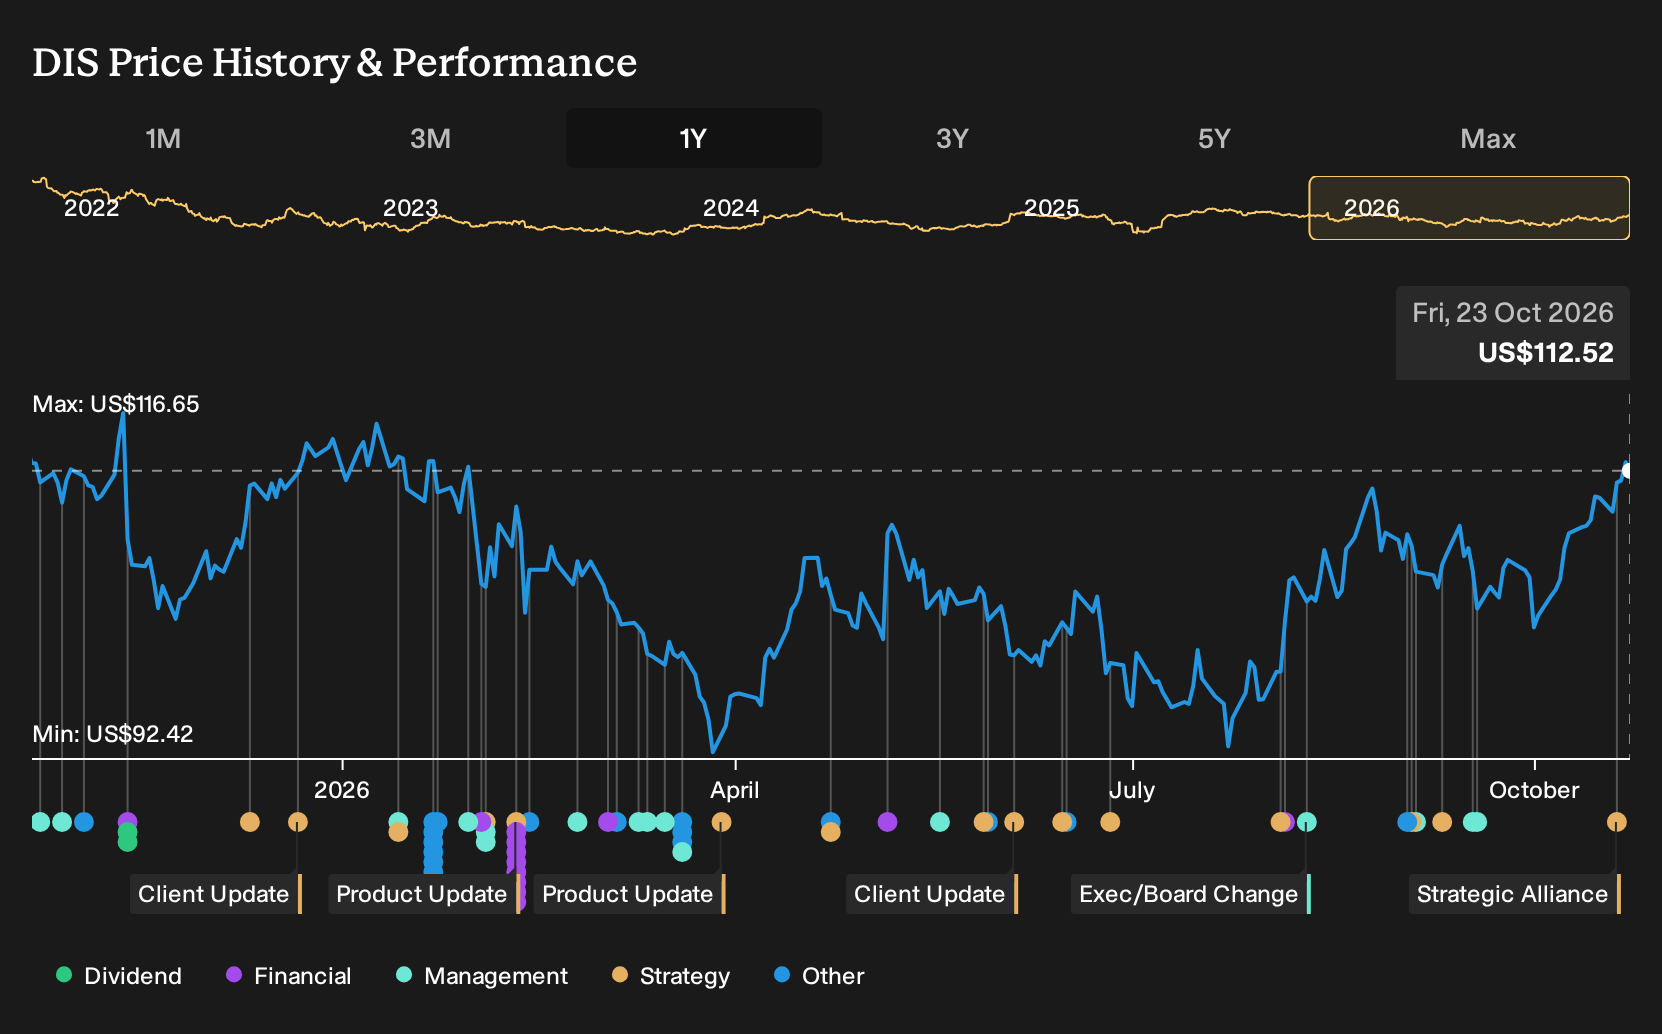
- In October 2026, Shutterfly and Walt Disney announced that Shutterfly will become the Official Photo Gift Partner for Walt Disney World Resort, Disneyland Resort, Disney Cruise Line and Aulani, A Disney Resort & Spa, giving guests new ways to turn Disney PhotoPass images into personalized products.
- The alliance deepens Disney's merchandising reach by tying its park and character IP directly into Shutterfly's customized photo books, home décor, cards, games and ornaments, widening the range of post-trip spending opportunities tied to each vacation.
- The next step is an assessment of how Walt Disney's broader investment narrative could be influenced by monetizing guest photos through this expanded Shutterfly partnership.
Scan beyond Walt Disney and this photo-focused partnership by reviewing hand-picked consumer and experience plays in our 21 high quality undiscovered gems.
Walt Disney Investment Narrative Recap
To own Walt Disney, you need to believe the Experiences flywheel, from parks to cruises, keeps doing the heavy lifting while Disney+ and Hulu sustain double digit streaming margins. The Shutterfly deal ties into that by nudging more spending around each trip, although on its own it looks incremental rather than a major near term driver.
The near term swing factor still sits in streaming. Ad markets for Disney+ and Hulu need to hold up well enough that price changes and subscriber trends offset any weaker ad yields. On the risk side, prolonged softness in Shanghai and Hong Kong parks or higher streaming related legal costs could pressure earnings.
The Shutterfly alliance plugs directly into one of Disney's key catalysts: Experiences expansion. Management has been adding cruise and park capacity to meet demand. Giving guests more ways to spend on photo books, décor and other items linked to each resort visit extends that same Experiences thesis into higher margin merchandise.
This also leans on the IP flywheel that already supports content, streaming and retail. Collections built around Toy Story, Cars or Mickey & Friends give Disney additional ways to monetise franchises without new rides or films. Execution still matters. If regional park demand weakens or legal disputes raise costs, the added photo revenue will not fully offset those pressures.
Walt Disney's narrative projects US$113.7b revenue and US$13.5b earnings by 2029. This aligns with analysts' expectations of 4.8% yearly revenue growth and an earnings increase of about US$4.9b from US$8.6b today.
Uncover why Walt Disney's fair value indicates a 13% potential upside to its current price before sentiment narrows that gap.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between US$117.15 and US$134.63, so opinions on Walt Disney already span a wide pricing band before the Shutterfly announcement is factored in. Consider that in the context of streaming ad pressure or park demand risks, then explore more community views before deciding how you frame Disney in your own portfolio.
Explore 4 other Walt Disney fair value estimates, including one that suggests as much as 20% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Walt Disney research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
If you want to apply the same kind of structured thinking used on Walt Disney to a broader watchlist, the Simply Wall St Screener gives you curated sets of stocks that already meet specific quality or income filters. That saves you from trawling through tickers one by one and lets you focus on which stories you actually want to back.
- For investors hunting for underappreciated quality, start with our 29 high quality undervalued stocks that combine strong fundamentals with prices that sit below fair value estimates.
- If resilience and balance sheet strength matter most to you, filter for companies on the list of solid balance sheet and fundamentals (24 results) to spot businesses with sturdier financial footing.
- Income focused readers can zero in on stocks offering higher yields by reviewing a curated 5 dividend fortresses that prioritize durable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com