


Air Products and Chemicals (APD) just reaffirmed its shareholder payout policy. The board declared a quarterly dividend of $1.81 per share, payable on February 8, 2027 to investors on record as of January 4.
The latest dividend decision lands while Air Products and Chemicals’ share price sits at $307.15, after a small 0.35% pullback on the day but a 9.01% 1 month share price return that hints at building momentum into year end. That short term move sits on top of a 22.63% year to date share price return and a 23.70% 1 year total shareholder return, suggesting investors who stayed invested through recent updates, including the FABTECH 2026 appearance, have been rewarded by both price gains and income.
Scan other dividend-paying industrials showing similar price strength with our curated list of 5 dividend fortresses as you evaluate Air Products and Chemicals alongside its income peers.
After a 9% one month climb, and with a share price that still sits about 10% below average analyst targets and a wider estimated intrinsic value gap, is Air Products and Chemicals genuinely mispriced, or is the market factoring in real risks?
Most Popular Narrative: 11% Undervalued
On the most followed narrative, Air Products and Chemicals screens as undervalued, with that framework pointing to a fair value of $345.11 against the latest close at $307.15, while the analyst work behind it leans heavily on long duration industrial gas and clean energy contracts.
Heavy investments in large scale hydrogen, blue and green ammonia, and carbon capture projects supported by multi decade power and supply agreements in regions such as the Middle East, Asia, and the U.S. Gulf Coast are progressing toward start up, which could support more stable earnings and a higher contribution from contracted volumes to operating margins over time.
See why 75 investors see Air Products and Chemicals as 11% undervalued.
Result: Fair Value of $345.11 (UNDERVALUED)
Still, heavy spending on hydrogen and ammonia projects, as well as any setback at large developments such as NEOM, could pressure returns and challenge the Air Products and Chemicals thesis.
Find out about the key risks to this Air Products and Chemicals narrative.
Another View: Rich Multiples On Air Products and Chemicals
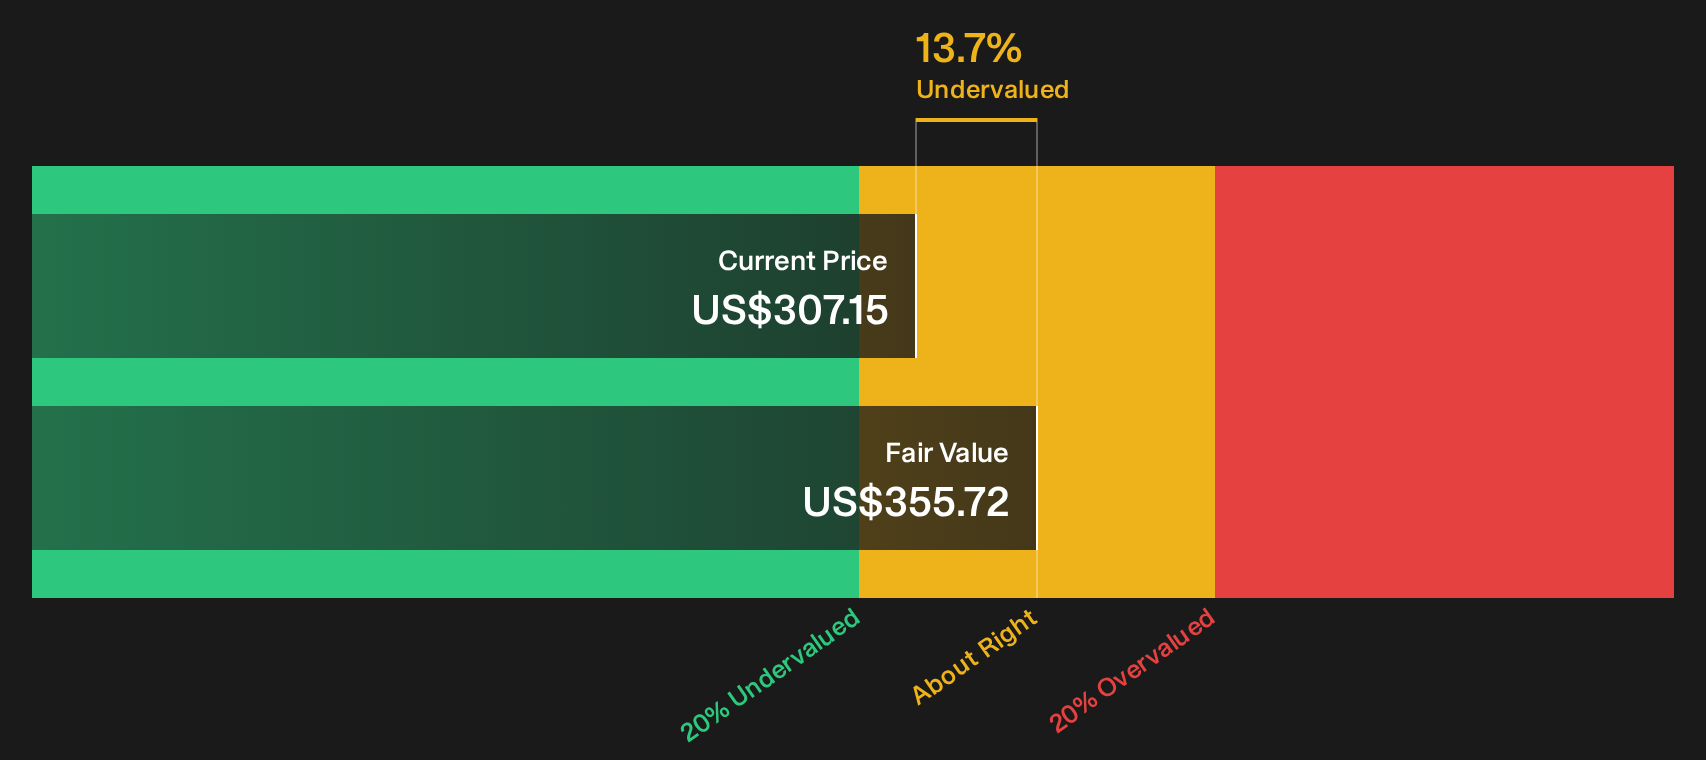
The SWS DCF model flags Air Products and Chemicals as undervalued, with the share price at $307.15 compared with an estimated future cash flow value of $355.72. That 13.7% gap suggests upside based on projected cash generation rather than current earnings.
Price based signals send a different message. APD trades on a P/S ratio of 5.4x compared with 1x for the wider US Chemicals group and 4.1x for its peer set, while the fair ratio sits closer to 2.3x. That kind of premium can mean investors are paying ahead of the story. How comfortable are you with that trade off between cash flow upside and richer sales multiples?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Air Products and Chemicals can be confusing, so move quickly, review the data independently, and decide where you land on 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Air Products and Chemicals?
If Air Products and Chemicals has your attention, do not stop there. Broaden your watchlist with other opportunities that fit clear, data driven criteria.
- Target sturdier portfolios by focusing on companies with strong finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value opportunities by reviewing the 29 high quality undervalued stocks tailored for investors who want quality at a measured price.
- Aim for stability first and filter for businesses with steadier risk profiles through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com